NV本周迎来一个安抚其低迷股票和债券的机会,这家Jeep和标致制造商将发布财报,而外界对其扭亏计划的担忧正笼罩着这一背景。
NV gets an opportunity to calm its slumping stock and bonds this week when the Jeep and Peugeot maker reports earnings against a backdrop of unease over plans for a turnaround.
首席执行官安东尼奥·菲洛萨重振这家陷入困境集团的战略,其信心已被持续不断的中国竞争、欧洲疲软的价格环境以及高企的原材料成本所侵蚀,这让投资者心中的疑问多于答案。
Confidence in Chief Executive Officer Antonio Filosa’s strategy for reviving the struggling group has been eroded by unrelenting Chinese competition, weak pricing in Europe and high raw-material costs, leaving investors with more questions than answers.
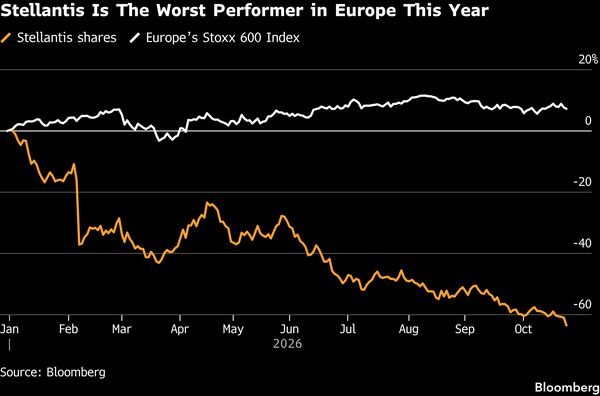
该股今年已下跌逾60%,跌至历史低点,Stellantis的债券也跌至历史最低水平,这位CEO周三公布业绩时将需要给出强有力的安抚之词。
The shares have fallen more than 60% to record lows this year and with Stellantis bonds also plumbing all-time depths, the CEO will need to deliver strong words of reassurance when the company reports on Wednesday.
“市场现在坚定地将Stellantis视为一个‘需要拿出证据’的故事,”持有这家菲亚特制造商股份的Acomea Sgr投资组合经理法比奥·卡尔达托表示。“能见度有限,加上整个行业面临的挑战,使得人们很难相信公司给出的指引以及5月公布的2030年计划。”就业绩本身而言,分析师们远不乐观。根据彭博汇编的12份预估的平均值,第三季度净营收预计将从上年同期的372亿欧元降至364亿欧元(410亿美元)。但更令许多人担忧的是负自由现金流,估计为34亿欧元。
“The market now firmly views Stellantis as a ‘show me’ story,” said Fabio Caldato, portfolio manager at Acomea Sgr, which owns the Fiat maker’s shares. “Limited visibility and the challenges facing the industry as a whole make it hard to give credit to the guidance and the 2030 plan unveiled in May.”For the results themselves, analysts are far from optimistic. Third-quarter net revenue is seen falling to €36.4 billion ($41 billion) from €37.2 billion a year earlier, according to the average of 12 estimates compiled by Bloomberg. But of greater concern to many is negative free cash flow that’s estimated at €3.4 billion.
汇丰控股分析师迈克尔·廷德尔在10月23日的一份报告中写道,“鉴于产量水平疲弱,现金消耗的规模是一个未知风险。”
The “scale of cash burn is an unknown risk given weak production levels,” HSBC Holdings Plc analyst Michael Tyndall wrote in an Oct. 23 note.
阅读:从7月起,Stellantis CEO难以赢得投资者支持:汽车观察。廷德尔表示,他担心“美国可能需要进行去库存,以及为恢复实质性竞争力所需的现金流出。”他给予该股减持评级,其3.30欧元的目标价为彭博追踪的所有分析师中最低,意味着较当前水平还有约10%的下行空间。
READ: From July, Stellantis CEO Struggles to Win Over Investors: Auto Monitor Tyndall said he’s concerned about “the potential need to destock in the US and cash outflow required to bring substance back to a competitive standing.”He has a reduce rating on the stock and his price target of €3.30 is the lowest of all analysts tracked by Bloomberg, implying a further 10% downside from current levels.
其他人同样持怀疑态度。巴克莱分析师亨宁·科斯曼表示,Stellantis是欧洲汽车行业中最难执行的案例。
Others are similarly skeptical. According to Barclays Plc analyst Henning Cosman, Stellantis is the most difficult execution story in the European autos sector.
Cosman 在本月的一份报告中写道,他预计要等到第四季度“充其量”才能看到投资论据所需的可持续改善证据,并补充称,他认为公司中期规划中的一些底层假设“相对不兼容”。这种疑虑并未被做空者忽视。根据标普全球市场智讯的数据,截至周四,Stellantis 的外借股份——即做空兴趣的指标——约占其自由流通股的 19%。这是 10 多年来的最高水平。
Cosman doesn’t expect any proof of sustainable improvement for the investment case until the fourth quarter “at the very earliest,” he wrote in a note this month, adding that he views some underlying assumptions in the company’s mid-term plan as “relatively incompatible.”Such doubt isn’t lost on short sellers. Shares out on loan — an indication of short interest — was about 19% of Stellantis’s free float as of Thursday, according to data from S&P Global Market Intelligence. That’s the highest level in more than 10 years.
并非所有人都如此看空。德意志银行的 Christoph Laskawi 表示,虽然他预期将出现一个疲软的季度,但他不认为 Stellantis 会改变全年展望,且宽泛的指引目标仍在触手可及之处。
Not all are so bearish. Deutsche Bank AG’s Christoph Laskawi said that while he’s expecting a soft quarter, he doesn’t anticipate Stellantis changing its full-year outlook and broad guidance remains within reach.
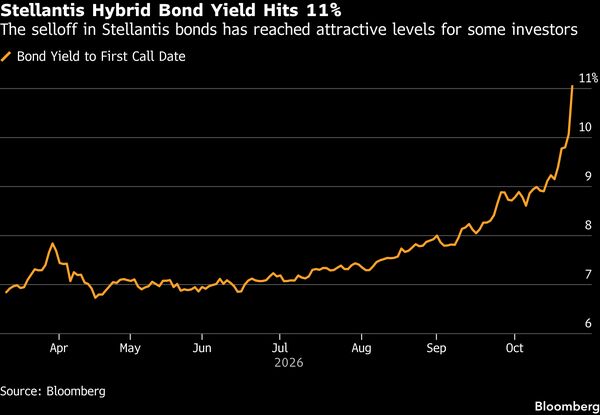
对于一些债权投资者而言,抛售已过度。该公司的混合债券——一种成本更高、在公司债务偿还顺序中排名较低、且被信用评级机构视为 50% 权益的债务形式——目前的首次赎回日收益率超过 11%,而今年早些时候发行时的收益率为 6.875%。
And for some credit investors the selloff has gone too far. The firm’s hybrid bonds — a more expensive debt format that ranks lower in a company’s borrowing stack and is treated as 50% equity by credit rating agencies — now trade at a yield to first call date of more than 11%, compared with 6.875% when they were sold earlier this year.
Acomea 的 Caldato 近期买入了部分永续债,他表示:“虽然恢复正向自由现金流肯定充满挑战,但我们不认为 Stellantis 的资产负债表应当定价为一场全面的金融危机,而这正是当前债券价格所暗示的。”
“While returning to positive free cash flow will certainly be challenging, we do not think Stellantis’s balance sheet should be pricing in a full-blown financial crisis, which is what current bond prices would imply,” said Acomea’s Caldato, who recently bought some of the perpetual bonds.
尽管如此,即使是最乐观的人士也认识到谨慎的必要性。Caldato 说:“要让股价回升,投资者将需要看到证据,证明恢复正向自由现金流的路径是真实且切实可行的。”
Still, even the most optimistic recognize the need for caution. “For the shares to recover, investors will need evidence that the path back to positive free cash flow is real and tangible.”Caldato said.