汽车制造商在纯语义层面上属于“科技”公司:内燃机是极少数真正定义现代生活的发明之一。它也可追溯至19世纪,因此汽车制造商总体上不被视为科技股。通用汽车公司似乎决心改变大众对这一点的固有认知。其朝这个方向迈出的最新一步,是从纽约证券交易所迁往带有硅谷色彩光环的纳斯达克。困难在于,光环的光芒也会为大型车企投下阴影。
Automakers are “technology” companies on a purely semantic level: The internal combustion engine is one of a select few inventions that truly define modern life. It also dates back to the 19th century, so automakers are not, by and large, regarded as technology stocks. General Motors Co. seems set on changing the wisdom of the crowd on this. Its latest step in that direction involves relocating from the New York Stock Exchange to Nasdaq, with its silicon-inflected aura. The difficulty is that the glow of an aura also casts a shadow for Big Auto.
通用汽车一直在进行某种重塑之旅。该公司最近举办了一场科技活动,展示其OnStar车载信息服务、即将推出的增强型驾驶辅助功能、下一代电动汽车平台,以及由人工智能赋能的更快车型开发流程。它还领投了位于湾区、致力于研发钠离子电池的初创公司Peak Energy。通用汽车今夏早些时候还宣布与洛克希德·马丁公司建立国防合作伙伴关系。迁往纳斯达克符合这一背景。
GM has been on something of a reinvention tour. The company recently hosted a tech event showcasing its OnStar connectivity service, forthcoming enhanced driver assistance features, a next-generation electric vehicle platform and faster model development enabled by artificial intelligence. It also led a funding round for Peak Energy, a Bay Area startup developing sodium-ion batteries. GM announced a defense partnership with Lockheed Martin Corp. earlier this summer. The Nasdaq move fits the context.
展开这一背景来看,底特律多年来一直活在一家它最初轻视、后来羡慕的公司阴影下:特斯拉公司。埃隆·马斯克旗下的这家公司销量仅为通用汽车的约四分之一,约为福特汽车公司的三分之一,但其市值却约为两者合计的14倍。其市盈率高达近200倍,而两家老牌车企的市盈率徘徊在个位数中段。特斯拉备受青睐,并非因为其造车业务卓越——远非如此——而是因为它以某种方式说服了投资者,它其实不是一家汽车制造商,而是一家毗邻太空领域的AI和机器人神童。顺带一提,特斯拉在纳斯达克上市。
To expand on that context, Detroit has for several years lived in the shadow of a company that it first dismissed and then came to envy: Tesla Inc. Elon Musk’s company sells only about a quarter of the vehicles that GM does, and around a third of what Ford Motor Co. moves, but its market cap is about 14 times bigger than theirs combined. Its earnings multiple scrapes 200 times while theirs tread water in mid-single digits. Tesla is beloved not because its car operation is stellar — far from it — but because it has somehow convinced investors that it is not, in fact, an automaker but instead a space-adjacent AI and robotics wunderkind. Tesla is listed on Nasdaq, by the way.
通用汽车和福特汽车有时也曾享受过较高的估值倍数,最显著的一次是疫情导致新车短缺、并出现了一段罕见的极强定价权时期——这在长期产能过剩的行业中实属罕见。福特的估值今夏也曾因宣布计划将一家工厂改造为生产电网电池、从而蹭上数据中心热潮而短暂受惠。
GM and Ford have sometimes tasted higher multiples, most notably when the pandemic caused a shortage of new vehicles and a period of extreme pricing power, rare in a sector with chronic excess capacity. Ford’s valuation also enjoyed a brief fillip this summer when it announced plans to switch a plant over to making grid batteries and thereby got caught up in the data-center hype.
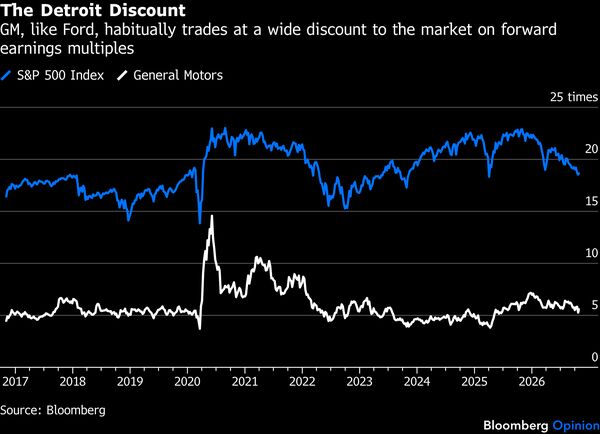
然而,这些偶尔的亮点并未让这两只股票“燃”起来。相较于任何与人工智能相关的题材,一家铝供应商发生火灾所带来的持续且相对平庸的影响,对福特今年的冲击反而更大。通用汽车目前的远期市盈率较标普500指数折价约70%,这属于常态。
Yet the occasional spark has not led these stocks to catch fire. The lingering, and relatively banal, impact of a fire at an aluminum supplier has been a bigger deal for Ford this year than anything AI-related. GM today trades at about a 70% discount to the S&P 500 on forward earnings multiples and that’s situation normal.
通用汽车试图通过转战纳斯达克、加入特斯拉和Rivian汽车公司的行列,以吸引更多投资者关注,这合情合理。通用汽车指出,其可能有资格纳入纳斯达克100指数,这将默认带来跟踪基金的资金流入。
It makes sense for GM to try to garner more attention from investors by joining the likes of Tesla and Rivian Automotive Inc. over at Nasdaq. GM noted that it may be eligible for inclusion in the Nasdaq 100, which would bring in tracking-fund money by default.
更大、也更扑朔迷离的问题是,市场对其的叙事是否会随之改变。通用汽车的技术日聚焦于所有正确的方向,尤其是致力于缩短开发周期——这是中国竞争对手已臻完美的强项。随着产品价值随时间逐渐从发动机和车身向算力、软件和订阅服务迁移,在新芯片与电气架构、电池以及OnStar(安吉星)上的投资合情合理。
Whether the narrative also shifts is the bigger, and far murkier, question. GM’s tech day focused on all the right things, especially the drive toward the sort of shorter development cycles that Chinese rivals have perfected. And as product value migrates over time from the engine and shell toward computation, software and subscription services, investment in new chip and electrical architecture, batteries and OnStar make sense.
当然,挑战在于,极度依赖平淡的美国汽车市场、耗油量大的卡车和SUV才是当下支付通用汽车账单的业务。按共识预测,通用汽车未来三年每股收益增速为18%,在目前的纳斯达克100指数成分股中将排名靠后(中位数为52%)。
The challenge, of course, is that gas-guzzling trucks and SUVs geared overwhelmingly to a flat US auto market pay GM’s bills today. At 18%, the consensus forecast for GM’s earnings-per-share growth over the next three years would rank toward the bottom of the current Nasdaq 100 (the median is 52%).
即使这种增长部分也是建立在通用汽车新的回购计划之上的,该计划规模高达其当前市值的30%。通用汽车三年前开始大规模回购股票;最初是为了在其Cruise无人驾驶出租车业务惨败后起到“熔断”作用,但随后成为其提振长期低估值的更广泛努力的一部分。然而,将200亿美元投入回购而非新业务,同时又试图重新定位为一只以技术为导向的成长股,这两者之间存在无法回避的张力。
Even that growth is predicated, in part, on GM’s new buyback program, equivalent to a whopping 30% of its current market cap. GM began buying back stock in earnest three years ago; first as a circuit breaker to move on from the debacle of its Cruise robotaxi operation but then as part of its broader effort to lift that stubbornly low valuation. Yet there is an inescapable tension between plowing $20 billion into buybacks — rather than new ventures — while also repositioning as a tech-forward growth stock.
随着汽车行业的转型,通用汽车的竞争对手不仅包括其惯常的同行——他们正进一步拥挤进入美国市场。还包括目前因关税而被挡在门外的中国车企,以及资金雄厚的纳斯达克老牌巨头,如特斯拉和Alphabet公司,后者为Waymo LLC提供资金,其资本支出预算比通用汽车高出一个数量级以上。通用汽车的新投资者群体或许能提振公司的叙事,但也同样可能使其黯然失色。
As the auto industry transforms, GM’s competitors include not just its usual peers, who are crowding further into the US. They also include Chinese automakers kept at bay by tariffs (for now) and, increasingly, deep-pocketed Nasdaq incumbents like Tesla and Alphabet Inc., the latter of which funds Waymo LLC and has a capital expenditure budget that dwarfs GM’s by more than an order of magnitude. As much as GM’s new crowd may lift the company’s narrative, they could just as well overshadow it.