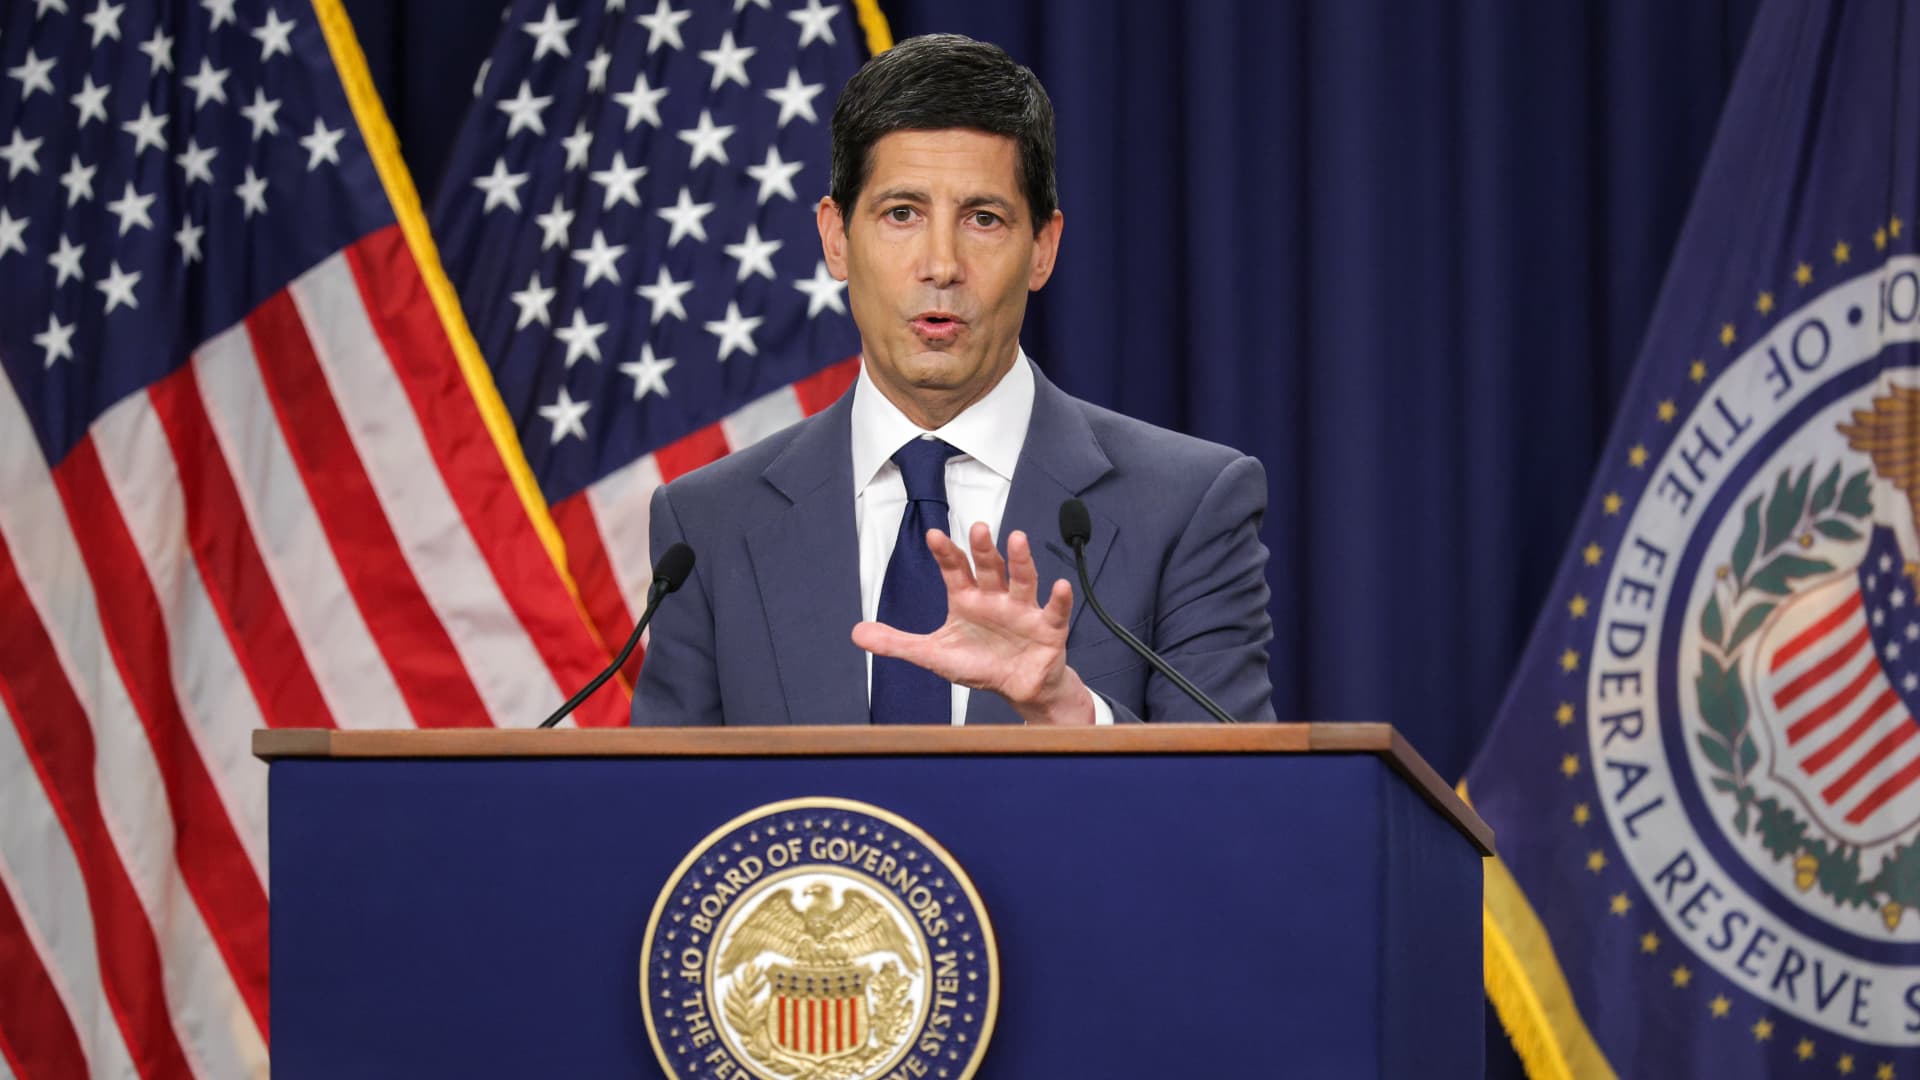
凯文·沃什已经不需要再证明自己了。这位美联储主席周三举行的记者会,与他刚上任时的早期公开露面截然不同,当时他常常显得被逼入绝境。他已经表明,他愿意让市场去猜测他的走向——至少在某种程度上是这样。而且他已开始动用自己的权威来重塑这个机构。
Kevin Warsh is done proving himself. The Federal Reserve chairman's press conference Wednesday was sharply different from his early appearances in the job, when he often seemed backed into a corner. He's shown he is willing to let the markets guess where he is going — at least to a point. And he has started using his authority to reshape the institution.
沃什是由一位曾表示降息是其美联储主席人选试金石的总统所任命的。当联邦公开市场委员会在6月和7月选择维持利率不变时,即便通胀率远高于美联储2%的目标,大批评论人士仍对这位新主席的信誉提出了质疑。随后,联邦公开市场委员会在9月做出了加息决定,沃什对经济发表了如此鹰派的解读,以至于市场向相反方向剧烈摇摆。投资者原本认为美联储本周可能会锁定加息,直到两名高级官员出面,似乎刻意缓和了市场的预期。
Warsh was appointed by a president who said cutting interest rates was a litmus test for his choice for Fed chair. When the Federal Open Market Committee opted to hold rates flat in June and July, even with inflation well above the Fed's 2% target, a swarm of commentators questioned the new chairman's credibility. The FOMC's subsequent decision in September to raise rates came with such a hawkish reading of the economy by Warsh that the markets swung sharply in the opposite direction. Investors thought the Fed might be locked into a rate hike this week until a pair of top officials came out and appeared to deliberately temper market expectations.
本周,沃什把这一切都抛在了脑后。他否认了美联储正走在既定道路上的任何预期:“如果我们对货币政策的实施有了一个坚定的结论,我们今天就会大肆宣扬并宣布这一结论,”他说。
This week, Warsh put all that behind him. He disavowed any expectation that the Fed is on a set course: "If we had a firm conclusion about the conduct of monetary policy, we'd announce it to much fanfare today," he said.
但沃什也释放出了一个强烈信号,即他目前的倾向是加息。“虽然整体金融状况有所收紧,但我既不愿意也没有说它们已经紧缩,”他说。
But Warsh also gave a strong signal that his current lean is toward higher rates. "While overall financial conditions are tighter, I'm unwilling and unable to call them tight," he said.
他在保留自己选择余地的同时,也为12月的加息奠定了理论基础,以防通胀居高不下。
He was preserving his options while laying the intellectual groundwork for a hike in December, should inflation remain stubborn.
沃什拒绝证实市场上的普遍猜测,即那些淡化加息预期的官员是奉他的旨意行事的。美联储内部人士曾表示,美联储的副主席们通常会与主席协调信息传达。
Warsh declined to confirm the widespread assumption in the markets that the officials who had talked down the markets had done so at his direction. Fed insiders have said that the Fed's vice chairs usually coordinate messaging with the chair.
“如果认为我是某种无所不知、到处发号施令的人,那这就不是我所了解的那个联邦公开市场委员会,”沃什说。然而,市场确实接收到了美联储本周不会加息的信息。如果沃什想通过他的副手们发出本属禁忌的前瞻性指引,他现在已经有了合理的否认空间。
"To suggest somehow that I am some kind of all-knowing person sending messages out, that's not the committee of the FOMC that I know," Warsh said. And yet the market got the message that the Fed wouldn't hike this week. If Warsh wants to give otherwise taboo forward guidance through his lieutenants, he now has plausible deniability.
这就是沃什的行事风格:他思维灵活,高度专注于实现自己的目标。
This is Warsh's MO: He is intellectually flexible and highly focused on achieving his goals.
例如,他组建的旨在推动政策变革的工作小组的目标之一,就是改变美联储衡量通胀的方式。但在他对抗通胀的承诺受到质疑时,这是不可能做到的。9月份的加息在很大程度上回应了那些质疑他并非真心放慢物价涨幅的怀疑论者,而且如果有必要,他愿意实施更多的加息。
For instance, one of the goals of the task forces he has assembled to kick-start policy changes is to change the way the Fed measures inflation. But that was impossible while his commitment to fighting it was in question. September's rate hike does a lot to answer the skeptics who said he wasn't serious about slowing price increases, and he is willing to deliver more rate increases, if necessary.
“如果你认为我们会容忍百分之二点几的某个通胀目标,那就让我们打消你的这种念头吧,”沃什周三表示。目标就是明确的2%。只要经济保持强劲,他的言论就是通胀率走高的秘诀。
"If you think that we're tolerating some inflation target somewhere in the twos, let us disabuse you of it," Warsh said Wednesday. The target is 2% flat. His remarks are a recipe for higher rates as long as the economy stays strong.
在12月的下次会议召开之前,沃什和联邦公开市场委员会将掌握大量新数据来阐明他们的立场。这反过来又可能有助于他证明生产率正在提高,从而在不引发通胀的情况下允许更多增长。
Warsh and the FOMC will have a raft of new data before the next meeting, in December, to make their case. That could, alternatively, help him make the case that productivity is rising, allowing for more growth without inflation.
与此同时,沃什在美联储做出的其他变革也开始发挥作用。他周三宣布了一项计划,旨在减少联邦公开市场委员会在未来两年内预定对利率进行投票的次数。美联储将继续保持每年开会八次,但在2027年的一场会议和2028年的两场会议上,将跳过关于是否更改利率的投票。此举的效果是贬低了相当一部分美联储官员的言论价值。
Meanwhile, Warsh's other changes at the Fed are starting to take effect. He announced a plan Wednesday to reduce the number of times the FOMC is scheduled to vote on interest rates over the next two years. The Fed will keep meeting eight times a year, but will skip a vote on whether to change rates at one meeting in 2027 and two in 2028. That move has the effect of devaluing a good chunk of Fedspeak.
当地方联储主席的评论是在利率决议做出多达三个月前发表时,市场不会给予太多关注。在联邦公开市场委员会长达一年的决策者轮值期间,地方联储主席预定的投票权也减少了一次。
The market won't pay much mind to a marginal regional Fed president's comments when they come as much as three months ahead of a rate decision. Regional presidents also get one fewer scheduled vote in their year-long rotations as decision-makers on the FOMC.
美联储主席保留在认为有必要改变利率时随时召开临时会议的权力。
The Fed chairman retains the authority to call an impromptu meeting at any time should he see the need to change rates.
但沃什的这种行事方式也存在风险,特别是当他进一步退居幕后之际。美联储透明度的倡导者认为,阳光能为官员们的辩论增添更多严谨性。
But there are risks to Warsh's way of doing business, especially as he recedes further behind the curtain. The advocates for Fed transparency believe that sunlight adds more rigor to officials' arguments.
资产管理公司PGIM的美国首席经济学家罗伯特·索金表示,这可能已经成了一个问题。他属于那种认为通胀过高、无法为美联储本周不加息的决定进行辩护的阵营。
That could already be a problem, said Robert Sockin, chief U.S. economist at asset manager PGIM. He is in the camp that thinks inflation is running too hot to justify the Fed's decision not to raise rates this week.
索金说:“虽然数据总是越多越好,但沃什并没有充分解释为什么这种背景不能成为加息的理由,特别是考虑到他曾表示,虽然他认为金融状况已经收紧,但他不会说它们已经紧缩。”
"While more data is always better, Warsh did not sufficiently explain why this backdrop did not justify a rate increase, particularly given his comment that while he thinks financial conditions have tightened, he would not say they are tight," Sockin said.
索金说,维持利率不变是一个“政策失误”,“而一个循序渐进的美联储可能意味着它不得不升得更高,从而机械性地推高了经济衰退的风险”。
It was a "policy mistake" to hold, "and a gradual Fed likely means one that has to hike higher, mechanically raising recession risk," Sockin said.
沃什这种方法的全部后果可能要几个月后才会明朗。这给了他在重塑美联储时腾挪的空间。但也意味着,等待收紧政策的后果可能在为时已晚时才会显现出来。
The full consequences of Warsh's approach may not become clear for months. That gives him room to maneuver as he reshapes the Fed. But it also means the consequences of waiting to tighten may not become apparent until it's too late.