投资者担忧,美联储主席凯文·沃什每年减少利率决策次数的计划,可能会给32万亿美元的国债市场带来更多波动。
Investors are worried that Federal Reserve Chairman Kevin Warsh’s plan to reduce the number of interest-rate decisions each year could be a recipe for more volatility in the $32 trillion Treasury market.
沃什在美联储周三的政策会议上维持利率不变后宣布了该计划,计划将每年八次利率决策逐步过渡为六次,剩下的两次会议将用于更广泛的战略讨论。这一举措将使明年的决策次数减少到七次,旨在给官员们留出“时间和空间”进行审议,他说。
Announced by Warsh after the Fed left rates unchanged at Wednesday’s policy meeting, the plan would phase in a shift to six rate decisions a year from eight, with the remaining two gatherings reserved for broader strategic discussions. The move, which would cut the number of decisions down to seven next year, is intended to give officials “time and space” for deliberations, he said.
然而,对交易员而言,这增加了沃什下美联储变得更不可预测的更广泛趋势,包括他放弃前瞻性指引——基本上就是提前透露政策举措——这可能会随着时间的推移增加市场动荡。
To traders, however, it adds to a broader shift under Warsh toward a less predictable Fed, including his retreat from forward guidance — essentially telegraphing policy moves — that could increase market turbulence over time.
交易员表示,决策之间更大的间隔可能意味着美联储需要偶尔实施更大幅度的利率削减或加息。这一转变也增加了在预定会议之间采取紧急行动的可能性,可能会推动短期国债出现更大波动,并提高投资者持有长期债务所要求的溢价。
Bigger gaps between decisions could mean the Fed will need to occasionally deliver larger rate cuts or increases, they said. The shift also raises the likelihood of emergency action between scheduled meetings, potentially fueling bigger swings in short-dated notes and boosting the premium investors demand to hold longer-term debt.
“这是迄今为止最明确的信号,表明他的美联储无意在利率方面充当波动抑制器,并且完全愿意在条件允许时通过意外公告增加波动性,”衍生品路径公司资产负债表策略总监艾萨克·惠勒表示。
“This is the clearest signal yet that his Fed has no interest in being a vol suppressor in rates, and is perfectly willing to add to volatility with surprise announcements if conditions warrant,” said Isaac Wheeler, managing director of balance sheet strategy at Derivative Path.
政策决策减少还可能减少美联储在当前周期收紧货币政策的机会,在此期间,美联储预计将继续加息以抑制通胀。交易员表示,这总体上对短期收益率有利,即使政策不确定性可能会推高长期利率。
Fewer policy decisions could also reduce opportunities for the Fed to tighten monetary policy in the current cycle, during which it is expected to continue raising rates in order to stave off inflation. That’s bullish for shorter term yields on the whole, even as policy uncertainty threatens to lift longer term rates, traders said.
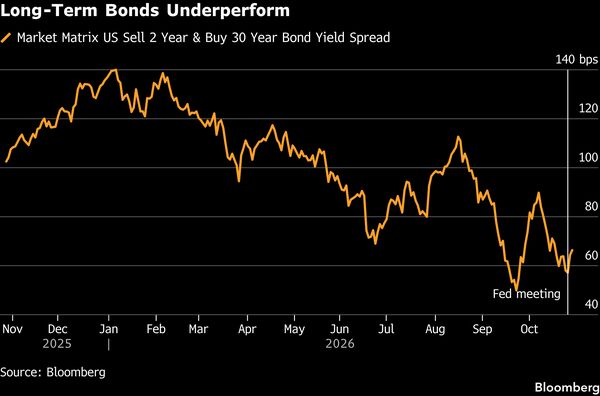
该公告,加上沃什在新闻发布会上的鸽派基调,推动周三短期国债出现上涨。长期期限表现较弱,导致收益率曲线陡峭化。自周三以来,30年期收益率相对于2年期收益率上升了约10个基点。
The announcement, coupled with Warsh’s dovish tone at the press conference, helped drive a rally in shorter-dated Treasuries on Wednesday. Longer maturities underperformed, steepening the yield curve. Thirty-year yields have risen about 10 basis points relative to two-year yields since Wednesday.
从长期来看,“你正在给曲线增加更多风险溢价,因为你注入了这些波动事件,”联合博时集团固定收益部主管斯科特·迪马焦说。
Over the long term, “you’re building more risk premium into the curve because you inject these volatility episodes,” said Scott DiMaggio, head of fixed income at AllianceBernstein.
沃什曾表示,前瞻性指引限制了美联储的灵活性,应仅在经济危机时期使用。
Warsh has suggested that forward guidance limits the Fed’s flexibility and should be reserved only for times of economic crisis.
自5月上任以来,他一直承诺带来“体制变革”,并委托成立一个工作组,审查央行的沟通策略,包括新闻发布会安排和官员政策预测的点阵图。
He has promised to bring “regime change” since taking office in May, and commissioned a task force to examine the central bank’s communication strategy, including the press conference schedule and the dot-plot of officials’ policy projections.
沃什首次在美联储7月会议上提出减少政策决策次数的想法。周三,他表示,这一改变将使决策者能够“对重大问题重新思考”。周三的公告“标志着美联储‘前瞻性沉默’新时代的开始,以及美联储沟通的进一步变化,”摩根大通资产管理公司墨尔本全球市场策略师凯里·克雷格说。
Warsh first raised the idea of reducing the number of policy decisions at the Fed’s July meeting. On Wednesday, he said the change would allow policymakers to think “anew about big questions.”Wednesday’s announcement “marks the start of a new era of ‘forward silence’ at the Fed, and further changes to Fed communications,” said Kerry Craig, global market strategist at JPMorgan Asset Management in Melbourne.
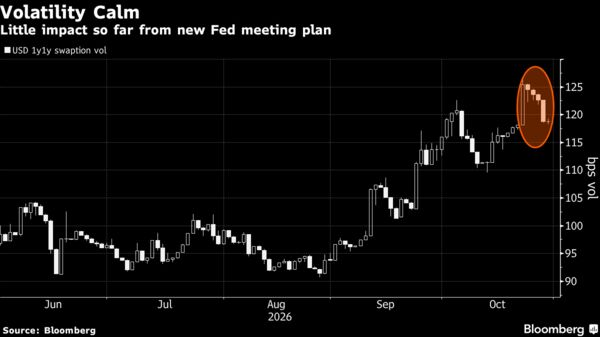
目前,衡量两年期利率波动率的指标几乎没有变动,部分原因是新安排的细节仍然稀缺,交易员表示。
For now, measures that gauge rate volatility over a two-year horizon have barely moved, in part because details of the new schedule remain scarce, traders said.
美联储尚未说明2027年哪次会议将转变为战略讨论,仅表示将在秋季举行。交易员和经济学家表示,不包含季度经济预测的10月会议是最可能的候选。
The Fed has yet to say which 2027 meeting will be converted into a strategy discussion, beyond indicating it will be in the fall. Traders and economists say the October meeting, which doesn’t include quarterly economic projections, is the most likely candidate.
直接影响也可能有限,因为大多数市场参与者押注美联储将在一年后停止加息。隔夜指数互换在9月和12月会议之间基本持平,表明如果10月会议被取消为决策日期,影响将不大。
The immediate impact may also be limited because most market participants are betting the Fed will be done hiking rates a year from now. Overnight-indexed swaps are broadly flat between the September and December meetings, suggesting little disruption if October is dropped as a decision date.
尽管如此,投资者表示,将更少的利率决策与更少的美联储指引相结合,其长期后果可能影响深远。
Still, investors say the longer-term consequences of combining fewer rate decisions with less Fed guidance could be far-reaching.
Thornburg Investment Management的投资组合经理阿里·哈桑表示:“更少的决策会议加上没有前瞻性指引,意味着每次会议前后都会出现更大幅度的重新定价,利率波动也将比市场目前定价的更大。”
“Fewer decision meetings plus no forward guidance are a recipe for bigger repricing around each one, and more volatility around rates than markets are currently pricing,” said Ali Hassan, portfolio manager at Thornburg Investment Management.