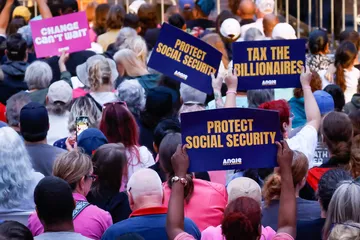
法国长期积聚的诸多矛盾在抗议和骚乱中全面爆发。政府借贷成本上升成为关键压力点——这是债券持有人因养老金改革迟迟不见起色、福利国家规模过于庞大而失去耐心发出的信号。美国人理应引以为戒。
Many long simmering tensions boiled over in France’s protests and riots. Rising borrowing costs for the government proved a crucial pressure point — a message from bondholders grown impatient with a lack of pension reform and the country’s enormous welfare state. Americans would do well to pay attention.
当利率接近零时,债务仿佛不要钱。一个承诺为所有人提供安全与保障的更大政府似乎触手可及。自2019年以来,法国新增借贷达1万亿欧元(约合1.1万亿美元)。安全的另一面是增长放缓,既源于更大规模的国家挤占私营部门,也源于更多监管拖累经济。在借贷廉价时,这并非大问题。但利率上升与人口老龄化如今威胁着法国及欧洲其他地区的整个安全体系。
When interest rates were near zero, debt felt free. A bigger government that promised safety and security for everyone seemed possible. France has added €1 trillion ($1.1 trillion) in borrowing since 2019. The flip side of safety is less growth, both from a bigger state that crowds out the private sector and more regulation that slows the economy. This didn’t matter so much when borrowing was cheap. Higher rates and an aging population now threaten the entire apparatus of safety in France and other parts of Europe.
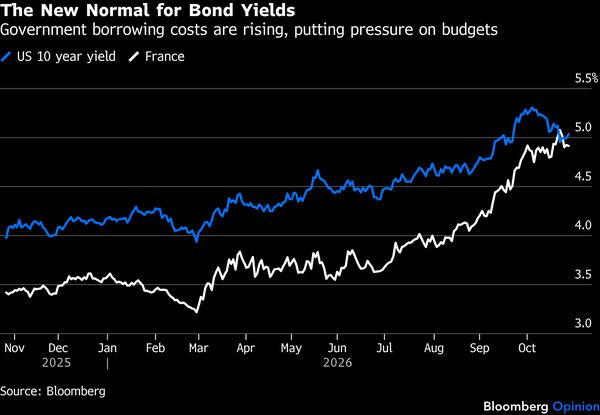
美国无法置身于欧洲这场重大风险清算之外。美国长期利率似乎正在5%左右企稳,与法国类似。美国利率较高有诸多原因:科技公司借贷形成竞争、通胀较高、债务负担日益加重。但5%也是长期债券收益率长期以来的大致平均水平。利率可能进一步上行,也可能下降,但可以合理假设美国正围绕一个新常态起舞,或者正在回归从前的常态。
America isn’t insulated from Europe’s great risk reckoning. Long-term rates appear to be settling around 5% in the US, like in France. There are many reasons why rates are higher here: competition from borrowing by technology companies, higher inflation and a growing debt burden. But 5% is also traditionally what long-term bond yields have broadly averaged. Rates may go higher yet, or fall, but it is reasonable to assume that the US is dancing around a new normal or returning to what was normal all along.
较高利率未必构成问题。美国经济在5%甚至更高利率下曾繁荣发展。但过渡期可能艰难。美国像法国一样,扩大了国家规模,却无法靠更高利率来支付账单。预算缺口约占经济总量的6%,年度利息支出已超越国防预算且将继续攀升。除了对最富有的美国人增税,几乎没有削减福利或增税为其买单的意愿,即便对最富有人群征税也无法覆盖所有开支。
Higher rates need not be a problem. The US economy has thrived at 5% and even higher rates before. But the transition might be difficult. America, like France, has taken on a bigger state that we can’t pay for with higher rates. The budget gap is about 6% of the economy, and annual interest costs have already leapt past the defense budget and will keep rising. There is little appetite to cut benefits or increase taxes to pay for them, other than taxing the wealthiest Americans, and even they can’t finance everything.
两党均未收到关于我们新利率现实的备忘录。两党继续承诺建设一个更大的政府,提供普惠且慷慨的医疗保健、儿童税收抵免,并扩大国家对经济的所有权。美国的救星在于更高的经济增长。美国指望人工智能引发生产力革命,从而提振增长并改善其赤字指标。但同时也存在监管人工智能、削减数据中心建设的意愿。这或许审慎,但会拖累增长。
Neither party got the memo on our new rate reality. Both continue to promise an even bigger state, universal and generous health care, child tax credits and more state ownership of the economy. The saving grace in America has been higher economic growth. The US is dependent on artificial intelligence creating a productivity revolution that will boost growth and improve its deficit metrics. But there is also a desire to regulate AI and cut back on data center building. This may be prudent, but it will slow growth.
在增长平平、利率走高的情况下,更大规模的政府是不可持续的。数学账根本算不清。但愿美国不会陷入骚乱和抢劫,但民众会愤怒,而且理应愤怒。
A bigger state with so-so growth and higher interest rates is unsustainable. The math just does not add up. Hopefully, the US doesn’t end up with riots and looting, but people will be angry and rightly so.
如果你被承诺了安全,你就会指望它、围绕它做计划。以为拥有安全资产却失去了它,或发现它原本并不那么安全,其代价可能远比从未拥有过它要大得多——任何金融危机都证明了这一点。投资者深信高评级抵押贷款支持证券必定兑付,且房价只会上涨。2008 年意识到两者均无保障,后果灾难性。如今退休人员信赖其社会保障福利不会被削减,家庭指望医疗保险补贴。
If you are promised security, you count on it and plan around it. Thinking you have a safe asset and losing it, or finding out it was not so safe after all, can be far more costly then never having it in the first place — as any financial crisis shows. Investors thought highly rated mortgage-backed securities would surely pay off and that their homes would only increase in value. The realization in 2008 that neither were guaranteed proved disastrous. Retirees today trust that their Social Security benefits won’t be cut, and families count on health insurance subsidies.
美国政客必须停止承诺建设更大、欧洲式的福利国家。“全民医保”不切实际,除非美国中产阶级愿接受更高税收,并由政府(而非保险公司)实施医疗资源配给。全民托儿和面向富裕阶层的税收抵免也站不住脚。更高的利率现实要求强化对低收入者和最弱势群体的福利。对其他人而言,这应意味着不再扩大福利,甚至直接削减福利。
American politicians must stop promising a bigger, European-style welfare state. Medicare for all is not realistic, unless the American middle class is willing to accept higher taxes and the government (instead of insurers) rationing care. Universal childcare and tax credits for the well off aren’t defensible either. The higher rate reality requires strengthening benefits for low earners and the most vulnerable. For everyone else, it should mean no further benefit expansions or outright cuts.
社会保障和医疗保险是退休人员收入保障的基石,即使是拥有大量资产的退休人员也是如此。这两个项目都在不断扩大,预计将继续增长。国会预算办公室预测,联邦在社会保障(该计划即将面临资不抵债)和医疗保险方面的支出将从2027年的国内生产总值的8.7%上升到2036年的10.1%,这主要是由人口老龄化、寿命延长以及福利随时间推移变得更加慷慨所驱动。美国人需要接受这样一个现实:改革必须涉及缩减而非扩大这些福利,并对所有人而非仅仅是富人增税。
Social Security and Medicare are the foundation of income safety for retirees, even those with substantial assets. Both programs have grown over time and are expected to keep growing. Federal spending on social security (which is nearing insolvency) and Medicare is projected by the Congressional Budget Office to rise from 8.7% of gross domestic product in 2027 to 10.1% percent in 2036, driven by an aging population, greater longevity and benefits that have become more generous over time. Americans need to accept that reform must involve shrinking rather than growing these benefits tax increases on everyone, not just the wealthy.
例如,美国可以改变人们退休时计算社会保障福利的公式,使其随通胀而非工资增长。同时也需要对高收入者实施更大幅度的削减,并提高退休年龄。
The US can, for example, change the formula used to calculate Social Security benefits when people retire, so they grow with inflation rather than wages. There will also need to be bigger cuts for higher earners and an increase in the retirement age.
这些变革理想情况下应适用于距离退休至少十年的人群,以便他们有时间调整储蓄计划。削减未来退休人员的福利不仅能在未来支出方面产生重大影响,还能向债券市场发出信号,表明支出终将放缓,且存在改革空间。这可能会降低当前的利率。
These changes will ideally apply to people who are at least a decade from retirement, so they have time to adjust their saving. Cutting benefits on future retirees can have a big impact, not only in terms of future spending, but also by sending a signal to bond markets that spending will one day slow, and there is scope for reform. That could lower rates today.
在我们这个高利率的世界里,唯一的出路是增长。但增长意味着更多风险和更小的福利国家。这是一颗苦药,但我们别无选择。我们曾以为极低利率会永远持续下去。现在借贷成本已回到历史上的“正常”水平,我们从历史中享受的假期已经结束。
The only way out in our higher rate world is growth. But growth means more risk and a smaller welfare state. It’s a bitter pill to swallow, but we have no choice. We thought rock-bottom rates would last forever. Now that borrowing costs are back to historically “normal” levels, our holiday from history is at an end.