周四,对冲标普500指数一年多来最大跌幅的成本飙升,交易员寻求保护以应对进一步的剧烈波动。
The cost to hedge against the biggest S&P 500 plunge in more than a year soared on Thursday as traders sought cover from further wild swings.
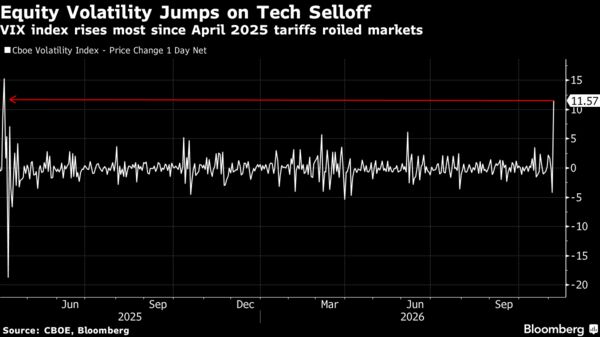
衡量美国基准指数预期波动率、作为市场压力关键指标的芝加哥期权交易所波动率指数(VIX)涨幅为2025年4月以来最大,当时标普500指数下跌4.4%,纳斯达克100指数下滑逾6%。VIX期权成本涨幅更大,增速为2018年“波动性大灾难”以来最快。
The Cboe Volatility Index, or VIX, measuring expected volatility in the US benchmark and a key gauge of market stress, rose the most since April 2025 as the S&P 500 dropped 4.4% and the Nasdaq 100 slid more than 6%. The cost of VIX options rose even more, jumping faster than at any time since the Volmageddon episode in 2018.
压力在短期合约中表现最为明显。反向结构,即首月VIX期权合约对次月合约的溢价,升至近一年来最高水平。在标普500指数期权(即VIX计算所依据的合约)中,买卖价差扩大,这是市场压力的另一信号。
The stress was most apparent in short-term contracts. The backwardation, or premium of first-month to second-month VIX futures contracts, reached the highest level in almost a year. In S&P 500 Index options, the contracts that feed into the VIX calculation, bid-ask spreads widened out, another sign of market stress.
“总体而言,对冲被买入和增加,虽然我们在某些点位看到了抄底买入,但绝大多数资金流向是变现/展期/增加保护,”Piper Sandler期权主管Daniel Kirsch表示。“临近收盘时首次感觉像是投降式抛售,固定行权价波动率飙升。”VIX期权总成交量是20日均值的三倍,达到313万份合约,为2024年8月因日元套息交易平仓导致市场暴跌、波动率飙升以来最高。但交易并非单边。VIX看跌看涨期权比率约为0.7,为7月以来最高,表明投资者并非整天只追逐看涨期权。
“Generally hedges bought and added, while we saw some dip buying in spots, the vast majority of flow was monetizing/rolling/adding protection,” said Daniel Kirsch, head of options at Piper Sandler. “Toward the close was the first time it felt like capitulation, with the spike higher in fixed strike volatility.”Overall volume of VIX options was triple the 20-day average and at 3.13 million contracts was the highest since volatility spiked in August 2024 when the market plunged on the unwinding of the yen carry trade. But the trading wasn’t all one way. The VIX put-call ratio was around 0.7, the highest since July, signaling that investors weren’t just chasing calls all day.
与此同时,基于纳斯达克100指数的芝加哥期权交易所NDX波动率指数飙升至2025年4月11日以来最高水平,当时正值该月关税驱动的动荡。
Meanwhile, the Cboe NDX Volatility Index, a version of the VIX based on the Nasdaq 100 Index, soared to its highest level since April 11, 2025, during that month’s tariff driven turmoil.
“市场买卖价差很宽,”Simplex Trading场内交易员Jason Coogan说。“市场每一次反弹都遭遇阻力。”
“Markets were wide,” said Jason Coogan, a floor trader a Simplex Trading. “Every rally in market was met with resistance.”