阿根廷全球债券正朝着一年多来最差单周表现迈进,全球避险情绪升温与投资者对明年总统大选日益加剧的焦虑形成共振。
Argentine global bonds are heading for their worst week in over a year as a global retreat from risk collides with growing investor anxiety over next year’s presidential election.
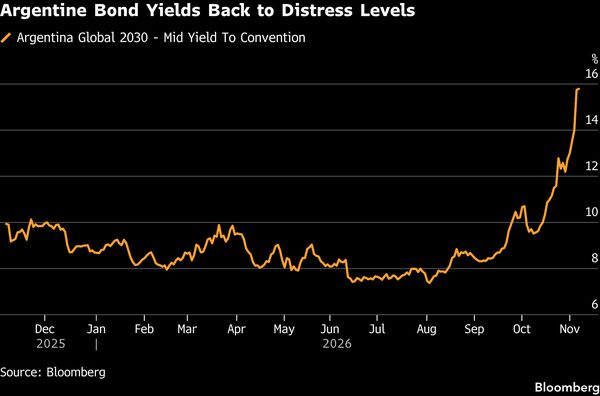
基准2035年期债券价格每美元跌超3美分,推动收益率周五升至13.77%,上周末收于12.67%。据摩根大通指数显示,投资者持有阿根廷债务而非美国债券所要求的额外收益率(注:即息差)在本周前四个交易日扩大近140个基点至928个基点——较7月低点翻倍有余。
The benchmark 2035 note lost more than three cents on the dollar, pushing the yield to 13.77% on Friday from 12.67% at the end of last week. The extra yield investors demand to hold Argentine debt over US bonds widened almost 140 basis points to 928 — more than double its July low — in the first four days of the week, according to a JPMorgan index.
本周暴跌加速了自7月以来形成的反转行情。当时阿根廷国家风险指标触及近八年低点、接近400个基点,投资者预期该国将重返国际资本市场。政府最终决定不发行外债,基准2035年期债券自此累计下跌近20美分。
This week’s rout accelerated a reversal that has been building since July, when Argentina’s country risk touched an eight-year low of almost 400 basis points and investors were anticipating a return to international capital markets. The government ultimately opted against issuing foreign debt, and the benchmark 2035 bond has lost almost 20 cents since then.
“本周价格表现糟糕,但这不是新闻——而是延续,”VanEck投资组合经理David Austerweil表示。“阿根廷风险面临完美风暴的条件已具备,距离阿根廷大选还有很长一段路。”阿根廷市场周五因银行假日休市,但债券在纽约交易中收窄部分跌幅。与美国债券的息差达到1000个基点,通常被视为进入困境债区域的门槛。
“Price action has been bad this week, but this is not news — it is a continuation,” said David Austerweil, a portfolio manager at VanEck. “There is a setup for a perfect storm for Argentine risk, and we still have a long way to go before the Argentine election.”Argentine markets were closed Friday for a bank holiday, though the bonds pared some losses in New York trading. A spread of 1,000 basis points to US bonds is commonly seen as the threshold for distressed territory.
尽管最新抛售伴随更广泛的全球抛售潮,投资者表示阿根廷特有担忧正日益放大跌幅。尽管该国继续保持财政盈余并受益于出口繁荣,市场已开始为2027年总统大选的风险定价,时间远早于许多投资者预期。
While the latest rout coincided with a broader global selloff, investors say Argentina-specific concerns have increasingly amplified the move. While the country continues to run a fiscal surplus and benefit from booming exports, markets have begun pricing in risks from the 2027 presidential election far earlier than many investors expected.
“市场已开始预判选举进程,”BlackRock投资组合经理Pablo Goldberg表示。
“The market has started to anticipate the electoral process,” said Pablo Goldberg, a portfolio manager at BlackRock.
根据经纪公司Portfolio Personal Inversiones策略主管Pedro Siaba Serrate开发的模型,市场隐含的米莱连任概率目前约为45%,低于7月左右的约90%。这意味着连任不再是债券价格所隐含的基本情形。
The market-implied probability of Milei’s reelection is currently about 45%, down from roughly 90% around July, according to a model developed by Pedro Siaba Serrate, head of strategy at broker Portfolio Personal Inversiones. That means reelection is no longer the base case implied by bond prices.
其他地方的政治发展加剧了这种焦虑。巴西总统卢拉连任以及美国共和党在中期选举中失利,促使一些投资者重新评估曾支撑市场对米莱情绪的政治背景。
Political developments elsewhere have added to that anxiety. The reelection of Luiz Inácio Lula da Silva in Brazil and Republican losses in the US midterms have prompted some investors to reassess the political backdrop that had supported sentiment toward Milei.
Allaria策略主管Federico Cuba表示:“市场似乎在为政府输掉大选而非赢得大选定价更高的概率,这看起来并不明显,而且发生得相当早。巴西大选加速了这种动态,不仅因为结果令人意外,还因为阿根廷现在已成为该地区下一个重大选举。”美国中期选举结果也引发了关于阿根廷明年能否指望获得华盛顿同等程度支持的疑问。2025年金融动荡期间,一条200亿美元的美国互换额度发挥了关键作用,但一些投资者质疑,在总统大选前夕,这种支持是否会同样随时可得。
“The market appears to be pricing in a greater chance of the government losing than winning, which doesn’t seem obvious and is also happening quite early,” said Federico Cuba, head of strategy at Allaria. “The Brazilian election accelerated that dynamic, not only because of the surprise, but because Argentina has now become the region’s next major election.”The US midterm result has also raised questions about whether Argentina could count on the same degree of support from Washington next year. A $20 billion US swap line proved critical during financial turmoil in 2025, but some investors question whether that backing would be as readily available ahead of a presidential election.
加剧担忧的是,本周异常大规模的本地政府债券购买引发了当局干预以支撑市场的猜测,这引发了关于潜在储备损失的疑问,因为阿根廷明年面临约250亿美元的硬通货偿付。
Adding to the concerns, unusually large purchases of local government bonds this week fueled speculation that authorities were intervening to support the market, which raised questions about potential reserve losses as Argentina faces about $25 billion in hard-currency payments next year.
Austerweil表示:“政府愿意花费如此巨额资金来支撑本地市场并维持比索稳定,这引发了对储备流失的担忧。我们预期储备会成为一个问题,但这种情况发生得如此之快令人担忧。”
“The fact that the government is willing to spend money in such size to support the local market and keep the peso stable brings concerns about reserve drain,” Austerweil said. “We expected reserves to become an issue, but the fact that this is happening so fast is concerning.”