人工智能机器人的突发性进步,正在关于谁将掌控消费者支付未来的争夺战中开辟新战场。
Sudden advancements by artificial intelligence bots are opening new fronts in the battles over who will control the future of consumer payments.
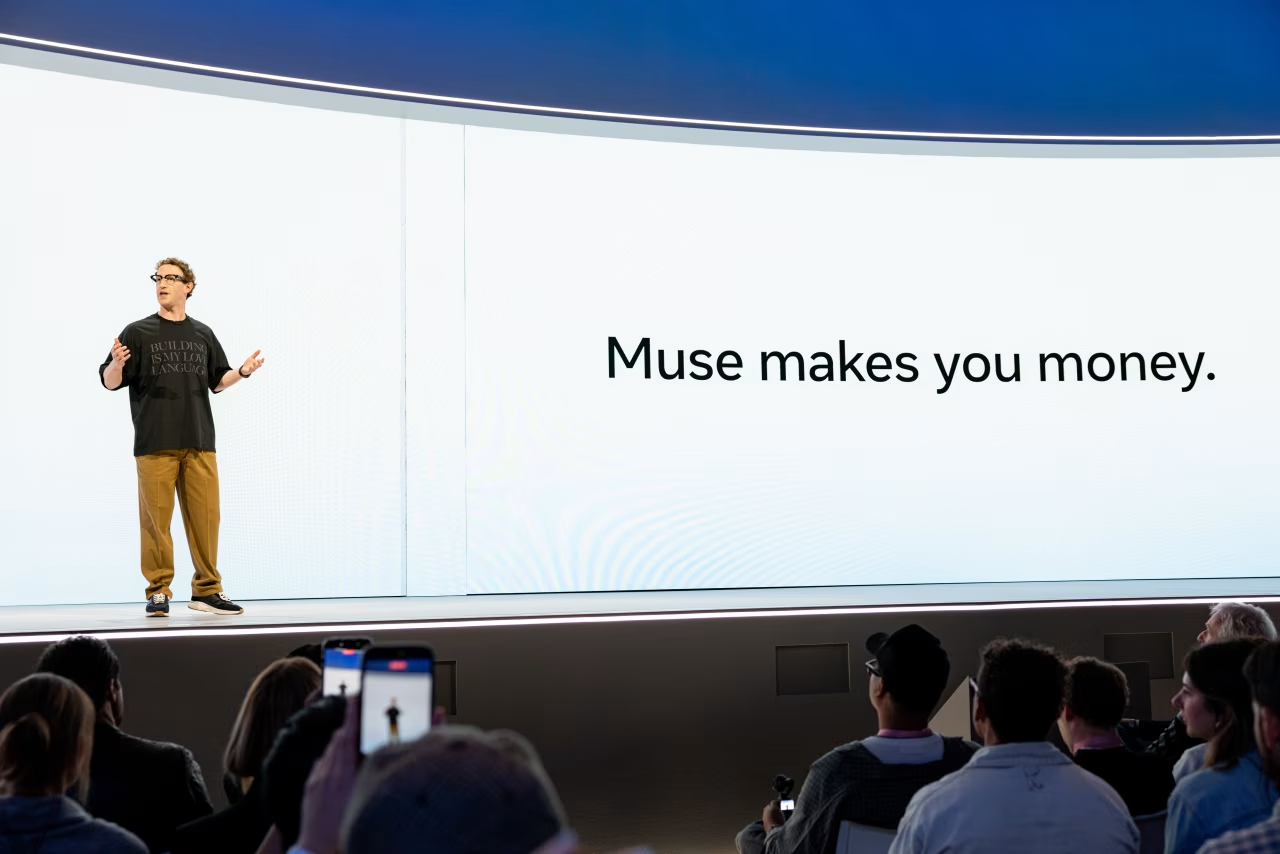
Meta 的 Muse、Instinct 等个人人工智能助手在过去几周内已获授权代表持卡人进行购买,标志着向一个可能的未来迈出了新步伐,届时消费者无需自行发起购买或在结账时按下“购买”按钮。这引发了人们对人工智能机器人能够在支付领域创造新世界秩序的热议与兴奋。
Meta’s Muse, Instinct and other personal AI assistants have been empowered in recent weeks to make purchases on behalf of cardholders, marking new steps toward a potential future where consumers no longer need to initiate a purchase or press “buy” at checkout. That is generating buzz and excitement about AI bots’ ability to create a new world order in payments.
但在银行、其他支付公司和商家内部,人们对其影响以及机器人是否会导致欺诈和退货案例增加、并开辟新的法律风险,充满担忧。早期的阵营已经开始形成。
But inside banks and other payments companies and merchants, worries abound about the implications and whether bots will lead to elevated cases of fraud and returns, and open new legal risks. Early camps are already being formed.
知情人士表示,支付巨头 Stripe 已拥抱代理购买,并试图在人工智能未来中占据核心地位。当消费者启用代理时,Bank of America、Capital One 和 Citigroup 等银行的卡片正被代理使用。
Payments giant Stripe has embraced agentic purchasing and sought to stake out a central position in the AI future, according to people familiar with the matter. Cards from banks such as Bank of America, Capital One and Citigroup are being used by agents when consumers enable them.
知情人士表示,按购买量计算美国最大的信用卡发行商 JPMorgan Chase 是较为怀疑的银行之一。该银行一直在阻止消费者将卡片信息交给机器人时的代理行为,并且对其他竞争银行正在尝试的解决方案反应迟缓,知情人士表示。
JPMorgan Chase, the largest U.S. credit-card issuer by purchase volume, is among the more skeptical banks, people familiar with the matter said. The bank has been blocking agents when consumers give the bots their card information and it has been slow to allow other solutions rival banks are trying, the people said.
支付高管表示,目前还处于早期阶段,人工智能机器人进行的消费者卡片交易数量不多,但很可能会大幅增长。银行和其他支付公司面临的根本紧张局势在于:如果选择了错误的技术或行动过于缓慢,就有被甩在后面的风险。
It is early days, and the number of consumer card transactions made by AI bots is small, but it is likely to grow materially, according to payments executives. The underlying tension for banks and other payments companies is the risk of being left behind if they choose the wrong technology or are too slow to act.
“现在正是抢地盘的时候,”Rain 首席执行官法鲁克·马利克说,Rain 是一家代理支付和稳定币基础设施公司。
“It’s a land grab right now,” said Farooq Malik, CEO of Rain, an agentic payments and stablecoin infrastructure company.
当今支付系统的运行依赖于错综复杂的规则、反欺诈保护、联邦法律,以及并非为机器人设计的网络和银行费用。这一生态系统长期处于商家、制定费用和规则的网络组织、以及向消费者提供信贷的发卡机构三方持续博弈的状态之中。
The systems that power payments today are built on byzantine rules, fraud protections, federal laws and network and bank fees that aren’t intended for robots. This ecosystem has long been in a state of constant tension between merchants, networks that set fees and rules, and card issuers that extend credit to consumers.
哪怕仅移动一环、将某项费用调整一美分,影响都能迅速蔓延,导致数十亿美元的得失。人工智能向金融领域的渗透正引发多重担忧。
Move one piece or change one fee even by a cent and the impact can quickly ripple into billions of dollars won and lost. The advancement of AI into finance is creating several concerns.
包括摩根大通、花旗、美国银行和Capital One(资本一号)在内的大型银行,近期采取措施限制AI代理访问消费者存款账户,理由是保障消费者个人信息安全。经济学家和分析师担心,AI代理将轻易发现其他地方收益更高的存款账户,并将存款持有者的资金转移过去。
Large banks, including JPMorgan, Citigroup, Bank of America and Capital One, recently moved to restrict AI agents from accessing consumer deposit accounts over the safety of consumers’ personal information. Economists and analysts have raised fears that AI agents will easily find higher-yielding deposit accounts elsewhere and transfer their deposit holders’ money there.
与此同时,据知情人士透露,财政部正就AI与支付相关的框架向银行提问。
The Treasury Department, meanwhile, is asking banks questions related to frameworks around AI and payments, according to people familiar with the matter.
在支付领域,银行担心消费者将信用卡直接交由AI机器人使用。例如,摩根大通已采取行动限制代理使用这些消费者的信用卡购物。
In payments, banks are concerned about consumers placing their credit cards directly into the hands of AI bots. JPMorgan, for instance, has moved to restrict agents from shopping with those consumers’ cards.
但其他大型银行的高管表示,他们视识别AI机器人并将其切断为一项难以实施、甚至不可能完成的挑战。
But executives at other large banks say they view it as a difficult-to-impossible challenge to spot AI bots and shut them off.
卡片行业技术公司Cardless的总裁Michael Spelfogel(迈克尔·斯佩尔福格尔)表示,其公司正与网络合作伙伴合作,以实现代理式消费。
Michael Spelfogel, president of Cardless, a technology company in the card industry, said his company is working with network partners to enable agentic spending.
斯佩尔福格尔说:“人们已经希望AI代理替他们购物,而安全实现这一目标的技术也已经具备。银行可以把这件事拖慢一两年,但无法阻止人们用代理花自己的钱。”一些支付行业高管表示,与消费者亲自购物相比,他们已经从代理式购物中看到更高的回报,但欺诈案件也有所增加,例如代理从虚假网店购买商品,而这些网店从不发货。此外,人们还担心AI会加剧积分套利行为,这可能使高端信用卡对银行来说成本更高。
“People already want AI agents to shop for them, and the technology to do it safely is built,” Spelfogel said. “Banks can slow this down for a year or two, but they can’t stop people from using agents to spend their own money.”Some payment executives say they are already seeing higher returns from agentic shopping compared with when consumers make their own purchases, as well as elevated fraud cases, such as from agents purchasing items from fake online stores that never deliver the products. And there are concerns about AI supercharging points gaming, which could make premium cards more expensive for banks.
高管们也对责任归属保持警惕。信用卡为用户提供欺诈保护,但银行并不以同样方式看待一笔经授权的扣款。一些高管表示,他们所在的银行计划告知消费者,消费者授权代理用自己的卡购物,将被视为等同于持卡人把自己的卡交给亲友使用。
Executives are also wary of liability. Credit cards come with fraud protection for users, but banks don’t view an authorized charge the same way. Some executives say their banks plan to tell consumers they are treating their authorization of an agent to shop with their card as equivalent to cardholders giving their cards to relatives or friends.
Stripe正试图发挥关键作用,利用其拥有超过3亿用户的Link钱包,让代理式购物者能够完成购买。
Stripe is seeking to play a key role by leveraging its Link wallet, which has more than 300 million users, to enable agentic shoppers to execute purchases.
Stripe的一位发言人说:“代理式商务尚处早期,但前景可期。”并补充说,公司正与合作伙伴共同构建这项技术。一些银行认为,相比让持卡人把原始卡号交给代理,Link是更可取的选择。
“Agentic commerce is nascent but promising,” a Stripe spokesman said, adding it is working with partners to build the technology. Some banks see Link as a preferable alternative to cardholders giving agents their raw card numbers.
Link使用的是代理令牌,其目的是通过隐藏卡号让交易更安全,类似于在Apple Pay和其他钱包中隐藏消费者卡凭证的令牌。这些代理令牌由Visa和Mastercard提供,还附带其他数据,例如消费者希望代理购买哪些商品的信息、消费者对购买金额设定的上限,以及该AI机器人是否可信。
Link is using agentic tokens, which are meant to make transactions more secure by hiding the card’s number, similar to the tokens that hide consumers’ card credentials on Apple Pay and other wallets. The agentic tokens, which are provided by Visa and Mastercard, are also packaged with other data, such as information on what consumers want purchased on their behalf, the limits they place on purchase amounts, and whether the AI bot is trusted.
据知情人士透露,这对摩根大通来说还不够。摩根大通一直不认同Stripe使用的代理令牌技术,并且迟迟没有采用这项技术。
That hasn’t been enough for JPMorgan, which has been at odds with the agentic token technology used by Stripe and has been slow to implement it, according to people familiar with the matter.
Stripe为AI机器人设有单独的机制,可用于大通卡及其他发卡机构的卡片。在这些情况下,Stripe的钱包一直使用与购买金额等额的一次性虚拟卡。交易完成后,Stripe立即将购买金额计入消费者的实际卡片,从而有效清偿这张虚拟卡。
Stripe has a separate mechanism for AI bots, which can be used for Chase cards and other issuers. In those cases, Stripe’s wallet has been using one-time virtual cards that are equal to the purchase amount. Just after the transaction goes through, Stripe charges the purchase amount to the consumer’s actual card, which effectively pays off the virtual card.
这一安排本身也带来了一系列问题,尤其是对商家而言。据知情人士透露,商家正向Visa和万事达卡投诉,称虚拟卡平均产生的费用高于消费者实际卡片本应收取的费用。这是因为虚拟卡被归类为商业卡,而非消费者卡。
This arrangement has opened its own set of issues, especially for merchants. Merchants are complaining to Visa and Mastercard that they are incurring higher fees on average from the virtual card than they would be charged by the consumer’s actual card, according to people familiar with the matter. That is because the virtual card is classified as a commercial card rather than a consumer card.
商家对代理式商务还有其他担忧,包括对客户购物方式的可见度降低,这使得收集数据以及未来向客户提供购买推荐变得更加困难。一些商家高管表示,临时卡还给退货处理带来了挑战。
Merchants already have other concerns about agentic commerce, including less visibility into how their customers are shopping, which makes it harder to collect data and make future purchase recommendations to them. The temporary cards have also created challenges for processing returns, some merchant executives said.
联合航空周三表示,将阻止个人AI助手访问其系统进行订票。亚马逊在9月阻止了Meta的Muse进行购物。不过,沃尔玛表示,将允许消费者授权AI代理,并区分消费者本人和代理发起的购买。
United Airlines said Wednesday that it will prevent personal AI assistants from accessing its systems to book tickets. Amazon in September blocked Meta’s Muse from making purchases. Walmart, however, said it would allow consumers to authorize AI agents and distinguish between the purchases they and the agents initiated.
货币监理署本月向其银行审查人员提供了一个新框架,用于评估银行对AI的使用,包括支付、客户服务和欺诈检测。该文件将“自主支付代理”列为最高风险等级。
The Office of the Comptroller of the Currency this month gave its own bank examiners a new framework for evaluating banks’ use of AI, including payments, customer service and fraud detection. The document lists “autonomous payment agent[s]” as being at the highest risk tier.