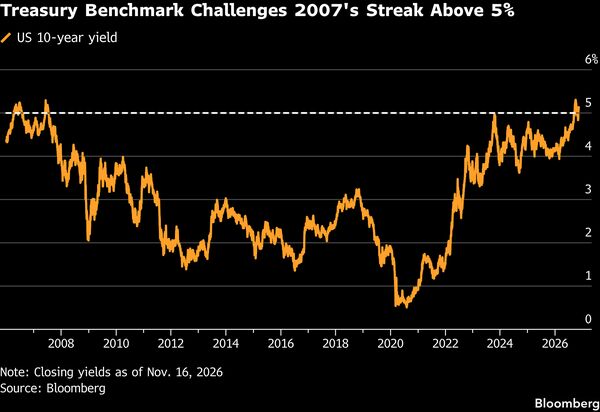
美国10年期国债收益率正逼近近二十年来最长的一段高于5%的时期,原因是通胀顽固地居高不下,投资者预计美联储将进一步提高利率。
The US’s 10-year Treasury yield is nearing its longest run above 5% in almost two decades as investors position for the Federal Reserve to hike interest rates more amid stubbornly elevated inflation.
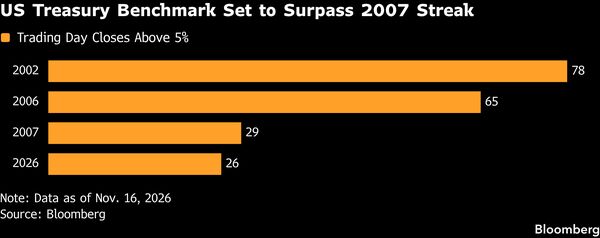
这一全球最大经济体借贷成本的基准今年有望第27天保持在5%以上,使2026年距离2007年创下的29次收于5%以上的纪录近在咫尺。在10月美国零售额增长放缓后,该收益率上升约1个基点,至5.14%。
The benchmark for borrowing costs in the world’s largest economy is on pace to hold above 5% for the 27th day this year, putting 2026 within striking distance of the 29 such closes recorded in 2007. It was about one basis point higher at 5.14% after US retail sales growth moderated in October.
收益率面临上行压力之前,高于预期的10月通胀迫使美联储政策制定者开始考虑以比此前预期更激进的方式收紧货币政策。
Upward pressure on yields comes after hotter-than-expected October inflation forced Fed policymakers to begin considering a more aggressively tightening of monetary policy than previously expected.
交易员目前完全消化了美联储在12月9日会议上加息25个基点的预期,并预计到2027年9月将收紧逾80个基点,而上周之前的预期约为50个基点。
Traders are now fully pricing a quarter-point rate increase at the central bank’s Dec. 9 meeting and see more than 80 basis points of tightening by September 2027, compared with roughly 50 basis points before last week.
摩根大通资产管理公司投资组合经理普里娅·米斯拉表示,收益率回升至5%以上反映出“美联储不确定性带来的风险溢价”。
Yields back over 5% reflect “risk premium due to uncertainty about the Fed,” said Priya Misra, portfolio manager at JPMorgan Asset Management.
她说,经济保持韧性,加上债券大量发行——既来自美国政府,也来自寻求投资人工智能的公司——是收益率保持在5%以上的其他原因。
The resilient economy and lots of bond sales, from the US government as well as companies looking to invest in AI are other reasons for yields staying above 5%, she said.
10年期收益率是美国经济的基准,因为它有助于确定住房抵押贷款、信用卡和商业贷款的成本。2007年,10年期收益率在6月升至5%以上,并在美联储将利率维持在2006年7月首次达到的5.25%之际见顶于5.32%。这为高利率拖累房地产行业埋下伏笔,促使美联储在9月降息。
The 10-year is a benchmark for the US economy as it helps set the cost of home mortgages, credit cards and business loans. Back in 2007, the 10-year yield climbed above 5% in June and peaked at 5.32% as the Fed kept rates at 5.25% they first reached in July 2006. That set the stage for elevated rates to weigh on the housing sector, which prompted the central bank to cut rates in September.
在BMO资本市场美国利率策略主管伊恩·林根看来,当前的高收益率已经令人担忧。
For Ian Lyngen, head of US rate strategy at BMO Capital Markets, the current elevated yields are already a cause for concern.
“对房地产市场的影响是实际上冻结了市场活动,”他说。这是“一个可以预见的结果,鉴于30年期抵押贷款利率自9月中旬以来一直保持在7%以上。”今年美国国债收益率的走势虽然并非直线,但总体呈上行路径,10年期收益率从2月底唐纳德·特朗普总统对伊朗发动战争、扰乱中东石油和天然气供应时的不到4%一路上升。
“The impact on the real estate market has been to effectively freeze activity,” he said. That’s “a foreseeable outcome given the fact that 30-year mortgages have remained above 7% since mid-September.”The trajectory of Treasury yields this year, while not in a straight line, has generally followed an upward path, with the 10-year’s rising from under 4% when President Donald Trump launched his war on Iran in late February, disrupting the supply of Middle Eastern oil and gas.
基准收益率震荡走高,先是在9月中旬突破5%,随后在10月7日盘中达到5.36%的峰值。这标志着常规交易时段自2002年以来的最高水平,之后科技股和人工智能股遭遇抛售,引发避险买盘,推动10年期收益率在本月早些时候回落至4.8%附近。
The benchmark yield swung higher, first topping 5% in mid-September before peaking intraday at 5.36% on Oct. 7. That marked the highest in regular trading since 2002, before an equity selloff in technology and AI shares fueled a haven bid, sending the 10-year’s down toward 4.8% earlier this month.
收益率反弹回升至5%以上,原因是通胀超出预期,引发美联储官员的担忧,并激起关于12月是否应考虑加息50个基点的争论。
The bounce back above 5% has been driven by inflation topping expectations, igniting concern from Fed officials and a debate about whether a 50-basis point increase should be considered in December.
其他因素也在拖累美国国债。人工智能热潮使超大规模云服务商的债务大量涌入市场,同时也向经济注入了刺激。对联邦政府膨胀的预算赤字的持续担忧是另一个催化剂,因为投资者要求获得更多补偿,即期限溢价,才愿意持有10年期美国国债。
Other forces are also weighing on Treasuries. The artificial intelligence boom has flooded markets with debt from hyperscalers, while also pouring stimulus into the economy. Lingering concerns about the federal government’s swollen budget deficit has been another catalyst as investors demand more compensation, or term premium, to own the 10-year Treasury.
随着华尔街银行将目光投向2027年,摩根士丹利的策略师表示,10年期美国国债收益率明年年底将在5%。高盛集团的同行预计将降至4.6%,而接受美国银行调查的全球基金经理预计为4.9%。
As Wall Street banks turn their eyes to 2027, strategists at Morgan Stanley are saying 10-year Treasury yields will end next year at 5%. Counterparts at Goldman Sachs Group Inc. see a decline to 4.6% while global fund managers surveyed by Bank of America expect 4.9%.
一些债券管理人并未反思收益率向上调整的痛苦过程,而是宣扬高收益率正带来数十年来最佳的收益机会。今年美国固定收益共同基金和交易所交易基金的资金流入创下纪录,表明大量散户和机构投资者并未因财政和通胀担忧而却步。
Rather than reflect on what has been a painful adjustment higher in yields, some bond managers are touting the high level of yields generating the best income opportunity in decades. This year has seen record inflows into US fixed income mutual and exchange-traded funds, indicating that plenty of retail and institutional investors looking beyond fiscal and inflation jitters.
此外,自2023年以来持续的股市上涨使许多投资组合的股票配置比重增加,为向债券进行有意义的再平衡奠定了基础,他们表示。
In addition, a sustained equity market rally since 2023 leaves many portfolios more heavily weighted in stocks, setting the stage for a meaningful rebalancing into bonds, they say.
据华盛顿堡投资顾问公司高级投资组合经理丹·卡特称,由于收益率所处的水平,固定收益产品存在需求。
There’s demand for fixed income because of where yields trade, according to Dan Carter, senior portfolio manager at Fort Washington Investment Advisors.
他说:“固定收益的风险回报比现在看起来比很长一段时间以来都要好得多。债券将重新发挥其在投资组合中传统扮演的防御性角色。”
“The risk-reward in fixed income is looking a lot better now than it has quite some time,” he said. “Bonds will reassert their defensive role that they traditionally have played in portfolios.”