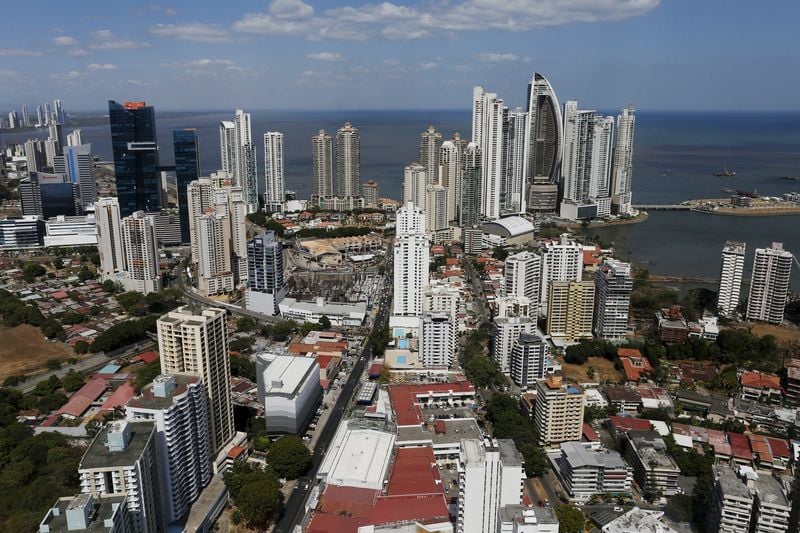
Investing.com -- 穆迪评级已将巴拿马政府的信用展望从负面调整为稳定,表明随着经济扩张加速,持续财政恶化的风险有所降低。该机构同时确认巴拿马长期外币发行人评级和高级无抵押评级为Baa3,使该国主权评级保持在投资级区间。
Investing.com -- Moody's Ratings has revised its credit outlook on the Government of Panama to stable from negative, signaling reduced risk of sustained fiscal deterioration as economic expansion accelerates. The agency concurrently affirmed Panama's Baa3 long-term foreign-currency issuer and senior unsecured ratings, keeping the sovereign within investment-grade territory.
经济势头强于预期,加上持续的预算纪律,已使巴拿马政府债务负担接近企稳。继2025年实际GDP反弹4.4%之后,穆迪预测2026年和2027年将实现5%的年增长,这有助于将非金融公共部门赤字从2025年占GDP的3.7%收窄至2027年的3.0%,并使债务稳定在GDP的66%左右。
Stronger-than-expected economic momentum and sustained budget discipline have brought Panama's government debt burden close to stabilization. Following a 4.4% real GDP rebound in 2025, Moody's forecasts 5% annual growth in 2026 and 2027, helping narrow the non-financial public sector deficit from 3.7% of GDP in 2025 to 3.0% by 2027 and stabilizing debt near 66% of GDP.
关键在于,财政调整的质量有所改善,从可逆的资本支出削减转向经常性支出约束、更强的税收管理,以及2025年一项缓解社会保障缺口的养老金改革。巴拿马运河的运营正常化进一步提升了该国的主权信用状况,2026财年收入增长16.6%至66亿美元,同时里奥印第奥水库等水资源韧性项目实现了自筹资金。
Crucially, the quality of the fiscal adjustment has improved, shifting away from reversible capital spending cuts toward current expenditure restraint, stronger tax administration, and a 2025 pension reform that alleviated social security shortfalls. Operational normalization at the Panama Canal has further bolstered the sovereign's profile, with fiscal 2026 revenue climbing 16.6% to $6.6 billion alongside self-funded water resilience projects like the Río Indio reservoir.
围绕已关闭的Cobre Panama铜矿的事态发展也指向更有利的风险平衡,官员们正逐步接近就潜在重启进行正式谈判。尽管穆迪的基线情景假设矿山不会恢复运营,但通过谈判达成和解可能消除国际仲裁索赔,并为出口和国家收入带来可观的上行空间。
Developments surrounding the shuttered Cobre Panama mine also point toward a more favorable risk balance as officials move closer to formal negotiations over a potential reopening. While Moody's baseline scenario assumes no mining resumption, a negotiated settlement could extinguish international arbitration claims and provide meaningful upside to exports and state revenues.
尽管有这些有利因素,巴拿马的Baa3评级仍受狭窄的收入基础以及相对于投资级同行的高债务偿还成本所制约。利息支出预计将从2025年政府收入的17.4%小幅下降至2027年的16.5%,未来各届政府的制度持续性仍是投资者关注潜在评级上调动力的关键变量。
Despite these tailwinds, Panama's Baa3 rating remains constrained by a narrow revenue base and elevated debt-servicing costs relative to investment-grade peers. Interest payments are projected to edge down only modestly from 17.4% of government revenue in 2025 to 16.5% by 2027, leaving institutional durability across future administrations as a key variable for investors watching potential upward rating momentum.