文/格雷格·里奇 德意志银行的乔治·萨拉维洛斯表示,今年市场对固定收益资产的情绪转向极度悲观已走得太远,市场低估了人工智能泡沫破裂引发抢购债券潮的风险。
The swing to deeply-negative sentiment on fixed-income assets this year has gone too far, with the market underpricing the risk of an artificial-intelligence blowup that triggers a rush into bonds, according to Deutsche Bank AG’s George Saravelos.
萨拉维洛斯是该行全球外汇研究主管,他在周五的一份报告中表示,美国客户会议显示出担忧,认为人工智能是“推高收益率的主要驱动力,且美国财政部已失去对长端债券的控制”。他补充称,这些因素助长了投资者对即将暂停发行20年期国债的猜测,而在法国债券经历动荡抛售后,客户对法国债务“压倒性地看跌”。
Client meetings in the US displayed concerns that AI is a “big driver of higher yields and the US Treasury has lost control of the long-end,” Saravelos, global head of FX research, said in a note Friday. These factors have fanned investor speculation of a coming suspension in 20-year Treasury issuance, while clients were “overwhelmingly bearish” on French debt after a turbulent selloff there, he added.
这与去年的市场叙事大相径庭,当时人工智能被视为潜在的去通胀因素,而美国财政部阻止收益率上升的举措被认为是可信的。萨拉维洛斯表示:“叙事的钟摆向另一方向摆动得有点过头了。”
That’s a far cry from the market narrative last year, when AI was seen as potentially disinflationary and the US Treasury’s moves to stop yields from rising were viewed as credible. “The narrative pendulum has swung a little too much” in the other direction, Saravelos said.
他表示:“明年市场最大的系统性风险不是法国,而是人工智能生态系统‘出问题’:安全事件、IPO失败或收入令人失望。集中度风险巨大,而这种利空美元(且极度利好债券)的事件风险,目前是市场定价最不足的。”
“The biggest systemic risk in the market next year is not France but ‘something going wrong’ in the AI ecosystem: a safety event, a failed IPO, or disappointing revenues,” he said. “Concentration risk is immense, and it is this dollar negative (and very bond positive) event risk that is most under-priced in markets at the moment.”
受伊朗战争导致能源价格飙升加剧通胀担忧、且美国经济强劲等因素影响,美国国债收益率已升至数十年高位。后者因人工智能基础设施支出而获得提振,同时也增加了投资者需要融资的债务规模。
US Treasury yields have risen to multi-decade highs as the surge in energy prices from the Iran war fanned inflation concerns, against a backdrop of a robust US economy. The latter is being boosted by spending on AI infrastructure, at the same time adding to the amount of debt investors are being asked to finance.
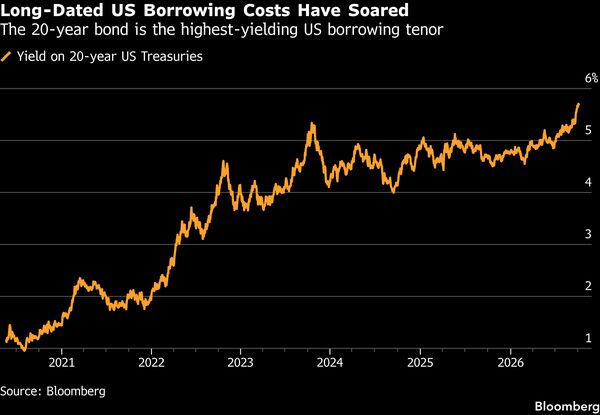
债券市场的动荡加剧了市场猜测,即美国财政部可能会进一步调整国家的借款结构,减少长期债券的发行,转而增加短期债务。减少或取消20年期国债的发行——该品种的收益率要求高于相近期限的债券——已成为一种激进的选项,尽管包括法国巴黎银行策略师在内的一些人士对其有效性持怀疑态度。
The battering of the bond market has increased speculation that the Treasury may further tilt the nation’s borrowing away from long-maturity bonds, and toward short-dated debt. Reducing or eliminating issuance of the 20-year bond, which demands a higher yield than nearby tenors, has emerged as a radical option, though some, including strategists at BNP Paribas SA, are skeptical that would be effective.
对于萨拉韦洛斯(Saravelos)而言,人工智能风险重新定价的风险将利好债券。与此同时,在谈到法国债务时,他告诉客户,投资者的一些担忧似乎被夸大了。
For Saravelos, the risk of a repricing of AI risk would benefit bonds. On French debt, meanwhile, he told clients some of investors’ concerns appear overblown.
“我们解释了为什么不同意将当前情况与2010年至2015年进行类比,但不可否认的是,鉴于上周出现的巨大错位,市场恢复信心仍需时日,”他表示。“这对欧元构成了我们此前未曾预料到会在今年出现的额外压力。”
“We explained why we disagreed with parallels of 2010-2015, but nonetheless it is clear it will take time for the market to regain confidence given the huge dislocations last week,” he said. “This is a fresh weight on the euro we were not expecting to materialize this year.”