国债正在出现重新夺回其传统避险角色的初步迹象 — — 这可能会让那些今年大举押注债券行情进一步恶化的投资者措手不及。
Treasuries are showing tentative signs of reclaiming their traditional role as a haven — threatening to wrong-foot investors who are heavily positioned for this year’s bond slump to deepen.
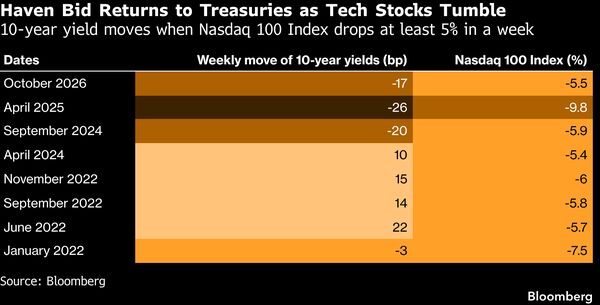
随着市场对领先人工智能公司前景及其对更广泛经济潜在影响的担忧加剧,上周10年期国债收益率下降了约17个基点,而纳斯达克100指数下跌了5.5%。
As concerns mount across markets over the outlook for leading artificial-intelligence firms and the potential impact on the broader economy, 10-year yields fell about 17 basis points last week while the Nasdaq 100 Index tumbled 5.5%.
上次收益率和科技基准在同一周出现如此幅度的下跌,是在2025年4月的关税动荡期间。
The previous time yields and the tech benchmark dropped that much in the same week was during the April 2025 tariff turmoil.
在数月来国债在股票低迷时期基本未能提供其传统保护作用之后,这次债券反弹尤为显著。通胀居高不下、经济韧性强劲以及政府和企业借贷激增 — — 包括为人工智能热潮融资 — — 共同推动了过去七个月美国10年期国债收益率上升,至二十多年来的最高水平。
The bond rally was notable after months when Treasuries largely failed to provide their customary protection during periods when stocks were struggling. Hot inflation, a resilient economy and a flood of government and corporate borrowing — including to finance the AI boom — combined to push 10-year US yields up the past seven months, to their highest levels in more than two decades.
股票的最新动荡部分扭转了这一趋势,因为投资者持有异常激进的做空国债头寸,这增加了空头回补的可能性,并在通胀仍然坚挺的情况下加剧了债券市场的双向风险。
The latest wobble in stocks upset that trend in part because investors were sitting on unusually aggressive bearish Treasuries bets, raising the prospect of short-covering and heightening the two-way risk in the bond market even as inflation stays solid.
“正如马克·吐温所说,关于美国国债死亡的传言被大大夸大了,”马尔伯勒投资管理公司投资组合经理詹姆斯·阿塞伊(James Athey)表示。
“To paraphrase Mark Twain, rumors of the death of US Treasuries are greatly exaggerated,” said James Athey, a portfolio manager at Marlborough Investment Management.
当然,要断言这一推动股市估值增加数万亿美元的人工智能热潮即将结束仍然很困难。之前的波动曾被证明是短暂的。
Of course, it’s tough to conclude that the AI boom, which has added trillions of dollars to stock-market valuations, is coming to an end. Previous bouts of volatility have proved short-lived.
但人们对人工智能公司Anthropic PBC收入增长放缓迹象以及人工智能云计算供应商CoreWeave Inc.债券价格下跌的担忧,正在引发人们对这一曾助长债券暴跌的交易是否出现裂痕的质疑。大规模人工智能投资提振了经济,而对计算机芯片的需求激增又加剧了通胀压力。
But concerns over signs of slowing revenue growth at Anthropic PBC and the sinking debt prices of AI cloud-computing provider CoreWeave Inc. are raising questions about whether cracks are emerging in a trade that helped drive the bond rout. Massive AI investment has boosted the economy, while surging demand for computer chips added to inflationary pressures.
“由人工智能主导的衰退将更接近传统的负面需求冲击”,瑞士银行 Julius Baer 的固定收益策略师阿方索·博尔赫斯(Afonso Borges)在一份报告中写道,“这也将成为通缩的催化剂。”他表示,在这种情形下,“中期国债应再次成为有效的投资组合对冲工具。”在此背景下,该公司建议在中期区间采取超配久期头寸。博尔赫斯指出,2000 年至 2020 年间,10 年期国债在股市回撤期间始终实现正回报。
“An AI-led downturn would be a lot closer to a more traditional negative demand shock” and a catalyst for disinflation, Afonso Borges, a fixed-income strategist at Julius Baer, wrote in a report. In that kind of episode, he said, “intermediate Treasuries should again serve as an effective portfolio hedge.”Against that backdrop, the firm recommends an overweight duration stance in the intermediate area. Borges pointed out that 10-year Treasuries consistently delivered positive returns during equity drawdowns between 2000 and 2020.
为融资人工智能基础设施而进行的企业发债潮加剧了资本竞争,这成为国债的另一大利空。如果对人工智能投资的预期减弱,这些力量可能开始逆向作用。以巨型科技公司为首的投资级公司今年已发行约 1.7 万亿美元债券,较去年同期增长约 29%。
The deluge of corporate issuance to finance AI infrastructure has increased competition for capital, another headwind for Treasuries. If expectations for AI investment fade, those forces could begin to work in reverse. Investment-grade companies – led by megacap tech firms — have sold about $1.7 trillion of bonds this year, up some 29% from this time last year.
“如果投资者看到其与人工智能挂钩的债券贬值,他们购买新债券的兴趣就会降低,”Natixis 北美公司美国利率策略主管约翰·布里格斯(John Briggs)表示。“因此,这在短期内削弱了人工智能发债的弹药供给,结果是随着对‘挤出效应’的担忧减少,长端国债的买盘增加。”如果人工智能交易的疲弱态势延续,交易员的持仓也可能进一步放大债券的强势。国债的上涨得到了被称为商品交易顾问的投资者推动,他们在上周以极端空头水平进入后,正在退出看跌期货头寸。
“If investors are seeing their AI-linked bonds losing value, they will be less interested in buying new bonds,” said John Briggs, head of US rates strategy at Natixis North America. “So that’s taken an arrow out of the AI issuance quiver in the short term, and the result is more buying of the Treasury long end as there’s less worry around crowding out.”Trader positioning could also amplify the bond strength if the AI trade extends its weakness. The gains in Treasuries drew fuel from investors known as commodity trading advisers exiting bearish futures positions, after they entered last week at extremely short levels.
避险资金流入有助于缓解持续通胀对债券的压力。上周高于预期的消费者价格数据最初促使交易员加大押注,认为美联储将在本月加息,一度将这一概率推高至约 50%。
The haven flows helped relieve pressure on bonds from persistent inflation. Hotter-than-expected consumer-price figures last week initially prompted traders to boost bets the Federal Reserve will lift interest rates this month, pushing the probability to about 50% at one point.
但随着股票抛售加剧,人们对10月加息的预期逐渐减弱。在联邦储备委员会主席凯文·沃什出席国际货币基金组织年会并仅重申美联储将实现价格稳定,而未就货币政策或其经济前景发表其他言论后,这种预期进一步降低。
But as the stock selloff intensified, the perceived chances of an October hike diminished. They dwindled further after Federal Reserve Chairman Kevin Warsh, appearing at the International Monetary Fund’s annual meetings, made no remarks on monetary policy or his economic outlook, apart from reiterating that the Fed will deliver price stability.
交易员仍预计美联储将在今年内紧缩一次,并在2027年再次紧缩。基于这些预期,标准银行的史蒂文·巴罗将近期的债券 rally 称为“红鲱鱼”。该公司G-10策略主管指出,通胀风险仍在前方,同时存在一种结构性趋势:投资者正转向股票持有,而远离主权债券。
Traders still see the central bank tightening once by year-end and again in 2027. Given those expectations, Standard Bank’s Steven Barrow called the recent bond rally a “red herring.”The firm’s head of G-10 strategy pointed to the inflation risk ahead and a structural trend toward equity ownership and away from sovereign bonds.
周五油价飙升,因伊朗战争导致油价大幅上涨并加剧了通胀担忧,这也凸显了债券作为对冲工具的角色如何轻易被颠覆。随着人们对特朗普总统释放更多俄罗斯柴油进入全球市场的协议产生疑虑,原油价格在午间左右跳升,美债和股票价格随之同步走弱。
A Friday surge in oil prices, which have soared amid the Iran war and fanned inflation concerns, also showed how easily bonds’ role as a hedging instrument can be upended. Both Treasuries and stocks weakened in parallel around midday as crude jumped amid doubts about President Donald Trump’s deal to release more Russian diesel into global markets.
展望未来,沃什缺乏前瞻性指引——这是他货币政策方法的核心原则——导致市场不确定性增加,使市场更容易出现大幅价格波动,State Street Investment Management驻东京的高级固定收益策略师Masahiko Loo如是说。
Looking forward, the uncertainty stemming from the lack of forward guidance coming from the Warsh — a core principle of his monetary-policy approach — leaves the market more vulnerable to large price swings, said Masahiko Loo, a Tokyo-based senior fixed-income strategist at State Street Investment Management.
然而,对于长期投资者而言,“情况看起来不同,”Loo表示。“如果我们迎来一次更大规模的AI驱动的风险规避事件,美债越来越显示出能够提供投资者在过去几年里一直缺失的对冲能力。”经济数据:美联储日程:拍卖日程:
However, for longer-term investors, “the picture looks different,” Loo said. “If we get a bigger AI-driven risk-off episode, Treasuries increasingly appear capable of providing the hedge investors have been missing for much of the last few years.”Economic data: Fed calendar: Auction calendar: