苹果公司(Inc.)本周将推出大量新产品并改进部分旧产品,但投资者并不确定这些新品是否足以提振该市场中估值最高且数月来几乎原地踏步的股票之一。
Inc. is rolling out a slew of new products and improved older ones this week, but investors are unsure if it will be enough to boost one of the most expensive stocks in the market that’s largely gone nowhere in months.
根据《彭博新闻社》的一份报道,这家iPhone制造商将于周二举办一场智能家居产品发布会,推出苹果门铃和苹果恒温器。本月晚些时候,该公司计划推出一款触屏MacBook和一款新的iPad mini。周五,全新折叠屏iPhone Duo将开始接受预订,这代表着苹果最赚钱设备历史上最大的一次设计变革,同时也伴随着相应高昂的价格。
The iPhone maker is holding a smart-home products event on Tuesday featuring an Apple doorbell and Apple thermostat, according to a Bloomberg News report. Later this month, the company is planning to launch a touchscreen MacBook and a new iPad mini. And on Friday, pre-orders begin for the new foldable iPhone Duo, which represents the biggest design change in the history of Apple’s most profitable device and carries a commensurately hefty price tag.
苹果公司的股价面临着巨大的风险。由于有关其进军智能家居市场的报道,以及市场对苹果一直避免的大规模人工智能支出的怀疑,该股价在7月下旬曾飙升至创纪录水平。但在随后的几个月里,该股票基本持平。
The stakes are high for Apple shares, which soared to a record in late July amid reports about its push into the smart-home market and skepticism about heavy artificial intelligence spending that Apple has avoided. But the stock is basically flat in the months since.
“对于一家这种规模的公司来说,你需要超级热销的产品来推动增长,”安德森资本管理公司(Andersen Capital Management)首席投资官彼得·安德森(Peter Andersen)表示,他协助管理着55亿美元资金。“我只是不确定我们所得到的任何产品都足够令人兴奋,足以引领一次转机。”该股今年已上涨25%,使苹果成为七大科技巨头中表现最好的公司。
“For a company of this size, you need super-hit products to move the needle on growth,” said Peter Andersen, who helps oversee $5.5 billion as chief investment officer of Andersen Capital Management. “I’m just not sure anything we’re getting is exciting enough to lead to an inflection.”The stock is up 25% this year, making Apple the top performer among the Magnificent Seven tech giants.
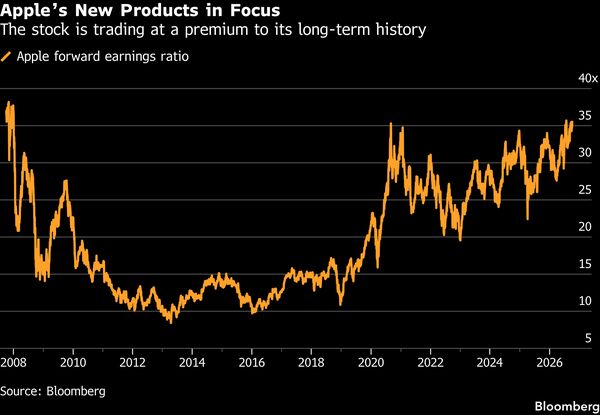
其交易价格超过未来12个月预期盈利的35倍,大约处于2007年以来的最高市盈率附近,且远高于其24倍的10年平均水平。苹果是标普500指数中估值最高的前50只股票之一,该指数的预期市盈率为19倍。
It trades at more than 35 times earnings estimated over the next 12 months, right around its highest multiple since 2007 and well above its 10-year average of 24. Apple is among the 50 most expensive stocks in the S&P 500 Index, which is priced at 19 times forward earnings.
其中部分反映了苹果在人工智能交易中的独特地位,即它并未面临支出风险,但被认为是该技术发展的关键受益者。这也表明了投资者对新任首席执行官约翰·特纳斯(John Ternus)的高期望,以及他们希望他能通过升级和扩展设备产品线来推动增长。
Some of that reflects Apple’s unique position within the AI trade, where it isn’t exposed to spending risk but is considered a key beneficiary of the technology’s development. And it shows investors’ high expectations for new Chief Executive Officer John Ternus and their hopes that he can generate growth by upgrading and expanding its lineup of devices.
然而,这也伴随着风险。根据彭博行业研究(Bloomberg Intelligence)上周的一份报告,由于需求低于预期,该公司已经削减了某些iPhone型号的零部件订单。与此同时,消费者正受到顽固通胀的压力,由于内存芯片等零部件成本上升,苹果不得不提高价格。
That’s a risk, however. The company has cut component orders for some iPhone models due to weaker-than-expected demand, according to a Bloomberg Intelligence report last week. Meanwhile, consumers are feeling pressured by stubborn inflation, and Apple has had to raise prices due to higher costs for components like memory chips.
“苹果完美地执行了其产品,但很难期望这些产品能真正腾飞,”不持有苹果股票的安德森说,部分原因是他认为该公司缺乏创新。“不仅家居市场多年来一直有主要玩家,而且苹果推出这些产品的市场正面临着巨大压力。”此外,苹果的增长率落后于其大型科技同行,这使得其高昂的股市估值比以往更加引人注目。该公司的财年已于9月30日结束,预计在几周后公布财报时,其年度营收将增长15%。但这似乎已接近峰值,预计在2027财年增速将放缓至10%,在2028财年放缓至7.8%。
“Apple executes its products flawlessly, but it’s hard to expect these will really take off,” said Andersen, who doesn’t own the stock, in part due to what he sees as the company’s lack of innovation. “Not only have there been major players in the home market for years, but Apple is launching these products into a market where consumers are under a lot of pressure.”What’s more, Apple’s growth rate is lagging its Big Tech peers, making its high stock market valuation stand out even more than it already does. The company’s fiscal year ended on Sept. 30, and it’s projected to post a 15% rise in annual revenue when it reports earnings in a few weeks. But that appears to be a near-peak, with the pace expected to slow to 10% in fiscal 2027 and 7.8% in fiscal 2028.
“苹果看起来既不像价值股,也不像成长股,”安德森说,“鉴于目前的市盈率,从这里期望股票有太多的额外上涨空间似乎是有问题的。”当然,苹果在增长放缓方面并不孤单。总体科技销售额预计将在未来几年经历减速,尽管起点要高得多。根据彭博行业研究的数据,标普500信息技术板块的营收预计在2026年将增长37%,在2027年增长29%。
“Apple doesn’t look like a value stock or a growth stock,” Andersen said. “Given where the multiple is, it seems questionable to expect much additional stock upside from here.”Of course, Apple isn’t alone in its slowing growth. Overall tech sales are expected to experience a deceleration in the coming years, albeit off a much higher level. Revenue is projected to climb 37% for the S&P 500 information tech sector in 2026, and 29% in 2027, according to Bloomberg Intelligence.
苹果的新产品是否会改变公司的盈利前景还有待观察。但华尔街并没有竞相调整其预测。在过去三个月中,分析师对该公司2027财年净利润的预期下降了0.6%,而对其营收的预期则上升了0.7%。
Whether Apple’s new products will alter the company’s earnings outlook remains to be seen. But Wall Street hasn’t been racing to adjust its projections. Analysts’ expectations for the company’s fiscal 2027 net income have dipped by 0.6% over the past three months, while their view for revenue has risen 0.7%.
“苹果的产品路线看起来很有前景,但我认为第一代新产品对整体营收不会有太大意义,”融合基金(Fusion Fund)创始人兼管理合伙人张璐(Lu Zhang)说,她在个人投资组合中持有该股票。“我们是否会看到那种有助于广泛升级周期的(折叠屏Duo的)新用例,还有待观察。”尽管如此,张璐对该股票仍持乐观态度。她说,苹果可以改进其人工智能产品,但它将继续受益于成为消费者访问新兴技术的门户。
“Apple’s product path seems promising, but I don’t think the first generation of new products will mean much for overall revenue,” said Lu Zhang, founder and managing partner of Fusion Fund, who owns the stock in her personal portfolio. “It remains to be seen whether we will see the kind of new use cases (for the foldable Duo) that will contribute to a broad upgrade cycle.”Nevertheless, Zhang remains positive on the stock. Apple could improve its AI offerings, she said, but it will continue to benefit from being a gateway for consumers to access the emerging technology.
“所有的人工智能公司都在互相竞争,但每当它们推出新模型时,都需要苹果作为关键分销渠道,而这是它基本上没有竞争对手的领域,”她说,“即使Duo的采用率在刚推出时并不高,只要苹果继续执行其硬件战略,它就值得拥有溢价估值。”
“All the AI companies are competing with each other, but whenever they launch a new model they need Apple as a key distribution channel, and that’s an area where it essentially has no competitor,” she said. “Even if Duo adoption isn’t high right out of the gate, so long as Apple continues to execute on its hardware, it will warrant a premiere multiple.”