从为数据中心项目融资的人工智能公司,到债台高筑的法国政府,随着投资者对借贷风险愈发警惕,信贷市场正在释放警示信号。
From AI companies financing data center projects to France's heavily indebted government, credit markets are flashing warnings as investors grow warier of borrowing risks.
据CNBC对FactSet数据的分析,CoreWeave、甲骨文和软银集团,以及法国和意大利的五年期信用违约互换(CDS)利差均已扩大。
Five-year credit default swap spreads have widened for CoreWeave, Oracle and SoftBank Group, as well as France and Italy, according to CNBC's analysis of FactSet data.
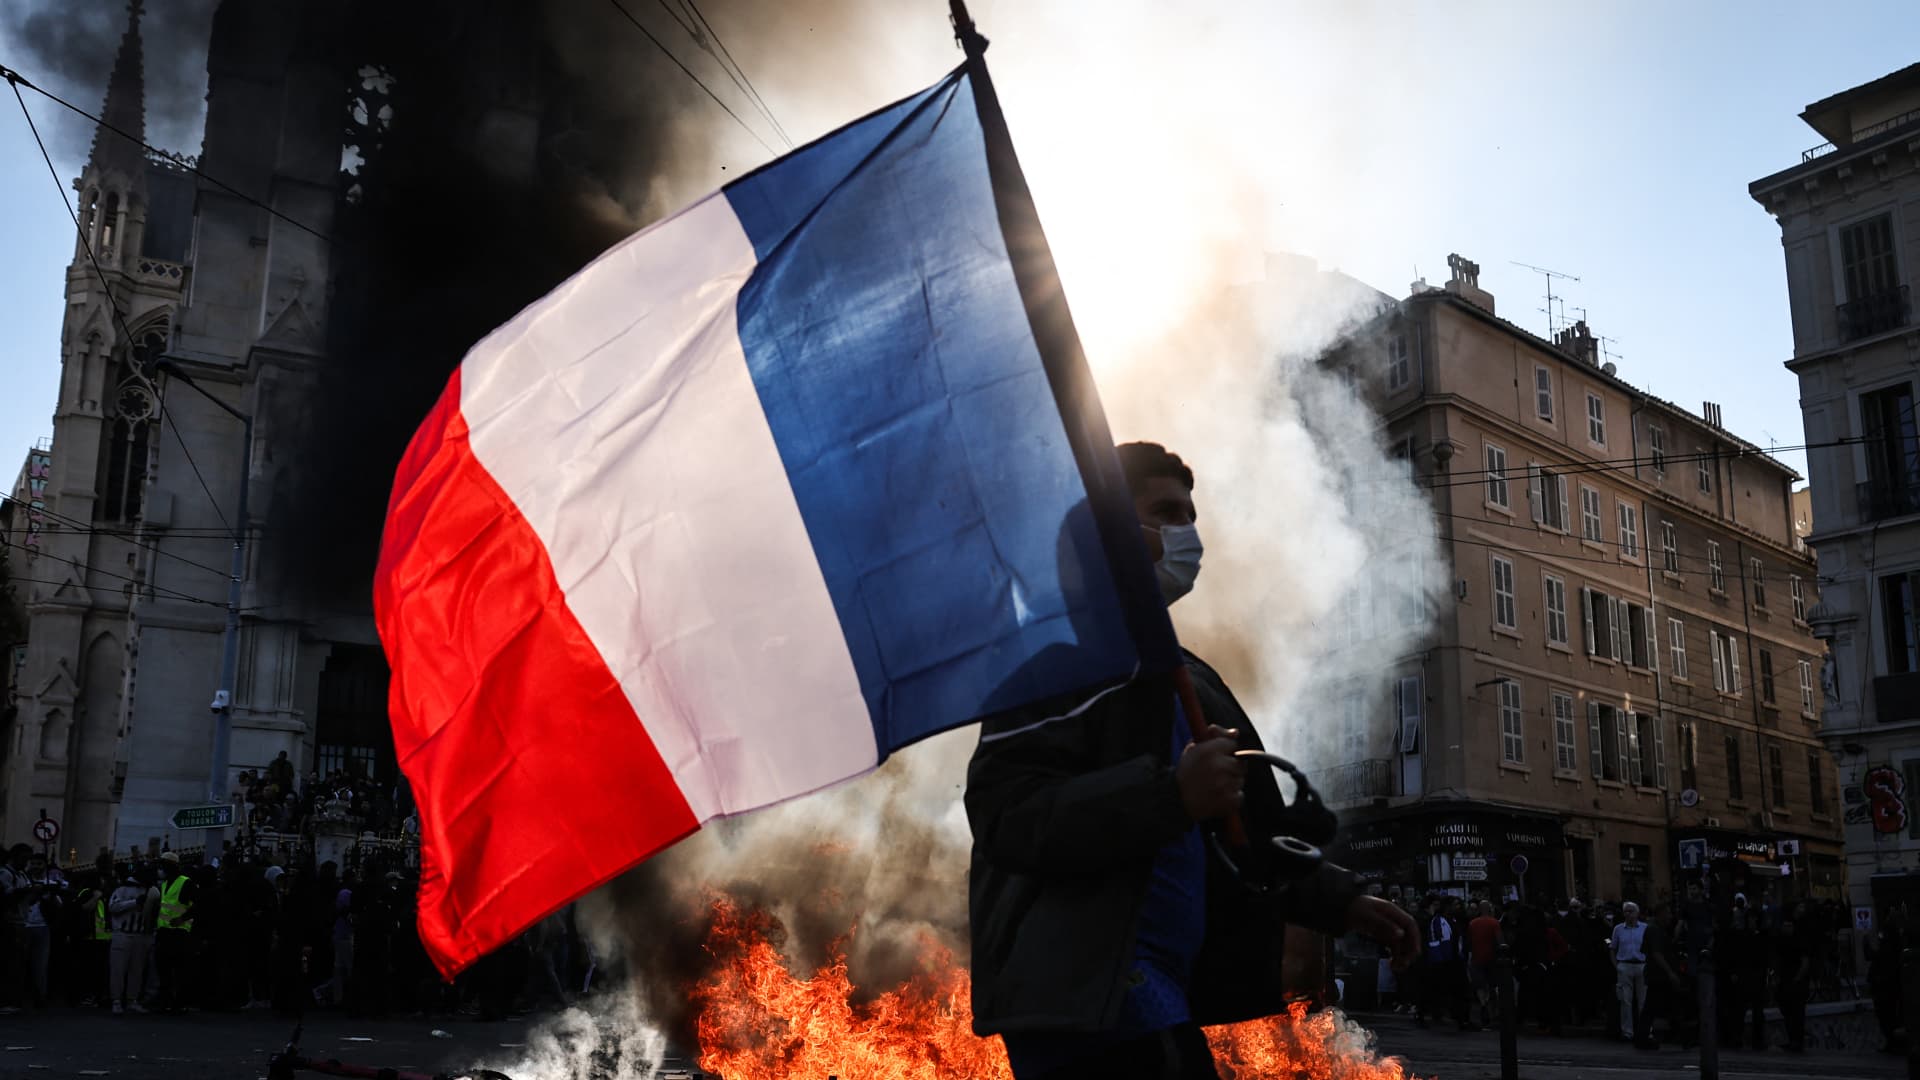
随着市场因担心融资紧缩而提高资本成本,与AI相关的债券遭遇抛售。英伟达首席执行官黄仁勋周四对CNBC表示,Neocloud(新型云服务商)的需求“极其旺盛”,但他警告存在“资本短缺”问题。他说:“对资本的需求远大于资本的可获得性”,并补充称,“这将会得到解决。”法国等国家面临类似的紧缩局面。随着投资者要求更高补偿以融资公共债务,债券市场压力不断加大。法国近期发生的大规模抗议和骚乱加剧了市场的担忧。
AI-related bonds have been selling off as markets raise the cost of capital amid concerns of a financing crunch. Neocloud demand is "off the charts," Nvidia CEO Jensen Huang told CNBC on Thursday, but he warned of a "scarcity of capital." "The demand of the capital is much greater than the availability of the capital," he said, adding, "that's going to get solved." Countries like France face a similar crunch. Pressure is building in bond markets as investors demand more compensation to finance public debt. Recent mass protests and rioting in France have heightened the market's concerns.
FedWatch Advisors首席投资官兼创始人Ben Emons在其“French Neoclouds”Substack专栏文章中写道:“市场可能不再愿意为巨额资本支出、高杠杆和不确定的未来现金流提供承销,这种同样的转变正在扩大法国主权利差,因为投资者要求更高补偿才愿持有期限长、债务融资的义务,而发债方是一个财力紧张的国家。”
"Markets may no longer want to underwrite massive capex, heavy leverage, and uncertain future cash flows, and that same shift is widening French sovereign spreads as investors demand more compensation to hold long‑duration, debt‑financed obligations from a strained state," FedWatch Advisors CIO and founder Ben Emons wrote on his "French Neoclouds" Substack post.
CoreWeave、甲骨文和软银处于AI基础设施建设的核心地位,涵盖数据中心、云服务和融资等领域。
CoreWeave, Oracle and SoftBank are at the heart of the AI infrastructure buildout, spanning data centers, cloud services and financing.
它们的五年期CDS利差为投资者对这一切成本及最终回报的焦虑提供了一个观察窗口。利差走高意味着违约保护成本更高,可能预示着对借款人偿债能力的担忧加剧。
Their five-year CDS spreads offer a window into investors' anxiety about the cost of it all and eventual payoff. Higher spreads mean more expensive default protection and can signal greater concern about a borrower's creditworthiness.
据FactSet数据,CoreWeave的违约保护成本涨幅最为显著之一。其五年期CDS利差于10月21日达到1065.84个基点,反映出市场对这家高负债公司为其扩张融资能力的担忧加剧。
CoreWeave has experienced some of the sharpest increases in default-protection costs. Its five-year CDS spread reached 1,065.84 basis points on Oct. 21, according to FactSet, reflecting heightened concerns about the debt-heavy company's ability to finance its expansion.
与此同时,甲骨文的信用利差于10月21日升至308.25个基点,高于1月2日的141个基点。标普信用评级在7月将甲骨文的债务评级下调至投资级最低档,理由是不断扩张的基础设施业务增加了整体信用风险。
At the same time Oracle's spread rose to 308.25 basis points on Oct. 21, up from 141 on Jan. 2. S&P Credit Ratings downgraded Oracle's debt to the lowest level of investment grade in July, citing the expanding infrastructure business raised the overall credit risk.
软银是主要的人工智能投资者,持有OpenAI的大额股份,并投资于数据中心和电力基础设施,包括在法国投资数据中心的870亿美元承诺。其五年期信用违约互换(CDS)利差于10月20日站上近四年高点432个基点,高于1月5日的284个基点。
Softbank is a major AI investor with a large stake in OpenAI and investments in data centers and power infrastructure, including an $87 billion commitment for data centers in France. Its five-year CDS spread stood near a four-year high of 432 basis points on Oct. 20, up from 284 basis points on Jan. 5.
法国尚未陷入全面债务危机,但市场正发出不安信号:防范主权违约的成本已升至意大利之上,而意大利的成本也在上升。
France isn't in a full-fledged debt crisis, but markets are signaling unease with the cost of protecting against a sovereign default rising above that of Italy's, which has also increased.
据CNBC分析,法国五年期信用违约互换利差于10月21日达到89.8个基点,高于1月2日的29.74个基点。意大利的利差于10月22日增至67.1个基点,1月2日为28.33个基点。法国的预算不确定性和债务负担已成为关注焦点,引发担忧风险可能蔓延至欧洲其他国家。
France's five-year credit default swap spread reached 89.8 basis points on Oct. 21, up from 29.74 basis points on Jan. 2, according to CNBC's analysis. Italy's spread increased to 67.1 basis points on Oct. 22 from 28.33 on Jan 2. France's budget uncertainty and debt burden have become a focus, raising concerns that the risk could spill over to other countries in Europe.
德国的利差也有所上升,但仍维持在远低水平,于10月22日为12.15个基点,而期初为7.47个基点。
Germany's spread also rose but remained much lower at 12.15 basis points on Oct. 22, compared with 7.47 at the start of the period.
麦格理集团全球外汇和利率策略师Thierry Wizman指出,法国不断攀升的债务负担和持续的财政赤字是违约保护成本上升的关键驱动因素。
Thierry Wizman, global FX and rates strategist at Macquarie Group, pointed to France's mounting debt burden and persistent fiscal deficits as key drivers of rising default-protection costs.
“关键驱动因素是巨额的法国主权债务(占GDP的120%)以及无法削减赤字,”Wizman告诉CNBC。相比之下,德国政府债务占该国GDP的65%。
"The key drivers are the large amount of French sovereign debt (120% of GDP) and the inability to reduce the deficit," Wizman told CNBC. In comparison to France, German government debt is 65% of the country's GDP.
投资者们也在密切关注法国债券与德国债券之间的利差——这一利差被视为欧洲国家信用状况的“基准”。目前,法国债券与德国债券之间的利差已飙升至1.6个百分点;法国10年期国债的收益率也自2002年以来首次超过了5%。投资者之所以愿意持有法国债券而非德国债券,就是因为他们要求获得更高的额外回报。
Investors are also watching the spread between French and German bonds, considered the European benchmark of creditworthiness, which has also surged to 1.6 percentage points. France's 10-year bond yield also topped 5% for the first time since 2002. The spread between the 10-year yield on French OATs and German Bunds is the extra payment investors demand to hold French bonds instead of German.
尽管法德之间的利差目前仍然较大,但在2010年代初的欧元区债务危机期间,欧元区的借贷成本差距实际上更为显著。
While the Franco-German spread is relatively wide, the Eurozone saw far larger gaps in borrowing costs during the Eurozone debt crisis of the early 2010s.
法国将在10月23日面临另一项考验:穆迪(Moody’s)将重新评估法国的Aa3主权信用评级(该评级的前景为“负面”)。由于政治分歧的存在,法国的财政整顿工作变得更加复杂。
France faces another test on Oct. 23 when Moody's is scheduled to review its Aa3 sovereign rating, which carries a negative outlook. The review comes as political divisions complicate efforts to repair the country's public finances.
虽然人工智能(AI)融资领域出现了一些问题,但债务市场也在预期更高的借贷成本。标普全球(S&P Global)在10月19日警告称,主要的云计算服务提供商可能拥有比公开披露的更多的与AI相关的债务。
While stresses are popping up in some pockets of AI financing, debt markets are also pricing in higher costs. S&P Global warned on Oct. 19 that major cloud providers may have more AI-linked debt exposure than publicly recognized.
信用违约互换(CDS)指数通过追踪各类公司的违约保护成本,能够更全面地反映信用市场的压力状况。根据LSEG的数据,北美地区的CDX高收益指数(CDX High Yield Index)显示,截至10月20日,该指数五年期的利差中位数已达到355.35个基点,较2025年底上升了约39个基点。
CDS indexes offer a broader picture of credit-market pressure by tracking default-protection costs across baskets of companies. North America's CDX High Yield index captures credit risk across speculative-grade companies. Its five-year midpoint spread reached 355.35 basis points on Oct. 20, up about 39 basis points from the end of 2025, according to data from LSEG.
这种利差的扩大表明,投资者对所有企业的信用风险都要求更高的补偿(即要求更高的利息回报),而不仅仅是那些与AI相关的借款企业。
The widening suggests investors are demanding more compensation for credit risk beyond AI-linked borrowers.