随着市场对人工智能的热情逐渐降温,甲骨文公司的债券评级正岌岌可危地逼近“垃圾级”水平。上周,人工智能相关投资热潮大幅退潮,以新云服务提供商CoreWeave为首,该公司的股票与债券价格均出现暴跌。
Oracle bonds are sitting dangerously close to junk territory as markets cool on artificial intelligence. Much of the AI trade fizzled last week, led by CoreWeave — the neocloud company whose equity and debt has been tanking.
如今,甲骨文面临着信用评级被下调的风险,一旦评级降至垃圾级,其债务状况也将随之恶化,进而可能对整个人工智能领域的融资生态产生连锁反应。
Oracle now faces risk of credit rating downgrades that could tip its debt into junk territory — with potentially cascading effects across the AI financing ecosystem.
“市场情绪似乎正在发生转变,这种转变似乎预示着2026年的整体走势:此前我们对各类资产都持极度乐观态度,如今却又变得极度悲观,”Dynasty Financial Partners的投资解决方案主管帕特·纳尼说道,“这也充分体现出这个市场的波动速度有多快。”不过,CoreWeave与甲骨文之间存在明显差异:甲骨文目前仍属于投资级企业,而CoreWeave的信用评级早已跌入垃圾级。部分分析师及固定收益类投资者向CNBC表示,目前他们尚未对甲骨文及其他大型云计算服务商感到担忧。
"There seems to be a sentiment shift, which almost speaks to 2026 in general, where we're so bullish about everything and then we're so bearish about everything," said Pat Nerney, head of investment solutions at Dynasty Financial Partners. "It just shows you how quickly this market moves." But there are key differences between CoreWeave and Oracle — the latter is investment grade while Coreweave is already in junk territory. Some analysts and fixed income investors tell CNBC they aren't concerned yet about Oracle and the other hyperscalers.
尽管如此,从甲骨文五年期信用违约互换的价差变化仍能看出市场情绪的转变。信用违约互换是一种用于防范债务违约风险的保险工具。标普全球市场财智的固定收益定价执行总监加万·诺兰指出,目前该价差水平更接近于BB级及B级信用评级所对应的水平,这些均属于高收益债券范畴。
Still, the shift in sentiment can be seen in the spread of Oracle's five-year credit default swaps, which are insurance against default. The range is more in line with BB and B credit, which is high yield, said Gavan Nolan, executive director of fixed income pricing at S&P Global Market Intelligence.
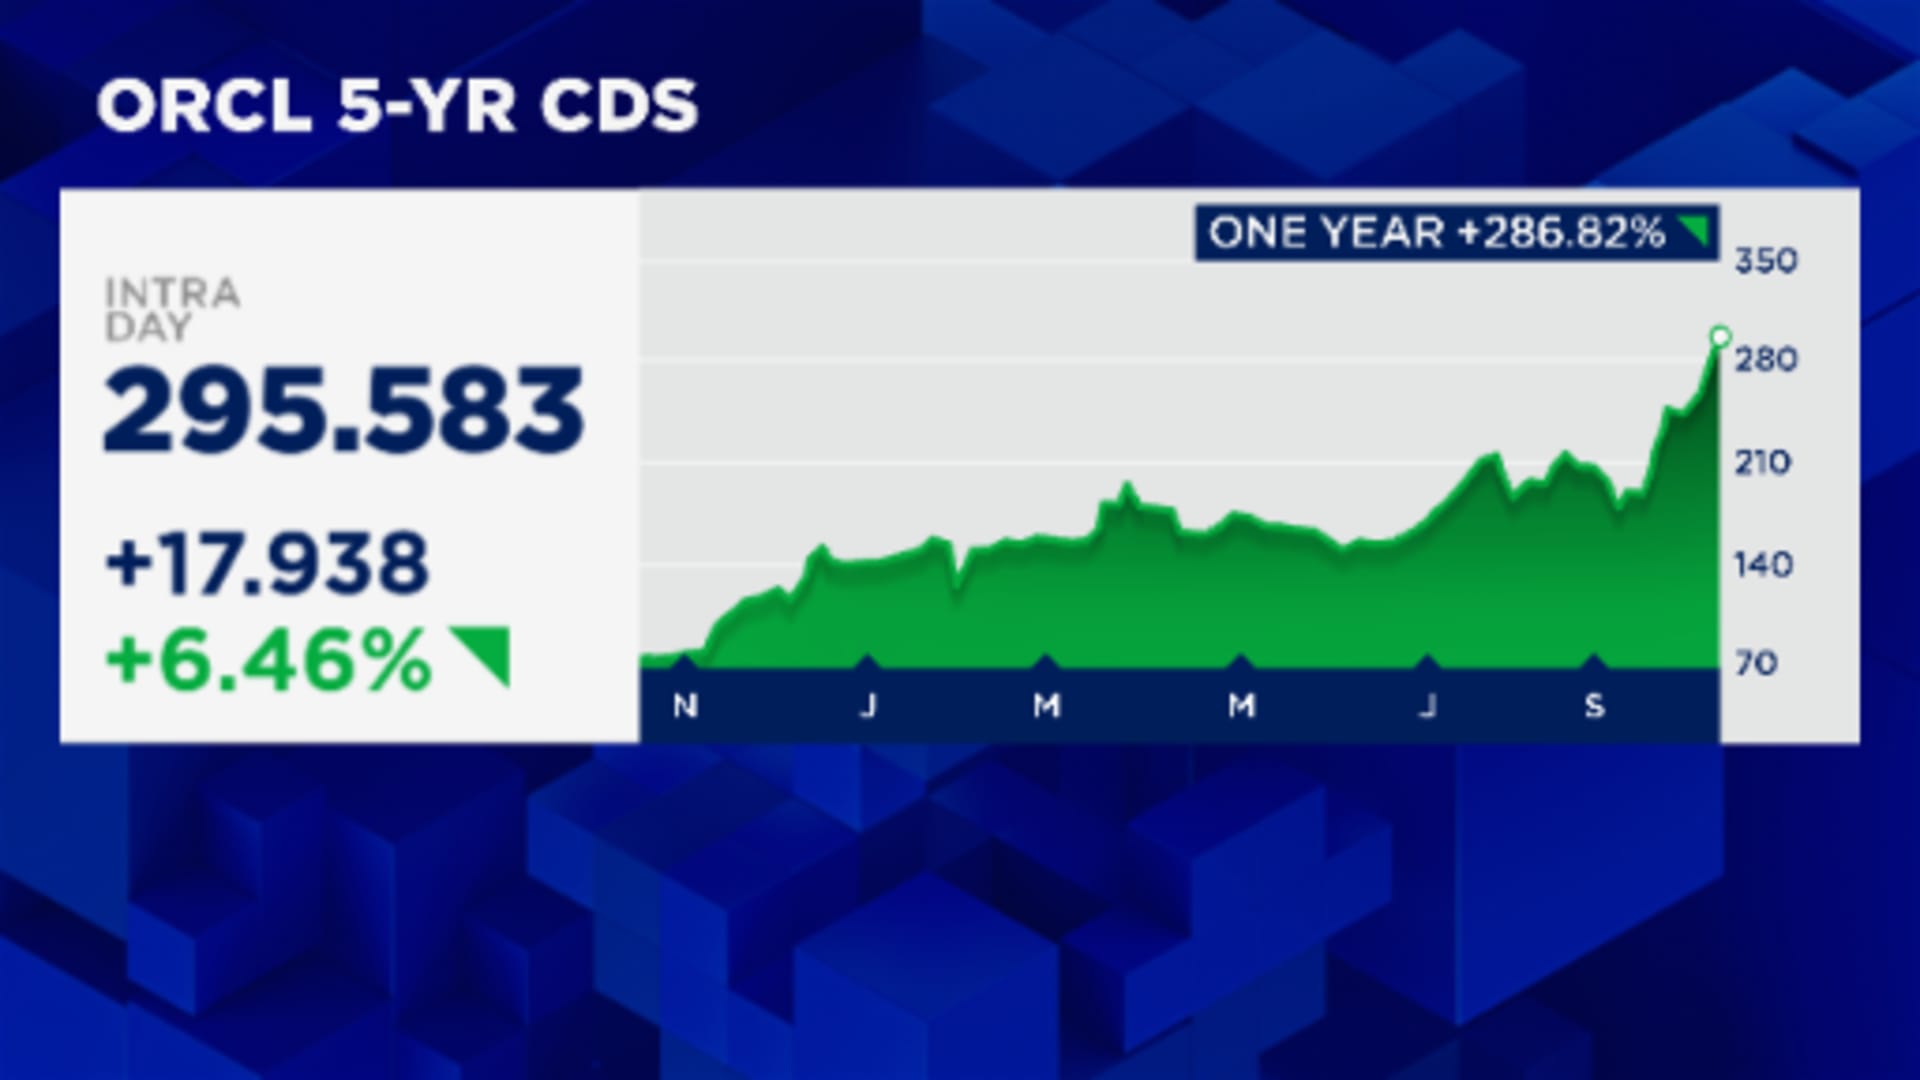
目前,甲骨文五年期信用违约互换的价差为295个基点,周四时曾短暂触及300个基点,这一数值较一年前增长了287%。
The spread on Oracle's five-year CDS is currently 295 basis points, after briefly hitting 300 bps on Thursday, up 287% in one year.
“甲骨文相关的信用违约互换交易流动性极佳。不过过去几天其价差波动剧烈,这无疑反映出市场对人工智能相关企业的信心十分脆弱,尤其是那些属于高收益债券范畴或处于投资级评级下游的企业,甲骨文正是其中之一,”他在给CNBC的邮件中说道。
"Oracle CDS is supported by high liquidity. Nonetheless, its spreads whipsawed over the last few days, no doubt a reflection of the fragile sentiment in AI-related names, notably those in HY [high yield] and at the weaker end of the IG [investment-grade] spectrum, such as Oracle," he said in an email to CNBC.
信用违约互换是一种金融合约:买方支付费用以换取在借款方无法偿还债务时的风险保障。此类互换价差扩大,意味着投资者认为相关债务的风险水平正在上升。
Credit default swaps are contracts where buyers pay for protection in case the borrower can't repay its debt. The spread widening in CDS means investors view the debt as riskier.
甲骨文的评级为标普信用评级BBB-,这是投资级别评级中的最低水平。标普在7月份下调了甲骨文的评级,指出该公司快速扩张的基础设施业务正在增加其整体信用风险。标普还表示,预计2027年公司的经营性现金流将更弱。“风向标”甲骨文主要是一家企业软件公司,但它正大举进军数据中心和云服务领域,包括与OpenAI达成的价值3000亿美元的巨额交易。根据FactSet的数据,为了资助这一扩张,甲骨文已发行1180亿美元的长期债务,还有另外390亿美元的资本和租赁义务。
Oracle's rating is S&P Credit Ratings is BBB-, the lowest level in the investment-grade spectrum. The agency downgraded Oracle in July, noting that the company's rapidly expanding infrastructure business is increasing its overall credit risk. S&P also said it expects weaker operating cash flow in 2027. A 'bellwether' Oracle is primarily an enterprise software company but it's barreling into data centers and cloud services, including a massive $300 billion deal with OpenAI. To fund the buildout, Oracle has issued $118 billion in long-term debt and has another $39 billion in capital and lease obligations, according to FactSet data.
这些支出和债务义务正在影响甲骨文的财务状况,而公司正在等待AI带来的收入激增。根据共识预测,分析师估计甲骨文今年的自由现金流为-237亿美元,2027年为-360亿美元。
The spending and debt obligations are taking a toll on Oracle's finances while the company waits for a gusher of AI revenue. Analysts estimate free cash flow of -$23.7 billion this year and -$36 billion in 2027, according to consensus forecasts.
这对投资者来说已经够糟了,但甲骨文不仅仅是一家负债累累的数据中心公司。正如德意志银行全球宏观和主题研究主管Jim Reid所指出的,甲骨文已经成为AI的“风向标”。他在一份报告中表示,若其信用评级被下调至垃圾级别,“将有可能迫使仅持有投资级别债券的投资者被迫抛售”。
That would be bad enough for investors, but Oracle is more than just a debt-laden data center play. It's become an AI "bellwether," notes Jim Reid, global head of macro and thematic research at Deutsche Bank. A downgrade of its credit into junk territory "would risk pressuring IG-only investors into forced sales," he said in a report.
标普在7月份的下调报告中表示,若出现以下情况,可能会触发另一次下调:预计甲骨文的杠杆率将持续超过4倍;或认为这家软件公司未能在2029财年之前实现正的经营性自由现金流;或对甲骨文的AI战略,乃至整个AI行业的前景持负面看法。
S&P said in its July downgrade that another downgrade could be triggered by: an expectation that Oracle will sustain leverage exceeding 4x; or belief that the software company isn't on a path to generate positive free operating cash flow by fiscal 2029; or a negative view on Oracle's AI strategy or that of the overall AI industry.
作为一家投资级别公司,甲骨文可以以低成本和长期借款,但若被下调为垃圾级别,这种情况将会改变。持有甲骨文股票的Laffer Tengler公司的高级证券分析师Jamie Meyers如此表示。
As an investment-grade company, Oracle can borrow cheaply and with duration, but that would change with a junk rating, said Jamie Meyers, a senior securities analyst at Laffer Tengler, which owns Oracle stock.
“没有人会在高收益领域购买30年期债务,”他说。“如果被降级为垃圾债券,那就意味着他们必须把所有东西都压到短期。显然,他们的借贷成本会更高,而且很可能如此。”不过,梅耶斯对甲骨文的债务水平并不担心。去年甲骨文与拉弗·滕格勒会面时,甲骨文强调将捍卫其投资级评级,梅耶斯说。
"Nobody in high yield is going to buy a 30 year debt," he said. "Getting downgraded to junk would mean that they'd have to push everything short. Obviously, their borrowing rate would be higher, more than likely." That said, Meyers is not concerned about Oracle's debt levels. In a meeting between Oracle and Laffer Tengler last year, Oracle stressed it will defend its investment-grade rating, Meyers said.
“我们确实相信收入将开始增长,利润也将开始增长,”他说。“甲骨文真正需要的是……时间。他们需要把这些东西建好。”先锋固定收益投资组合经理布拉德·柯林斯也对甲骨文及其他超大规模云服务提供商表示信心。
"We do believe the revenue is going to start ramping and the earnings are going to start ramping," he said. "What Oracle really needs is … time. They need to get these things built." Brad Collins, a fixed income portfolio manager at Vanguard, also expressed confidence in Oracle and the other hyperscalers.
“甲骨文目前受到最严格的审查,但正因为如此,到目前为止今年他们在发行方面更加审慎,”他说。“资产负债表处于健康的起点,[我]不会把我们在高收益领域看到的情况外推到投资级领域。”王朝金融合伙公司的纳尼表示,公司目前的困境可以视为一种“融资考验”。他们要么通过,要么失败,失败可能意味着进一步降级,他说。
"Oracle is most under the microscope, but as a result, has been more diligent in their issuance" so far this year, he said. "Balance sheets are in a healthy starting spot, and [I] would not extrapolate what we are seeing in HY to IG." The company's current troubles could be looked at as a "financing test," said Dynasty Financial Partners' Nerney. They'll either pass or fail, which could mean an additional downgrade, he said.
“现在真正的问题是,随着利率变动,这将带来多少成本?”他说。“如果利率继续上升,投资者持有甲骨文债券相较于市场上其他资产的机会成本,你就会看到市场需求增加。”甲骨文回应置评请求时表示:“我们一直非常明确,作为一家公司,维持投资级评级是我们的首要任务。”“人工智能基础设施业务具有强劲的经济回报,我们预计一旦项目启动并 ramp up,将产生强劲的自由现金流。”它还补充道。
"The real question now is, with the move in rates, how much is that going to cost?" he said. "If rates continue to move higher, just the opportunity cost of investors to hold Oracle paper relative to other things in the market, you're going to see the market demand more." Oracle responded to a request for comment by saying, "We have been very clear that maintaining an investment grade rating is our first priority as a company." "The AI infrastructure business has strong economic returns and we expect it will produce strong free cash flows once projects are ramped," it added.