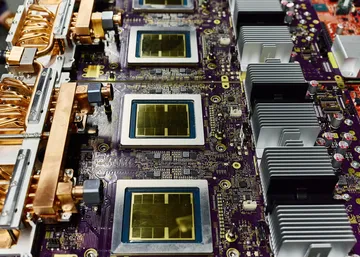
和 Dina Bass“什么是GPU?”Blackstone Inc.的高管们向CoreWeave Inc.的领导层提问。还有:“AI是真的吗?”这些问题在AI热潮的早期阶段完全合乎逻辑,当时CoreWeave仍是一家鲜为人知的AI云公司,正在寻找资金购买芯片。Blackstone的战术机会组织对所得到的答案深信不疑,并于2023年主导了一笔23亿美元的私人信贷贷款。
By Paula Seligson and Dina Bass“What is a GPU?”Blackstone Inc. executives asked CoreWeave Inc.’s leadership. Also: “Is AI real?”These were entirely logical queries in the early innings of the AI boom, and at a time when CoreWeave was still a little-known AI cloud company on the hunt for funds to buy chips. Blackstone’s tactical opportunities group was convinced by the answers it received, and led a $2.3 billion private credit loan in 2023.
这标志着此类交易的首笔重大交易,并成为芯片担保债务的蓝图。三年过去,该市场有望达到万亿美元规模,甚至超越了用于建设容纳这些芯片的数据中心的借款。
This marked the first major deal of its kind and became a blueprint for chip-backed debt that, three years on, is on track to become a trillion-dollar market, eclipsing even the borrowings used to build the data centers housing the chips.
这证明了全球AI扩张与信贷市场在如此短的时间内变得多么紧密交织。就在本周,Blackstone总裁Jon Gray将AI需求描述为近乎“抛物线式”。但CoreWeave也体现了人们对该领域投入资金的担忧——其股票和公司债券在过去几周里遭受重创,因为投资者质疑AI收入是否能证明这惊人的支出是合理的。
It’s a testament to how intertwined the global AI expansion and credit markets have become in such a short time. Just this week, Blackstone President Jon Gray called demand for AI almost “parabolic.”But CoreWeave is also emblematic of the anxiety around the money being poured into the space — its stock and corporate bonds have been battered in recent weeks as investors question whether AI revenues can ever justify the breathtaking spend.
市场预计的增长吸引了几乎每一家主要美国银行和另类资产管理公司,以及AI芯片制造商Broadcom Inc.和Nvidia Corp.的支持,这两家公司的总价值约为7万亿美元。
The market’s projected growth has drawn in virtually every major US bank and alternative-asset manager, along with backstops from AI chipmakers Broadcom Inc. and Nvidia Corp., which have a combined value of roughly $7 trillion.
Broadcom正与华尔街公司合作,为一个特殊实体进行600亿美元的债务交易,该实体将购买名为张量处理单元的芯片并将其租赁给Anthropic PBC。与此同时,SpaceX正在洽谈筹集400亿美元用于购买Nvidia芯片。这发生在Nvidia宣布与六家主要贷款机构达成5000亿美元合作伙伴关系,以帮助客户购买其图形处理单元(GPU)之后。
Broadcom is working with Wall Street firms on a $60 billion debt transaction for a special entity that would buy chips known as tensor processing units and lease them to Anthropic PBC. Meanwhile, SpaceX is in talks to raise $40 billion for Nvidia chips. That follows Nvidia’s announcement of a $500 billion partnership with six major lenders to help customers purchase its graphics processing units, or GPUs.
支出规模可能导致债务市场依赖人工智能的盈利能力。这场洪水还可能导致人工智能及其他行业的借贷成本上升,因为科技公司在利率上升的背景下竞争有限的资本。JPMorgan Chase & Co.分析师预测,芯片支出可能在2030年前超过3万亿美元,大部分可能通过借贷来资助。
The scale of the spending risks leaving debt markets dependent upon AI’s profitability. The deluge also threatens to drive up borrowing costs for AI and other sectors as tech firms compete for finite capital amid rising interest rates. JPMorgan Chase & Co. analysts predict chip spending could exceed $3 trillion through 2030, with the majority likely funded by borrowing.
“我们前所未有的看到供应商融资规模如此庞大,而且以风险高度集中的方式进行,”Fitch Ratings资深副总裁杰森·普波蒂(Jason Pompeii)表示。“这增加了如果人工智能最终成为令人失望的故事,供应链将面临连锁反应的可能性。”这种策略建立在这样一种信念之上:对计算能力的需求将在多年内持续超过供应。
“You have vendor financing being done at a scale that we’ve never seen before, and being done in a way that the risk is concentrated,” said Jason Pompeii, a senior director at Fitch Ratings. “That just increases the chance that if AI ends up being a disappointing story, there will be ripple effects throughout the supply chain.”The strategy rests on the conviction that demand for computing power will outstrip supply for years to come.
“这些融资与市场中最有价值的东西——由芯片生产的计算能力相连联,”摩根士丹利全球结构产品及私募市场负责人Rich Myers表示。“市场上有大量证据表明,对计算的需求将持续上升,并且超过计算的供应。”然而,建设进程的持续动力面临风险。
“These financings are attached to the thing of most value in the market, which is the compute capacity produced by the chips,” said Rich Myers, global head of structured products and private capital markets at Morgan Stanley. “There’s a lot of evidence that demand for compute will continue to go up and is outpacing supply of compute.”Yet there are risks to the build-out’s continued momentum.
当地反对声浪导致德克萨斯州对新项目实施数据中心停建令,而Oracle Corp.(甲骨文公司)则因监管拖延而在新墨西哥州的项目中采取措施推迟付款。与此同时,OpenAI和Anthropic正就安全和存在性问题讨论更慢的推出节奏,这发生在一连串事件之后。
Local opposition has sparked a data center moratorium on new projects in Texas, while Oracle Corp. has taken steps to put off payments on a New Mexico project mired in regulatory setbacks. Meanwhile, OpenAI and Anthropic are discussing a slower rollout over safety and existential concerns following a spate of incidents.
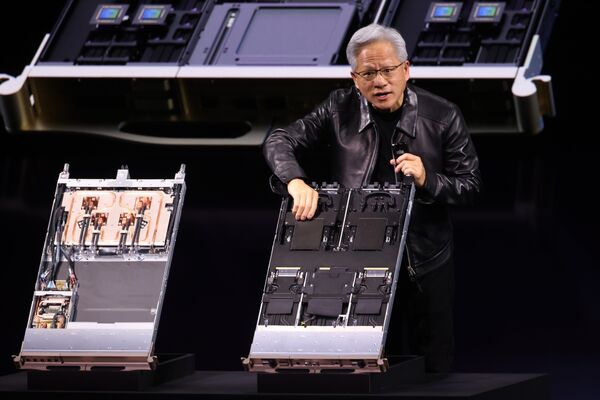
但大部分支出已经锁定在正在建设的超大规模数据中心中,这确保了芯片需求在各个项目陆续投入使用时持续存在。由于供应商基本已售罄,且因严重的存储器短缺推高成本,制作包含Nvidia人工智能芯片的服务器的公司在8月通知客户,在许多情况下芯片价格将上涨超过15%。
But much of the spending is already locked into mega data centers under construction, ensuring chip demand as those sites come online. With vendors largely sold out and severe memory shortages driving costs up, companies that make servers containing Nvidia’s AI chips informed customers in August that prices will rise by more than 15% in many cases.
“这是经济的一个新领域,需要有序的融资机制来支持,”黑石集团战略机会部门高级董事总经理约翰·沃森表示。
“This is a new part of the economy that needs to have an orderly mechanism to finance it,” said John Watson, a senior managing director at Blackstone in the firm’s tactical opportunities group.
对沃森而言,这与汽车工业早期充满不确定的日子以及福特面向大众市场的T型车有相似之处。
For Watson, there’s a parallel to the early, uncertain days of the automotive industry and Ford’s mass-market Model T car.
“如果你当时为福特T型车提供融资,你会问:‘我在干什么?人们真的会开车吗?’”他说。“汽车金融市场稳健、成熟且规模巨大。它成为了美国购买量最大的机器。我们对算力有着类似的愿景。”推动这些资本需求的现实是,芯片成本是容纳它们的数据中心的两到四倍,却在约五到六年内折旧。
“If you were financing the Ford Model T, you would have asked, ‘What am I doing? Are people really going to drive cars?’” he said. “The automotive finance market is robust and well understood and is enormous in scale. It became the most bought machine in America. We have a similar vision for compute.”Fueling these capital needs is the reality that chips cost two to four times more than the data centers housing them, yet depreciate over about five to six years.
例如,在AI云服务商Nscale位于西弗吉尼亚州的旗舰项目中,现场电厂预计耗资65亿美元,数据中心及设备另外需要180亿美元。GPU则高达470亿美元。
At AI cloud provider Nscale’s flagship development in West Virginia, for example, the on-site power plant is expected to cost $6.5 billion and the data center and equipment another $18 billion. The GPUs: $47 billion.
投资级云巨头Alphabet旗下Google、微软、亚马逊和Meta Platforms主要通过现金或廉价的资产负债表内债券发行来覆盖这些硬件成本。但OpenAI和Anthropic正在烧掉数十亿美元,缺乏这些储备和债务市场影响力。所谓“新云”公司——专注于提供AI云计算的企业——情况也是如此。
Investment-grade cloud giants Alphabet Inc.’s Google, Microsoft Corp., Amazon.com Inc. and Meta Platforms Inc. cover these hardware costs largely through cash or cheap on-balance-sheet bond sales. But OpenAI and Anthropic, burning through billions, lack those reserves and debt market clout. The same is true of neoclouds, companies focused on offering cloud computing for AI.
“基础设施建设规模空前,”OpenAI业务财务官迈克·利贝拉托雷表示。“没有现成的剧本告诉你如何从零走向AGI,并通过传统方式筹集资金,因为这是一个极其资本密集型的业务,”他指的是通用人工智能。
“The infrastructure build-out is unprecedented,” said Mike Liberatore, business finance officer at OpenAI. “There’s no playbook that shows you how you go from zero to AGI and raise money through traditional means, given it’s a very capital-intensive business,” he said, referring to artificial general intelligence.
因此,该行业已借鉴项目融资和结构化融资的机制。通过设立特殊目的载体来隔离每笔交易的风险,发行人基于交易本身的优劣和客户质量发行债务,通常使其不计入企业资产负债表。
Consequently, the industry has adapted mechanisms from project and structured finance. By creating special purpose vehicles to ring-fence each deal, issuers raise debt based on a transaction’s merits and the quality of the customer, often keeping it off corporate balance sheets.
特殊目的载体(SPV)正是借钱购买并持有这些芯片的实体。债务由预期客户产生的现金流作为支撑,这些现金流用于支付利息,并在一段时间内全额偿还债务,同时还有芯片本身的价值作为担保。
The SPV is what borrows money to buy and own the chips. The debt is backed by the cash flow from the intended customer, which covers interest payments and fully pays down the debt over time, and the value of the chips themselves.
通过将债务期限与芯片预计五到六年的折旧周期相匹配,贷款方得以规避硬件贬值带来的风险。
By aligning the debt’s maturity with the chips’ expected five-to-six-year depreciation schedule, lenders insulate themselves from risks that the hardware loses value.
目前出现了两种主要模式:一种是客户从SPV租用芯片,接入自身的技术栈;另一种是新型云服务商(neoclouds)向客户出售算力,并利用债务帮助支付购买芯片的费用,以建设这一服务。
Two primary versions have emerged: deals where customers rent chips from an SPV to plug into their own technology stacks, and transactions where neoclouds sell computing capacity to customers and use debt to help pay for buying the chips to build out this service.
博通和英伟达更进一步,提出为数十亿美元级别的交易提供兜底,承诺在出现问题时支持贷款方。这使债务的信用评级与芯片制造商的投资级评级保持一致,从而降低SPV的借贷成本。
Broadcom and Nvidia are taking this a step further by offering to backstop multibillion-dollar deals, promising to support lenders if something goes wrong. This aligns the debt’s credit rating with the chipmaker’s investment-grade status, reducing the SPV’s borrowing costs.
博通的一位代表拒绝置评,英伟达的一位代表则没有发表评论。两家公司的高管此前曾表示,他们认为融资结构相关的风险有限。
A representative for Broadcom declined to comment and a representative for Nvidia didn’t have a comment. Their executives have previously said they consider risks around the funding structure to be limited.
投资级评级对于获取最大的资本池——尤其是保险资金——至关重要。
An investment-grade rating is vital to tapping the largest pools of capital — particularly insurance money.
阿波罗全球管理公司全球发起业务主管克里斯·埃德森表示,数字基础设施融资的规模超出了传统公开债务市场所能提供的范围,需要项目融资、私募配售、保险和商业房地产等市场的参与。
The scale of digital infrastructure financing exceeds what traditional public debt markets can supply, demanding involvement from markets such as project finance, private placements, insurance and commercial real estate, said Apollo Global Management Inc.’s global head of origination Chris Edson.
他说:“我们一直专注于高等级机会,这些机会的风险通过抵押担保、摊销、极低甚至不存在的剩余风险或续约风险、多元化以及高等级承购方来加以缓解。”
“We have been focused on high-grade opportunities where risks are mitigated through collateral security, amortization, little to no residual risk or renewal risk, diversification and high-grade off-takers,” he said.
评级为垃圾级的CoreWeave毫不掩饰其希望获得投资级评级的愿望。该公司成立于2017年,最初是一家加密货币矿企,后来利用其在GPU方面的经验迅速转向销售AI算力。随着这家科技巨头寻求获得更多GPU以支持其合作伙伴OpenAI,微软成为CoreWeave最大的客户。
Junk-rated CoreWeave, which has made no secret of its desire to become investment grade, was founded in 2017 as a crypto miner before leveraging its GPU experience to quickly pivot to selling AI processing power. Microsoft became CoreWeave’s largest customer as the tech giant sought access to additional GPUs to support its partner OpenAI.
为了支付芯片费用,CoreWeave的创始人借鉴了以往在大宗商品领域的经验。他们套用了液化天然气等市场的模式:客户先签署合同,然后开发商利用这些协议获得债务融资以建设设施。
To pay for the chips, CoreWeave’s founders drew on past experience in commodities. They adapted a model from markets like liquefied natural gas, where customers sign contracts first, then developers use those agreements to secure debt to build facilities.
2023年的第一笔债务交易由与微软的合同作为支撑,CoreWeave不得不以高达十几的利率借款。
That first 2023 debt deal was backed by contracts with Microsoft, and CoreWeave had to pay up to borrow at a rate in the mid-teens.
“这是我一生中做过的最具挑战性的尽职调查,”CoreWeave联合创始人布兰宁·麦克比回忆道,他还描述了黑石集团向该公司提出的问题。
“It was the most challenging diligence I’ve ever done in my life,” recounted CoreWeave co-founder Brannin McBee, who also described the questions Blackstone had asked the company.
随着CoreWeave签下后续客户,它从私募信贷交易转向成本更低的银行融资。CoreWeave首次尝到投资级待遇是在3月,当时它筹集了一笔85亿美元的债务方案,由Meta的合同作为支撑。华尔街将该风险视为与Meta的高信用评级相当,而非CoreWeave的垃圾级,从而将借款成本降至约6%。
As CoreWeave signed subsequent customers, it shifted from private credit deals to cheaper bank facilities. CoreWeave’s first taste of investment grade came in March, when it raised an $8.5 billion debt package backed by Meta contracts. Wall Street viewed the risk in line with Meta’s high credit rating rather than CoreWeave’s junk grade, slicing borrowing costs to roughly 6%.
其他人也效仿了CoreWeave的做法。去年,当埃隆·马斯克的xAI需要英伟达芯片来充实其Colossus 2数据中心时,它通过一个特殊目的载体筹集资金,其中包括由Valor Equity Partners领投的股权投资。阿波罗为该交易提供了近110亿美元的债务。
Others have followed the CoreWeave playbook. Last year, when Elon Musk’s xAI needed Nvidia chips to stock its Colossus 2 data center, it raised money through an SPV that included an equity investment led by Valor Equity Partners. Apollo provided nearly $11 billion of debt for the transaction.
阿波罗和黑石集团最近完成了一笔名为Big Sky的350亿美元债务交易,以支持Anthropic。这是博通、阿波罗和黑石集团之间名为AI XPV的平台的首笔交易,该平台可为20吉瓦的容量提供融资——美国银行策略师估计,到2029年中期,这可能需要在背后支持2350亿美元的债务。
Apollo and Blackstone recently did a $35 billion debt deal called Big Sky to support Anthropic. This was the first transaction of a platform between Broadcom, Apollo and Blackstone called AI XPV that could finance 20 gigawatts of capacity — which Bank of America Corp. strategists estimate may require $235 billion of backstopped debt by mid-2029.
为筹集购买芯片的债务,设立了一个特殊融资实体,Anthropic 将租用这些芯片。博通提供了兜底保障,即如果 Anthropic 违约,这些芯片将被重新租赁或出售以偿还剩余债务,芯片制造商将承担任何缺口。
A special financing entity was created to raise the debt to buy the chips, which Anthropic would lease. Broadcom provided a backstop, meaning if Anthropic defaults, the chips are re-leased or sold to repay the remaining debt, with the chipmaker covering any shortfall.
这项支持使该融资工具的两个博通支持的优先级债券获得了投资级评级。其中最大的一部分支付 5.75% 的利率——比 Anthropic 作为一家未评级的私营公司所能获得的更便宜——而风险更高的 45 亿美元次级债券定价为 8.5%。
This support led to an investment-grade rating for the vehicle’s two Broadcom-backed senior tranches. The largest of these pieces pays a 5.75% interest rate — cheaper than Anthropic could get as an unrated, private company — while the riskier $4.5 billion junior tranche priced at 8.5%.
“该行业可能面临许多风险,但有些融资结构比其他结构更能缓解这些风险,”L&G——资产管理公司美国分部另类债务主管 Ross McAdam 表示。
“The sector can have many risks, but some financing structures mitigate those risks more than others,” said Ross McAdam, head of alternative debt at L&G — Asset Management, America.
八月,英伟达组建了一个由 Apollo、Blackstone、BlackRock Inc.、Brookfield Asset Management、KKR & Co. 和 Goldman Sachs Group Inc. 组成的强大联盟,为 AI 基础设施寻找融资,英伟达将为其中最高达 25% 的机会提供兜底保障。
In August, Nvidia assembled a powerhouse coalition of Apollo, Blackstone, BlackRock Inc., Brookfield Asset Management, KKR & Co. and Goldman Sachs Group Inc. to source financing for AI infrastructure, of which it would backstop up to 25% of an opportunity.
彭博社本月报道,博通已就安排融资以帮助 OpenAI 购买双方共同开发的定制芯片进行了早期讨论。
Broadcom has held early discussions to arrange financing to help OpenAI purchase custom chips that the pair is developing together, Bloomberg reported this month.
不过,要实现真正的规模,行业需要从私人市场转向银团债务——即银行安排债券和贷款,在机构投资者之间出售和交易。今年早些时候,CoreWeave 成为首个进入银团市场进行芯片交易的公司:两笔获得投资者强劲需求的杠杆贷款。
To reach true scale, though, the industry needs to transition from private markets into syndicated debt — where banks arrange bonds and loans to sell and trade among institutional investors. Earlier this year, CoreWeave became the first to enter the syndicated markets with chip deals: two leveraged loans that met solid investor demand.
但最终目标是让这些特殊目的载体结构进入更大的投资级债券市场——这是世界上最深、最便宜的资本池之一。
But the ultimate goal is for these SPV structures to break into the much larger investment-grade bond market — one of the world’s deepest, cheapest pools of capital.
CoreWeave 的公司级垃圾债券最近受到打击,部分债券跌至每美元面值约 80 美分,收益率升至约 15%,因为投资者担心该公司不断扩大的债务。然而,市场将其两笔芯片支持的杠杆贷款视为独立部分。两笔贷款均略有下跌,但仍接近面值交易。
CoreWeave’s corporate-level junk bonds have taken a hit recently, with some sliding to around 80 cents on the dollar and pushing yields to roughly 15% as investors worry about the company’s expanding debt. However, the market views its two chip-backed leveraged loans as separate. Both dipped slightly but still trade near par.
在随抛售而发表的一份声明中,CoreWeave首席执行官迈克·因特拉特表示,构建一种新型科技公司意味着,市场有时需要处理关于AI采用的问题。
In a statement to Bloomberg following the selloff, CoreWeave Chief Executive Officer Mike Intrator said building a new type of technology company means there are moments where the market has to work through questions about AI adoption.
“这种审查很重要,但同样重要的是认识到,各公司拥有不同的技术、客户承诺、融资结构和执行记录,”他说。“我们对自己的商业模式、技术、执行质量以及支撑我们财务引擎的不懈纪律充满信心。”随着资金涌入,贷款人正面临风险。由于大多数芯片交易都是私下交易,投资者无法轻易出售自己在将少数几家芯片制造商、云计算巨头和新兴云公司绑定在一起的债务交易中的头寸。这导致对一小群相互关联的参与者产生高度敞口。
“That scrutiny is important, but what’s also important is to recognize that companies have different technologies, customer commitments, financing structures and records of execution,” he said. “We’re confident in our business model, our technology, the quality of our execution, and the relentless discipline behind our financial engine.”As capital floods in, lenders are confronting risks. Because most chip deals are private transactions, investors have no easy way to sell their positions in debt deals that have bound a small number of chipmakers, cloud computing giants and neocloud firms together. This creates heavy exposure to a small group of interconnected players.
“大的会变得更大,”Magnetar公司管理合伙人兼另类信贷和固定收益全球主管戴夫·斯奈德曼表示。“现有企业很可能会获胜,因为只有他们才能获得资金。”贷款人面临的另一个风险是,客户合同究竟有多严密。文件保护在实践中可能不如预期那样坚不可摧——就像在风险更高的信贷市场中那样。如果AI回报令人失望,科技公司可能会利用其影响力,迫使贷款人和新兴云公司重新谈判交易或租赁。
“The big are going to get bigger,” said Dave Snyderman, managing partner and global head of alternative credit and fixed income at Magnetar. “The incumbents are likely going to win because they’re the only ones who are going to have access to capital.”Another risk for lenders is how airtight the customer contracts really are. Document protections may prove less ironclad in practice — as they have in riskier credit markets. If AI returns disappoint, tech firms could use their clout to force lenders and neocloud firms into renegotiating deals or leases.
每个人都认为这些合同严密且不可打破,但卡莱尔集团(Carlyle Group Inc.)资产支持融资部门负责人阿希尔·班萨尔(Akhil Bansal)表示:“我关注的是实际因素。”他说:“如果有七家公司基本上为GPU提供所有信贷支持,那么谁拥有议价权?”这种复杂性让一些投资者持观望态度。纽维恩(Nuveen)私募固定收益部门负责人劳拉·帕罗特(Laura Parrott)表示:“这是一种新型结构。”
Everyone is assuming these contracts are tight and unbreakable, but “I look at the practical element,” said Akhil Bansal, head of asset-backed finance at Carlyle Group Inc. “If you have seven firms that are basically providing all the credit support for the GPUs, who’s got the leverage?”The complexity is keeping some investors on the sidelines. “This is a novel structure,” said Laura Parrott, head of private fixed income at Nuveen.
她补充说:“我们还没有看到,如果出现某种中断,这种结构会如何运作。”她表示,在市场进一步发展之前,她将暂缓向大型投资级芯片交易提供贷款。
“We haven’t seen how that plays out if there is some sort of disruption,” she said, adding that she’s holding off on lending to big investment-grade-rated chip deals until the market develops more.
随着芯片市场的演变,用于融资硬件的机制也将随之变化。早期研究和实际使用表明,芯片的寿命比目前的会计处理所暗示的更长,这将使芯片更容易融资。
As the chip market evolves, so too will the mechanisms used to finance the hardware. Early research and real-world usage so far are showing the chips are lasting longer than current accounting treatment suggests, which would make them easier to finance.
美国银行(Bank of America)全球基础设施与可持续融资部门负责人、全球资本解决方案团队联合负责人卡伦·方(Karen Fang)表示,新旧汽车的凯利蓝皮书(Kelley Blue Book)的等价物可能会为半导体出现,从而推动芯片交易和对冲的发展。
The equivalent of the Kelley Blue Book for new and used cars could emerge for semiconductors, enabling chip trading and hedging to develop, said Karen Fang, global head of infrastructure and sustainable finance, and co-head of the global capital solutions teams, at Bank of America.
她说:“当我们拥有足够的芯片数据历史和业绩记录时,你将开始看到一个更加强劲的租赁市场。”
“When we get to a point where we have enough data history and track record on the chips, then you’re going to start seeing a much more robust leasing market,” she said.
一旦OpenAI和Anthropic上市,为它们筹集芯片债务可能会变得更简单,尤其是如果它们能获得投资级评级并自行组建交易。
And raising chip debt could get simpler for OpenAI and Anthropic once they do go public, especially if they can win investment-grade ratings and put together deals on their own.
英伟达(Nvidia)、黑石(Blackstone)及其华尔街同行的最终目标,是将计算能力单位转变为一种资产类别,让全球的人们能够“融资算力,因为我们理解算力的经济价值”,黑石的沃森(Watson)表示。
The ultimate endgame for Nvidia, Blackstone and their Wall Street peers is to turn a unit of computing power into an asset class, where people globally can “finance compute because we understand the economic value of the compute,” Blackstone’s Watson said.