财报季已经来临,华尔街预计标普500指数中与人工智能无关的公司将赚取巨额利润。如果这表明盈利增长正在扩大,那将是个好消息,但实际上该指标正处于由总统唐纳德·特朗普与伊朗的战争所造成的皮洛斯式繁荣中。这是我们日后要付出代价的提振。
Earnings season is upon us, and Wall Street expects companies in the S&P 500 Index that aren’t tied to artificial intelligence to rake in profits. That would be good news if it pointed to a broadening out of earnings growth, but instead the gauge is in a Pyrrhic boom created by President Donald Trump’s war with Iran. It’s a bump that we’ll pay for later.
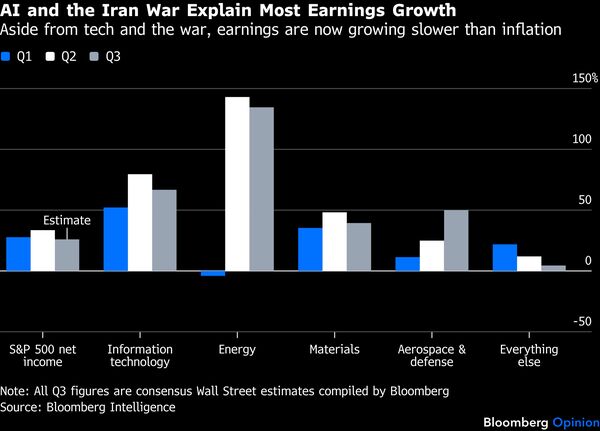
预计能源行业第三季度净利润将较去年同期飙升约135%,而航空航天和国防行业的利润可能会跃升约50%。再加上材料板块(包括受战争影响的石化产品、化肥和金属)预计39%的飙升,你就解释了绝大部分非人工智能领域的强劲表现。
Energy industry net income is expected to soar about 135% in the third quarter from a year earlier, while the aerospace and defense industry may see profits jump by about 50%. Add to that the projected 39% jump in the materials sector — including war-impacted petrochemicals, fertilizers and metals — and you’ve explained away most of the non-AI strength.
只要战争继续,它可能会继续成为一些特殊利润的来源,但代价是什么?标普500指数经调整后的“其他所有”类别收益(即那些与战争或人工智能无关的收益)预计在上一季度仅增长了约4.5%,勉强超过3.7%的通货膨胀率。
The war may continue to be a source of some idiosyncratic profits for as long as it continues, but at what cost? The “everything else” category of adjusted S&P 500 earnings, those not linked to the war or AI, is expected to have grown just about 4.5% last quarter, barely outstripping the 3.7% pace of inflation.
战争收益本质上是寄生的。经济上的权衡是更高的燃料价格和借贷成本,这会阻碍消费者信心并挤占其他类型的消费。由此产生的选民沮丧情绪可能会让共和党人在下个月的中期选举中失去对众议院和参议院的控制权。
War earnings are inherently parasitic. The economic tradeoff is higher fuel prices and borrowing costs, which hamper consumer sentiment and crowd out other types of consumption. The resultant voter frustration may cost Republicans control of the House and Senate in next month’s midterm elections.
我们在2022年和2023年初短暂的盈利衰退中尝到了这种滋味,当时人工智能尚未成为主导市场叙事的因素,还没有取代俄罗斯对乌克兰的入侵以及美联储的加息。人工智能仍然是市场的主要支撑力量,但在包括特朗普2025年关税在内的多重经济意外的重压下,消费经济变得更加脆弱。在过去六个月里,通货膨胀率超过了每小时收入的增长,导致低收入消费者不得不累积信用卡债务或动用储蓄来维持消费。
We got a taste of this in the short-lived earnings recession of 2022 and early 2023, before AI became the dominant market narrative, displacing Russia’s invasion of Ukraine and the Federal Reserve’s interest-rate hikes. AI is still a major source of market ballast, but the consumer economy has grown shakier under the weight of repeated economic surprises, including Trump’s 2025 tariffs. Inflation has outstripped growth in hourly earnings for the past six months, leaving lower-income consumers to rack up credit card debt or cut into savings to finance their spending.
历史表明,能源冲击的负面影响通常需要一段时间才能在整体收益和产出中显现出来。消费者和企业通常可以暂时无视较高的燃料价格,但当冲突拖延很长时间时,他们的缓冲就会耗尽。达拉斯联邦储备银行的一篇论文发现,工业生产通常会在大约10个月的滞后时间内下降,其中家用电器、家具和汽车是受打击最严重的行业之一。在这些行业中,只有机动车辆的购买在早期阶段出现明显的疲软,但最终缺乏需求往往会打击整个非石油经济。
History shows that the deleterious effects of energy shocks are usually somewhat slow to manifest themselves in aggregate earnings and output. Consumers and businesses can typically brush off higher fuel prices for a while, but they run out of cushion when conflicts drag on for a long period. A Federal Reserve Bank of Dallas paper found that industrial production typically declines with a delay of about 10 months, with household appliances, furniture and automobiles among the sectors hit the hardest. Of these, only purchases of motor vehicles turn noticeably sluggish in the early days, but a lack of demand tends to hit the entire non-petroleum economy eventually.
这一次,某些行业的萎缩可能来得很早,就在特朗普加入以色列对伊朗空袭大约半年之后。标普500可选消费板块预计本季度仅增长1.8%,必需消费品板块可能增长约1.3%。房地产基本持平,医疗保健收益继续处于收缩状态。
The retreat may have come early in some sectors this time around, only about a half year after Trump joined Israeli airstrikes on Iran. The S&P 500 consumer discretionary sector is expected to see just 1.8% growth this quarter, and consumer staples probably grew about 1.3%. Real estate was essentially flat, and health care earnings remain in contraction.
展望未来,如果通胀不尽快消退,包括住房和汽车在内的对利率敏感的行业可能会变得更糟。全美住宅建筑商协会与富国银行合作编制的住房市场景气指数在上一周发布的一份报告中降至2012年6月以来的最低点。如果这些不是与战争相关的拖累的早期迹象,那就表明需求在伊朗事件之前就已经在水面下减弱了。
Going forward, rate-sensitive sectors including housing and autos will probably get worse if inflation doesn’t abate soon. The National Association of Home Builders/Wells Fargo gauge of housing market conditions fell to the lowest since June 2012 in a report published last week. If these aren’t early signs of a war-related drag, then they show that demand was weakening under the surface even before Iran.
人工智能难道不能帮助经济挺过这一切吗?分析师预计,标普500信息技术板块本季度净利润将增长67%,从而将整个指数的盈利增长推高至26%!人工智能繁荣不仅通过数据中心深入到其他行业——包括公用事业和工业——而且自2022年底(ChatGPT发布时)以来,它还促使家庭净资产增加了约52万亿美元。如果这种状况能够维持下去,这反过来可以继续缓冲消费。
Won’t AI help the economy power through all of this? Analysts expect net income for the S&P 500 information technology sector to grow 67% this quarter, bringing index-wide earnings growth to 26%! Not only does the AI boom reach deep into other sectors through data centers — including utilities and industrials — but it has contributed to an increase of about $52 trillion in household net worth since the end of 2022, when ChatGPT was released. That, in turn, can continue to cushion consumption, if it holds.
没有人能够可靠地预测像人工智能这样的大规模繁荣何时到来,但亿万富翁肯·格里芬上周与桥水基金创始人雷·达里奥一起暗示,我们正处于一个泡沫之中。固定收益投资者正突然要求风险较高的人工智能相关发行人(包括CoreWeave公司)的债券提供高得多的收益率。无论你对末日论作何感想,毫无疑问,狭窄的市场广度增加了动荡的几率。毕竟,很大一部分经济和市场现在都依赖于少数几家超大规模企业证明人工智能具有盈利性,并值得在更多芯片和基础设施上进行进一步投资。
No one can reliably time a massive boom like AI, but billionaire Ken Griffin last week joined Bridgewater founder Ray Dalio in suggesting that we were in a bubble. Fixed-income investors are suddenly demanding much higher yields on debt from riskier AI-related issuers including CoreWeave Inc. Whatever you think of the doomer thesis, there’s no question that narrow breadth raises the odds of turbulence. After all, so much of the economy and market now rest on the ability of a few hyperscalers to prove AI is profitable and worth further investments in more chips and infrastructure.
这就是为什么近期能源和材料收益的飙升是一场虚假胜利。其代价是给那些本已难以为继的家庭增加了更大的压力,并削弱了可能从此时起进一步走软的消费者盈利基础,如果格里芬和达里奥是正确的,这将只剩下一层薄如蝉翼的缓冲来支撑市场。
That’s why the recent jump in energy and materials earnings is a false victory. The price is increased pressure on households that were already running out of runway and a consumer earnings base that will probably soften further from here, leaving a razor-thin cushion to buoy the market if Griffin and Dalio are right.