根据贝莱德(BlackRock)的里克·里德(Rick Rieder)的说法,由人工智能推动的债务繁荣正在创造多年来最具吸引力的固定收益机会,其吸引力超过了长期美国国债。
The AI-driven debt boom is creating some of the most attractive fixed-income opportunities in years, eclipsing the appeal of long-dated US Treasuries, according to BlackRock’s Rick Rieder.
“我从未见过类似的情况,无论是债务市场还是股票市场涌入的融资规模,”该公司全球固定收益首席投资官在接受彭博电视台采访时表示。“我职业生涯的大部分时间都在等待7%的收益率。”他指出,GPU、数据中心和其他人工智能基础设施融资的激增尤其引人注目。里德偏好成熟公司的有担保债务以及产生现金流的资产,同时也认为半导体和计算领域的股票估值合理。
“I’ve never seen anything like it in terms of the size of the financing that’s coming in both debt markets, equity markets,” the firm’s chief investment officer for global fixed income said in a Bloomberg TV interview. “I’ve spent much of my career waiting for 7% yields.”The surge in financing for GPUs, data centers and other AI infrastructure is particularly compelling, he noted. Rieder prefers secured debt from established companies and assets that generate cash flow, while also seeing reasonable equity valuations in semiconductors and computing.
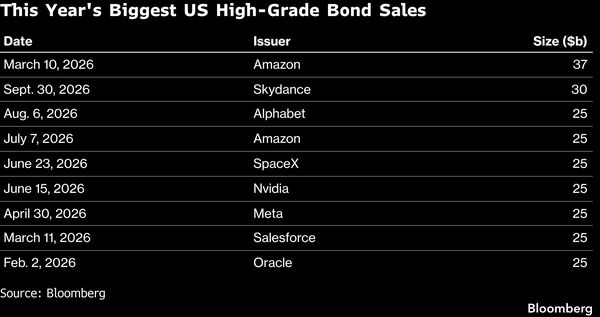
人工智能行业正在经历一场大规模的资本支出周期,由超大规模云服务商(hyperscalers)推动,他们可能每年在一项可能重塑全球经济的技术上花费高达1万亿美元。这一扩张已经使全球高等级人工智能相关融资在2026年超过3000亿美元,大约是2025年全年总额的三倍。
The AI sector is undergoing a massive capital expenditure cycle, driven by hyperscalers potentially spending up to $1 trillion annually in a technology that may reshape the global economy. This expansion has already driven high-grade AI-related funding past $300 billion globally in 2026, roughly triple the total for all of 2025.
“这是我见过的最令人兴奋的投资时期之一,”他说。“我整个周末都在研究这些交易中的一些,并以相当显著的方式参与了其中一些交易。”里德表示,新发行债券的巨大规模相比过去改善了定价,为投资者提供了更具吸引力的入场点。
“This is one of the most exciting investment periods I’ve ever seen,” he said. “I spent the entire weekend looking at some of these transactions, participating in a pretty significant way in some of these transactions.”The sheer scale of new issuance has improved pricing compared to the past, offering investors more attractive entry points, Rieder said.
相比之下,10年期美国国债在固定收益领域“已退居次要”,让位于其他机会。即使其收益率超过5%,里德也认为这一基准越来越不像核心投资,而越来越像市场风向标,通常针对股票。
By contrast, the 10-year Treasury has “taken a backseat” to other opportunities in fixed income. Even with its yield above 5%, Rieder views the benchmark as increasingly less as a core investment and increasingly as a market barometer, often for equities.
相反,他说,投资者可以在短期、单A级投资组合中获得约7%的收益率,同时避免与长期政府债务相关的久期风险。
Instead, investors can earn about 7% in short-dated, single-A-rated portfolios while avoiding the duration risk associated with longer-term government debt, he said.
在美国以外,里德认为日本长期利率存在吸引人的机会,新兴市场收益率也颇具吸引力,但他警告称,包括巴西大选在内的政治事件值得警惕。
Outside the US, Rieder sees attractive opportunities in Japan’s long-end rates and compelling yields in emerging markets, though he warned that political events, including Brazil’s elections, warrant caution.
他对法国债券保持警惕,预计波动将持续,且对人民币计价债务的敞口有限,因为其“相对于其他机会缺乏吸引力”。
He remains wary of French bonds, expecting ongoing volatility, and has limited exposure to yuan-denominated debt because it “lacks attractiveness relative to other opportunities.”