本周英国预算案将成为该国股市的一大考验,正值英国市场重新获得全球投资者青睐之际。
This week’s UK budget looms as a major test for the country’s stocks, just as the market gains renewed appeal among global investors.
富时100指数和富时250指数今年以来均跑赢大盘,分别上涨8%和9%,优于欧洲斯托克50指数5.6%的涨幅。
Both the FTSE 100 and the FTSE 250 have outperformed this year, up 8% and 9%, respectively, and beating the 5.6% advance in the Euro Stoxx 50 index.
英国大盘股本月表现尤为强劲,得益于能源、日用消费品和医疗保健板块的强势,这三大板块约占基准指数的40%。与此同时,低估值和更稳定的英国国债收益率提振了中盘股。但风险很高,周三预算案公布时,债券市场警惕者将权衡潜在的增税或消费者支持措施与政府有限的财政空间。
UK large caps have been particularly on the front foot this month, powered by strength in energy, staples and healthcare, which make up about 40% of the benchmark. Meanwhile, cheap valuations and more stable gilt yields have boosted mid-caps. But the stakes are high heading into Wednesday’s budget, when bond vigilantes will evaluate potential tax hikes or consumer support measures against the government’s limited fiscal headroom.
花旗集团策略师Beata Manthey领导的团队表示:“我们认为富时100指数存在战略性跑赢大盘的理由,因为该市场可作为有效的地缘政治对冲工具。不过,从中长期来看,我们在全球范围内仍维持对英国市场的低配评级。”该行经济学家预计预算案将对市场友好,并将优先考虑财政可信度。另一方面,花旗行业分析师认为,不同行业组的风险回报各异。例如,英国公用事业面临不成比例的下行风险,因为政府对能源负担能力的关注可能带来市场可能低估的结构性改革。
“We see reasons for tactical outperformance for the FTSE 100, as the market serves as an effective geopolitical hedge,” said Citigroup Inc. strategists led by Beata Manthey. “We nevertheless remain underweight UK globally over medium term.”The bank’s economists expect a market-friendly budget that will prioritize fiscal credibility. Citi’s sector analysts, on the other hand, see varied risk-reward across industry groups. UK utilities, for one, face disproportionate downside risk, as the government’s focus on energy affordability could bring structural reforms that the market may be under-appreciating.
花旗分析师表示,英国房屋建筑商处于新推出的“Your First Home”(你的首套住房)计划可能带来的需求提振,与英国国债收益率居高不下导致的可负担性逆风之间。对于银行股而言,预算案可能成为一个潜在的出清事件。对贷款机构加征税费的增加在很大程度上已被定价,而英国国债市场对预算案的反应可以说是该板块估值的更大驱动因素。
UK homebuilders sit between a potential demand boost from the new “Your First Home” program and affordability headwinds from elevated gilt yields, Citi analysts said. For banks, the budget could be a potential clearing event. An increase in the tax surcharge on lenders looks largely priced in, while the gilt market’s reaction to the budget is arguably a bigger driver of sector valuations, they said.
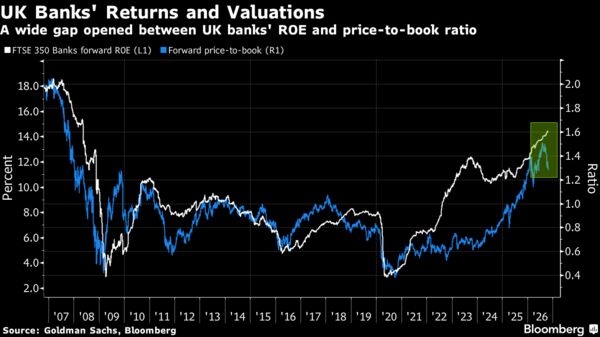
基于账面价值的英国银行估值与其股本回报率之间已出现显著差距,这一差距比欧洲其他地区更为明显。这表明,尽管英国银行的股本回报率较高,且欧洲大陆的主权债券利差在上升,但投资者很可能对其施加了更高的风险溢价。
UK bank valuations based on book value have opened a significant gap to their return on equity, a gap that’s more pronounced than it is in the rest of Europe. That’s a sign that investors are likely applying a greater risk premium to British banks, despite their higher ROE and rising sovereign spreads on the continent.
英国银行已在25%的公司税基础上额外缴纳3%的银行附加税,还需缴纳银行税。据高盛集团分析师称,英国银行附加税每提高一个百分点,将对巴克莱银行2028年净利润预期造成约0.5%的拖累,对劳埃德银行集团和国民西敏寺银行集团则略超1%。“提高银行附加税将产生重大影响,”以莎伦·贝尔为首的高盛策略师表示。“预算案公布后能否实现重新估值,关键在于英国特有风险溢价的下降以及对英国经济信心的增强。”
UK lenders already pay a 3% banking surcharge on top of the 25% corporation tax, as well as a bank levy. According to Goldman Sachs Group Inc. analysts, each percentage point increase in the UK banking surcharge would equate to a drag of about 0.5% on 2028 net income estimates for Barclays Plc, and slightly over 1% for Lloyds Banking Group Plc and NatWest Group Plc. “An increase in the bank surcharge would be significant,” said Goldman strategists led by Sharon Bell. “For there to be a re-rating post the budget, the key will be a reduction in UK-specific risk premium and a rise in confidence about the UK economy.”
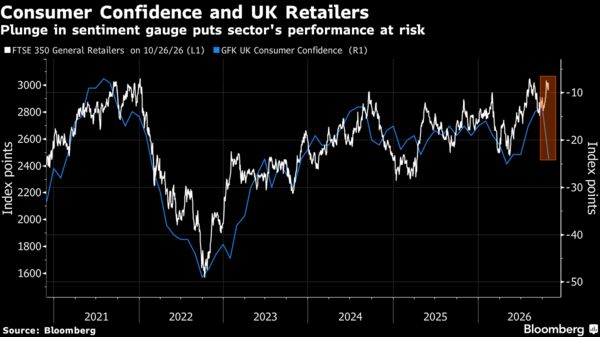
一旦预算案尘埃落定,下一个重大风险事件就是英国央行11月5日的利率决定。市场几乎已经完全消化了一次加息,这是预计到明年7月底之前四次加息中的第一次。这样的连续加息将对消费者造成严重打击,并推高许多家庭的抵押贷款成本。难怪本月英国消费者信心的降幅创下自新冠疫情以来最大。这使零售业面临风险,尤其是如果预算案未能提供实质性支持。
Once the budget is out of the way, the next major risk event is the Bank of England rate decision on Nov. 5. An interest-rate increase is almost fully priced in, the first of four expected by the end of July next year. A series of hikes like that would be a serious blow to consumers and raise mortgage costs for many households. It’s no wonder then that UK consumer confidence this month fell the most since the Covid pandemic. That puts the retail sector at risk, especially if the budget fails to provide meaningful support.
英国市场得益于10月份全球投资者仓位的转变,其特点是转向更具防御性的资产。根据本月早些时候公布的美国银行基金经理调查,投资者目前对英国股票净低配26%,而9月份为净低配35%。这仍比长期均值低0.8个标准差,意味着仍有增加敞口的空间。
The UK market has benefited from a flip in global investor positioning in October, characterized by a move to more defensive assets. According to the Bank of America Corp. fund manager survey out earlier this month, investors are now net 26% underweight UK equities, compared with a net 35% underweight in September. That is still 0.8 of a standard deviation below the long-term average, leaving scope for more exposure.
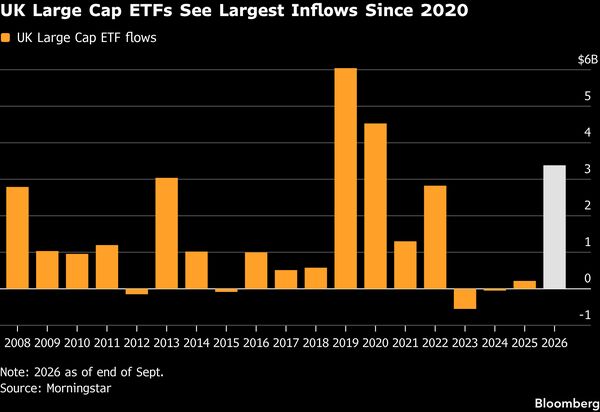
与此同时,根据晨星数据,英国大盘股交易所交易基金(ETF)在2026年吸引了约34亿美元的预估净流入,创下自2020年以来最强年度总额。对富时100指数的重新信任投票,部分反映了投资者渴望接触伦敦市场一些最强劲的标的,如汇丰控股、英国石油、壳牌和劳斯莱斯控股。
Meanwhile, UK large-cap exchange-traded funds have attracted $3.4 billion in estimated net inflows in 2026, their strongest annual total since 2020, according to Morningstar data. The renewed vote of confidence in the FTSE 100 partly reflects investor appetite for exposure to some of the London market’s strongest names, like HSBC Holdings Plc, BP Plc, Shell Plc and Rolls-Royce Holdings Plc.
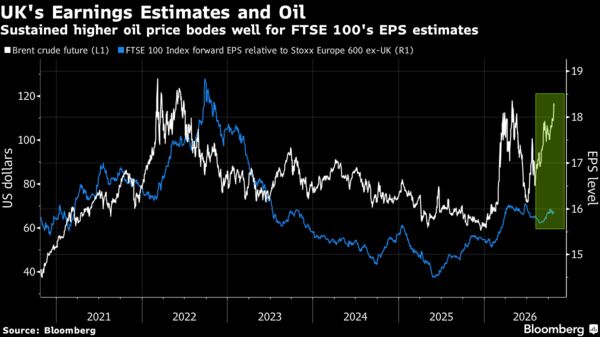
“投资者正以全新眼光审视英国,”晨星分析师迈克尔·伯恩表示。“被动基金的资金流入通常跟随表现,但也反映出投资者希望从美国大盘科技股中分散配置,拓宽股票敞口。”对英国大盘股前景的主要潜在威胁之一是油价。伊朗战争使布伦特原油价格维持在每桶100美元以上,而能源板块正推动富时100指数的大部分盈利增长。随着分析师预期明年油价下跌,每股收益增幅预计将从2026年的30%降至2027年的仅5%。
“Investors are looking at the UK with fresh eyes,” said Michael Born, an analyst at Morningstar. “Flows into passive funds typically follow performance, but they also reflect investors looking to diversify away from US mega-cap technology and broaden their equity exposure.”One of the main potential threats to the outlook for UK large caps is oil prices. The war in Iran has kept Brent prices above $100 a barrel and it’s the energy sector that’s driving most of the earnings growth for the FTSE 100. With analysts pricing lower oil prices next year, earnings-per-share increases are projected to fall to just 5% in 2027, compared with 30% in 2026.
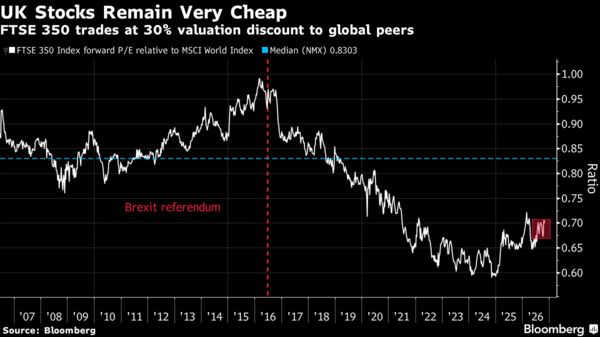
话虽如此,估值仍然不算昂贵,可能为大盘股和中盘股提供缓冲。富时350指数相较全球股票提供30%的折价,仍是英国股市的主要吸引力之一。它不仅是分散敞口的低成本方式,也是欧洲并购最肥沃的土壤,尤其是在中盘股方面。
That said, valuations remain undemanding and may provide a cushion for large and mid-caps alike. The FTSE 350 offers a 30% discount to global stocks and remains among the main attractions of the UK stock market. Not only is it a cheap way of diversifying exposure, but it’s also the most fertile ground for M&A in Europe, especially when it comes to mid-caps.
“人们普遍预期经济政策相对稳定且预算对市场友好,这限制了富时100指数的上行空间,特别是如果此类预算主要体现为英镑走强时,”包括邓肯·托姆斯在内的汇丰策略师表示。他们对英国整体维持中性立场。“相反,英国中盘股看起来更具吸引力。持续向好的英国经济活动意外正推动富时250指数近几个月跑赢大盘,我们认为这种趋势可持续。”
“Widespread expectations of relatively stable economic policy and a market-friendly budget limit the upside for the FTSE 100, particularly if such a budget were to manifest itself primarily in a stronger pound,” said HSBC strategists including Duncan Toms. They retained a neutral stance overall on the UK. “Instead, UK mid-caps look more attractive. Persistently positive UK activity surprises are driving FTSE 250 outperformance in recent months, which we think can continue.”