债市投资者越来越怀疑,国会山可能出现的僵局,是否能像过去几十年那样,缓解他们对美国财政走势的担忧。
Bond investors are growing skeptical that the potential return of gridlock on Capitol Hill will ease their worries about the US fiscal trajectory the way it has for decades.
民调显示,11月3日的美国中期选举很可能再次出现这种政治结果。民主党预计将从共和党手中夺取国会至少一个议院的控制权,但不足以获得足够席位来推翻唐纳德·特朗普总统的否决权。
Polls suggest that political outcome is likely once again from US midterm elections on Nov. 3. Democrats are projected to wrest control of at least one chamber of Congress from the Republican Party, while falling short of gaining enough seats to override President Donald Trump’s veto power.
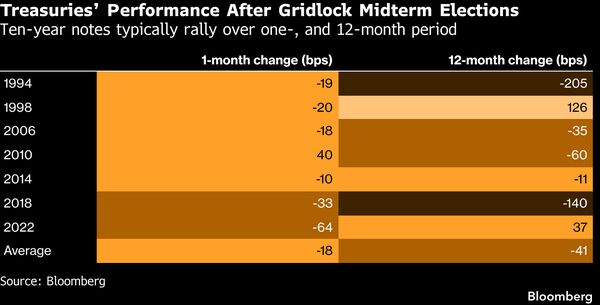
自20世纪90年代中期以来,国会或政府分裂往往是国债的利好因素。彭博社汇编的数据显示,在产生此类结果的中期选举后,基准10年期国债收益率平均在一个月和12个月后更低。由于这种局面使重大支出立法更难通过,它曾被视为遏制政府支出、控制膨胀预算赤字的可靠方式。
Since the mid-1990s, a split Congress or government has often been a bullish recipe for Treasuries. Benchmark 10-year yields have been lower on average one and 12 months after midterms that produced such a result, Bloomberg-compiled data show. By making it harder to pass major spending legislation, that setup was seen as a sure way to rein in government spending and contain swelling budget deficits.
但这一次,投资者怀疑立法瘫痪是否足以将收益率从近四分之一世纪以来的最高水平附近拉下来。财政挑战已变得过于艰巨:仅仅避免大规模新支出或减税举措已不再足够——政客们现在需要采取增加收入或削减支出的措施,才能为投资者提供更具建设性的财政叙事。
This time, investors doubt that legislative paralysis will be enough to bring yields down from around the highest in nearly a quarter century. The fiscal challenge has just become too daunting: Merely refraining from big new spending or tax-cut initiatives is no longer enough — politicians now would need to take steps to raise revenue or reduce outlays to offer investors a more constructive fiscal narrative.
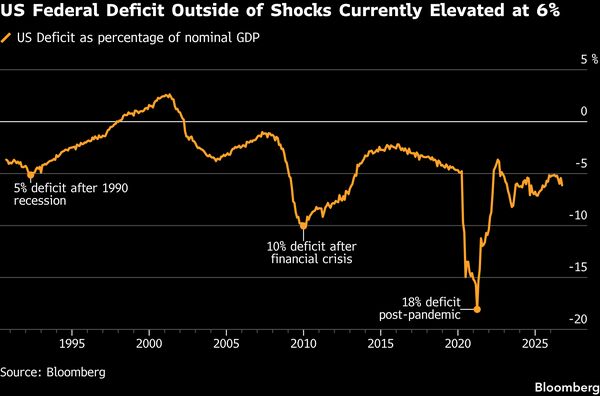
联邦预算缺口约占经济规模的6%,在非衰退时期很少出现如此之大的缺口。而且,在公共债务超过32万亿美元、利率上升的背景下,年度净利息成本已攀升至超过1万亿美元的创纪录水平,超过了国防预算。
The federal budget gap, at roughly 6% of the economy, has rarely been this large outside of a recession. And with debt held by the public surpassing $32 trillion, at a time of rising interest rates, annual net interest costs have climbed to a record above $1 trillion, more than the defense budget.
“债券市场正在寻求某种政策行动,以控制支出和债务,”管理210亿美元资产的钻石山资本(Diamond Hill)投资组合经理亨利·宋(Henry Song)表示。“从这个角度看,两年的僵局未必是件好事,因为——如果你算算账——在未来两年里,如果什么都不做,你将不断增加债务。”宋表示,结论是“风险在于利率将上升”。“你还没有得到足够的补偿”来购买长期债券。
“The bond market is looking for some sort of policy action to get the spending and debt under control,” said Henry Song, a portfolio manager at Diamond Hill, which oversees $21 billion. “From that perspective, two years of impasse is not necessarily great because — if you just do the math — you’re going to keep adding more debt to it in the next two years by doing nothing.”The bottom line is “the risk is for rates to go higher,” Song said. “You’re not really getting compensated enough” to buy long-term bonds yet.
当然,中期选举后的债券表现也反映了当前的经济背景。例如,2022年,共和党赢得众议院控制权,而民主党在乔·拜登(Joe Biden)领导下保持参议院和白宫控制权,随后一个月10年期国债收益率下跌了超过半个百分点。随后,随着高通胀延长了美联储的加息周期,收益率在接下来的一年里上升。
Of course, the post-midterm bond performance also reflects the prevailing economic backdrop. In 2022, for example, when Republicans won control of the House as Democrats held the Senate and the White House under Joe Biden, the 10-year yield dropped more than a half-point in the subsequent month. It then rose over the following year as hot inflation extended the Federal Reserve’s cycle of interest-rate hikes.
下个月的选举正值债券市场艰难的一年,伊朗战争推高能源价格,助长通胀担忧,并促使美联储时隔三年首次加息。市场也在消化大量政府债务发行,这些债务正与为融资AI热潮而激增的企业债券销售竞争。
Next month’s election comes during a bruising year for bonds, with the Iran war boosting energy prices, fanning inflation concern and pushing the Fed to lift rates for the first time in three years. Markets are also absorbing a wall of government debt issuance, which is competing with surging corporate bond sales to finance the AI boom.
本月10年期国债利率接近5.4%,创下2002年以来的最高水平,推高了抵押贷款成本并抑制了房地产市场。投资者表示,除非国会控制住支出,否则政府债券拍卖可能会继续以高收益率成交。
Ten-year Treasury rates approached 5.4% this month, the highest since 2002, driving up mortgage costs and cooling the housing market. Investors say that unless Congress gets spending under control, government auctions will likely keep clearing at elevated yields.
“很奇怪,有人认为僵局对市场是件好事,因为过去也发生过这种情况,”DWS美洲固定收益部门负责人乔治·卡特兰博内(George Catrambone)表示。
“It’s odd that there’s some argument that gridlock is a good thing for markets, because that happened in the past,” said George Catrambone, head of fixed income at DWS Americas.
“明年国会会议失灵或出现更多政府停摆,本质上就是把这件事交给了债券市场,”他说。“考虑到利率已经大幅回升,明年若再次出现这种情况将是一件遗憾的事,因为我不确定经济能否承受。”华尔街有些人士并未准备好将中期选举视为推动固定收益市场走强的催化剂而将其排除在外。
“Having a dysfunctional congressional session next year or more government shutdowns is essentially putting this into the bond market’s hands,” he said. “Given how much rates have backed up, it would be a shame to have that repeated next year as I’m not sure the economy can handle it.”Some on Wall Street aren’t ready to write off the midterms as a catalyst for fixed-income strength.
除了阻碍支出法案,MUFG美国宏观策略主管乔治·贡萨尔维斯认为,民主党大胜可能会为明年加强对人工智能的监管留出空间。在他看来,这将支撑国债,因为这会打击股市、拖累经济并减少与人工智能相关的债券发行。债券市场上周因对人工智能公司前景的担忧而上涨,使10年期收益率在周末跌破5%。
In addition to stymieing spending bills, George Goncalves, head of US macro strategy at MUFG, sees scope for a Democratic wave to increase regulation around AI next year. In his view, that would support Treasuries because it would hurt stocks, slow the economy and reduce debt sales linked to AI. The bond market rallied last week on concerns over the outlook for AI companies, pulling the 10-year yield below 5% at week’s end.
不过,鉴于民调情况,至少在众议院方面,这种结果会令人意外,他也思考了一种对债券不利的情景:选举结果使支出持续流动。
And while it would be a surprise given the polling, at least for the House, he also pondered a bond-bearish scenario where the vote keeps spending flowing.
“如果共和党获胜并使财政扩张得以继续,这对债券来说可能更具挑战性,”贡萨尔维斯说。
“A Republican win could be more challenging for bonds if it enables continued fiscal expansion,” Goncalves said.
下个月市场还有另一个不确定因素,可能会扭曲中期选举后债券发出的信号。选举后的第二天,财政部将公布其季度再融资计划,该计划被视为为任何重大债务管理政策变化铺平道路。
There’s another wild card for the market next month, which may distort the signals from bonds following the midterms. The day after the election, the Treasury announces its quarterly refunding plans, which are seen as setting the stage for any substantial changes in debt-management policy.
分析人士推测,官员们可能会通过缩减长期债券拍卖规模、增加国库券销售等措施来帮助降低收益率。任何暗示这种转变即将到来的迹象,都可能有助于使国债收益率曲线变平,即长期收益率相对于短期利率下降。
Analysts have speculated officials might seek to help lower yields through steps such as shrinking longer-maturity auctions and increasing sales of T-bills. Any hint that shift is ahead may help flatten the Treasury curve, with long-dated yields falling relative to rates on shorter maturities.
这将模仿某些选举结果陷入僵局后出现的模式。TD证券策略师莫莉·布鲁克斯和根纳季·戈德伯格在一份报告中写道,选举后几周内,民主党控制国会、共和党人担任总统的组合,历史上曾导致收益率曲线平坦化,且主要由更长期限的债券带动。
That would mimic the pattern seen after certain episodes of gridlock election results. The combination of a Democratic Congress and a Republican president in the weeks after an election has historically seen the yield curve flatten led by longer maturities, TD Securities strategists Molly Brooks and Gennadiy Goldberg wrote in a note.
他们表示,僵局结果“应严格限制任何新的支出法案”。但即使出现这一结果,他们仍预计,2027财年的赤字将从5.9%上升至占国内生产总值的6.4%,因为支出政策实质性改变不太可能。
A gridlock outcome “should severely limit any new spending bills,” they said. But even with that result in November, they still expect the deficit to climb to 6.4% of gross domestic product for fiscal 2027 from 5.9% as substantive changes to spending policy would be unlikely.
SMBC美国利率策略主管约瑟夫·阿贝特表示,最终,国会人事更替可能导致投资者要求更高的收益率,而这种影响的大小可能取决于民主党获胜的程度。他说,更大的“蓝色席卷”可能会促使共和党人关注可负担性问题,并使他们更愿意接受民主党增加支出的提议。
Ultimately, turnover in Congress may lead investors to demand higher yields, and the size of that effect could depend on the extent of any Democratic gains, said Joseph Abate, head of US rates strategy at SMBC. A bigger “blue sweep” could lead Republicans to focus on affordability issues and make them more open to Democratic proposals to increase spending, he said.
富兰克林邓普顿固定收益部门全球首席投资官索娜尔·德赛表示:“无论你谈论的是哪个党派,都无所谓。我们只是有挥霍无度的人掌权。”她对美国国债持中立态度,要想转向看好美国国债,“我们需要看到一些债券市场‘义警’出现”,或者出现显著的经济放缓。
“It doesn’t matter which party you are talking about,” said Sonal Desai, global chief investment officer for Franklin Templeton Fixed Income. “We just have profligates in power.”She’s neutral on US debt and in order to shift toward favoring US Treasuries, “we need to see some vigilantes come out,” or a significant economic slowdown.