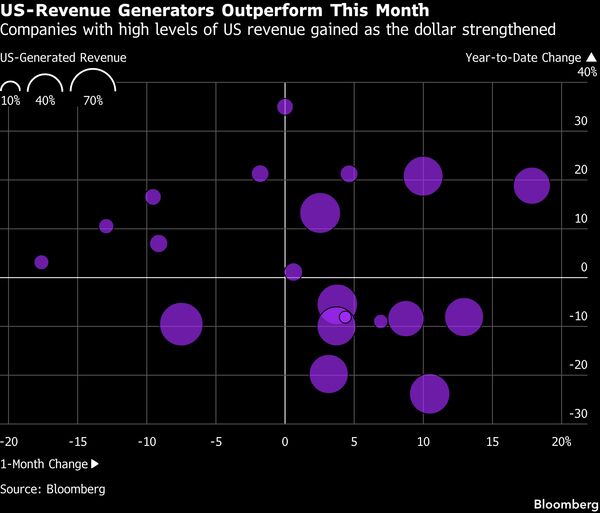
美元反弹对欧洲出口商股票构成利好,正值企业步入第三季度财报最密集的披露期。
The dollar’s rebound is good news for shares in European exporters, just as companies enter the busiest stretch of the third-quarter reporting season.
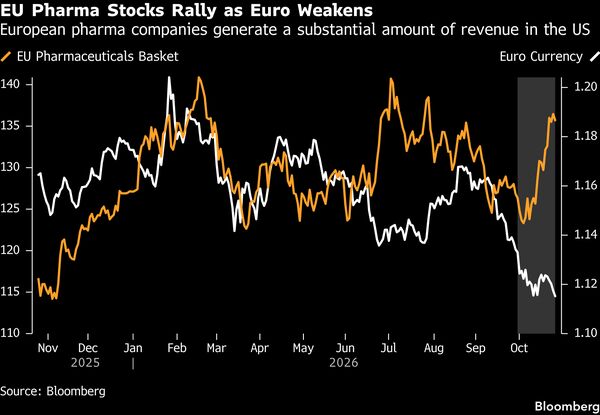
今年以来欧元兑美元已下跌逾5%,仅过去一个月就跌约2%,这对向欧洲以外客户销售产品的企业是一大福音。这扭转了2026年早些时候拖累这些股票利润的逆风局面,部分策略师认为市场尚未完全将其计入定价。
The euro has fallen more than 5% against the greenback this year and roughly 2% in the past month alone, a boon for firms that sell to customers outside Europe. It’s a reversal of the headwind that held back profits for these stocks earlier in 2026, and some strategists say it has yet to be fully factored in by the market.
瑞银集团(UBS Group AG)编制的一篮子对美销售敞口较大的股票,包括诺和诺德(Novo Nordisk A/S)、帝亚吉欧(Diageo Plc)、葛兰素史克(GSK Plc)和初灵(Rentokil Initial Plc)等,本月累计上涨近8%,涨幅创2022年7月以来新高。
A UBS Group AG basket of stocks exposed to US sales, including the likes of Novo Nordisk A/S, Diageo Plc, GSK Plc and Rentokil Initial Plc, has rallied almost 8% this month, the most since July 2022.
本周和下周将有占斯托克欧洲600指数(Stoxx 600)市值近40%的公司发布财报。欧元走弱对该指数是一大助力,其成分股约一半收入来自海外。
Companies representing nearly 40% of the Stoxx 600’s market capitalization are reporting this week and next. A weaker euro is a handy boost for an index whose members generate roughly half their revenue overseas.
汇丰控股(HSBC Holdings Plc)策略师估计,欧洲货币兑美元贬值5%可为区域盈利增长贡献约3.1个百分点。但在负面消息冲击下的市场中,即便是相对较小的汇率影响也能产生差异。
Strategists at HSBC Holdings Plc estimate that a 5% depreciation in European currencies against the dollar can add about 3.1 percentage points to regional earnings growth. But even a relatively small currency impact can make a difference in a market buffeted by negative news.
摩根士丹利投资管理公司欧洲股票策略主管迈克尔·菲尔德(Michael Field)表示,在市场情绪紧张之际,投资者正寄望财报寻找稳定迹象。
With sentiment on edge, investors are looking to earnings for signs of stability, according to Michael Field, Morningstar’s head of European equity strategy.
菲尔德说,欧元走弱可能通过“将部分符合预期的业绩转为超预期”来提供帮助。“市场意识到汇率带来了多少增量,但我仍不认为这已完全反映在价格中。”在盈利预期低迷的板块,获益可能最大。他提到联合利华(Unilever Plc)和雀巢(Nestle SA)等消费类公司,疲软需求和较高成本拖累了前景。“汇率带来的这额外一推,实际上可能产生巨大差异,”他说。
A weaker euro may help by “turning some meets into beats,” Field said. “There is an awareness of how much it’s bringing to the table, but I still don’t think it’s fully in the price.”The benefit may be greatest where earnings expectations are subdued. Field cited consumer companies including Unilever Plc and Nestle SA, where weaker demand and higher costs have weighed on the outlook. “That extra bump from FX could actually make a huge difference,” he said.
欧洲医疗保健行业是另一个潜在受益者,其约40%的收入来自美国,在斯托克600指数各板块中占比最高。Oddo BHF估计,近期美元走势可能使诺和诺德每股收益增加2.5%-3.5%,使赛诺菲每股收益增加2%-3%。这两家公司将在未来两周内发布财报。
European healthcare is another potential beneficiary, generating roughly 40% of its revenue in the US, the highest among Stoxx 600 sectors. Oddo BHF estimates the recent dollar move could add 2.5%-3.5% to Novo Nordisk’s earnings per share and 2%-3% at Sanofi SA. Both report within the next two weeks.
汇率影响还意味着,基金经理可以在宏观经济条件看起来不那么吸引人的国家寻找股票机会。
Currency effects also mean fund managers can find stock opportunities in countries where broader economic conditions look less appealing.
“我对未来几年英国和欧洲经济可能持谨慎态度,”Ninety One全球股票投资组合经理Dan Hanbury表示。“然而,考虑到海外收入占比之高,这与对其股市持谨慎态度截然不同。”尽管如此,对欧洲跨国盈利企业有利的因素,未必利好整个大盘。
“I may have a cautious view of the UK and European economies over the next few years,” said Dan Hanbury, a global equity portfolio manager at Ninety One. “However, that is very different to being cautious on their stock markets given how much of the revenue is made overseas.”For all that, what benefits Europe’s international earners isn’t necessarily good for the market as a whole.
据摩根士丹利投资管理副首席投资官Jitania Kandhari称,历史上当欧元走强时,欧洲股票往往跑赢其他地区。这在一定程度上反映了该地区对国内金融股的大比例配置,这些金融股受益于欧元走强带来的更强购买力、经济活动和信贷增长。
European equities have historically tended to outperform other regions when the euro strengthens, according to Jitania Kandhari, deputy chief investment officer at Morgan Stanley Investment Management. That partly reflects the region’s large weighting toward domestically exposed financials, which benefit from the stronger purchasing power, economic activity and credit growth associated with a stronger euro.
“只有欧元走强,MSCI欧洲指数整体才能在相对基础上跑赢大盘,”Kandhari说。如果欧元持续下跌,她将对南欧部分地区更加谨慎,因为这些地区的国内金融股权重显著。
“You really need euro strength for the aggregate MSCI Europe to outperform on a relative basis,” Kandhari said. A sustained decline would make her more cautious on parts of southern Europe, where domestic financials carry significant weight.
在个股层面,情况变得更加复杂。阿迪达斯和彪马在亚洲的采购以美元计价,意味着美元持续走强最终可能损害利润率,而复杂的对冲操作可能会延迟或削弱出口商的获益。
At the individual-stock level, the picture gets more complicated still. Adidas AG and Puma SE have dollar-denominated Asian sourcing meaning sustained greenback strength can ultimately hurt margins, while sophisticated hedging can delay or mute the benefit for exporters.
Hanbury指出,其公司重点推荐股之一的罗尔斯·罗伊斯控股公司,拥有覆盖多年航空发动机服务合同的大规模对冲账簿。
Hanbury points to Rolls-Royce Holdings Plc, among his firm’s top picks, where a large hedge book covers multi-year airline servicing contracts.
“问题在于时机和对冲,这永远不会像你希望的那样精确,”汉伯里说。“对冲会导致数字传导出现滞后。”对于长期投资者而言,这种复杂性使得货币成为另一个需要管理的风险,而非投资论据的基础。Rathbones基金经理大卫·库姆斯表示,他愿意容忍全球多元化业务(如欧莱雅)的短期外汇波动,但当多项持仓使投资组合面临同一种货币敞口时,他会变得更加谨慎。
“The problem is timing and hedging and it’s never as exact as you’d like it to be,” Hanbury said. “Hedging creates a lag in the numbers coming through.”For longer-term investors, that complexity makes currency another risk to manage rather than the basis for an investment thesis. Rathbones fund manager David Coombs said he is willing to tolerate short-term foreign-exchange volatility in globally diversified businesses such as L’Oreal SA, but becomes more cautious when several holdings leave a portfolio exposed to the same currency.
“货币是决策链条中的最后一环,”库姆斯说,并补充称,很难预测其对整体利润和回报的影响。
“The currency is the last decision in the chain,” Coombs said, adding that it’s difficult to forecast its impact on overall profits and returns.
欧元持续走弱可能进一步提振盈利。Brown Brothers Harriman全球市场策略主管Elias Haddad认为,随着美国经济表现优异和利率差继续利好美元,欧元有空间在年底前走弱至1.10美元。
The euro’s continued weakness potentially sets up a further earnings boost. Elias Haddad, global head of markets strategy at Brown Brothers Harriman, sees scope for the currency to weaken toward $1.10 by year-end as US economic outperformance and interest-rate differentials continue to favor the dollar.
导致进一步走弱的原因依然重要。因美国强劲增长导致的欧元下跌,对欧洲资产的影响与因投资者要求更高本土风险溢价而导致的下跌截然不同。
The reason behind any further weakness still matters. A euro falling because of strong US growth has different implications for European assets than a decline caused by investors demanding a higher risk premium at home.
法国财政压力可通过货币走弱提振出口商的折算收益,但同时也会推高主权利差、融资成本以及美元计价进口商品的价格。
French fiscal stress can boost exporters’ translated earnings through a weaker currency while simultaneously pushing up sovereign spreads, financing costs and the price of dollar-denominated imports.
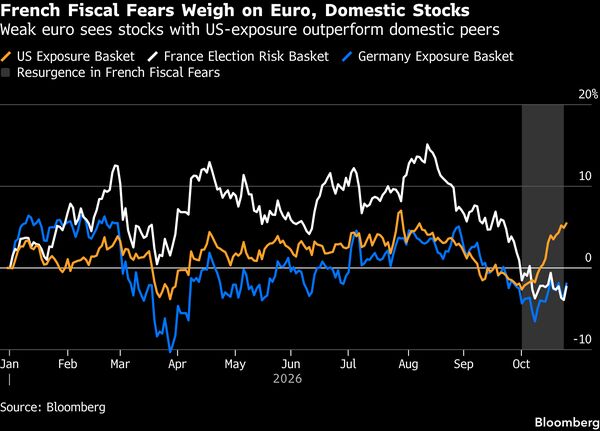
目前的法国事件可能止步于那种更具破坏性的情景。摩根士丹利的Kandhari认为,法国的财政动荡是一次重新定价,而非另一场欧元区危机。她表示,该国的财政问题已被充分理解,欧洲央行现在拥有强大得多的工具来应对传染风险。
The current French episode may stop short of that more damaging scenario. Morgan Stanley’s Kandhari sees France’s fiscal turmoil as a repricing rather than another euro-zone crisis. The country’s fiscal problems are well understood and the European Central Bank now has significantly stronger tools to manage contagion, she said.
整体局面可能使欧洲股市处于某种“最佳位置”:货币疲软足以带来盈利上行惊喜,又不至于压倒支撑大盘的国内因素。其结果可能是一轮外汇助推,其惠及范围远超直接受益的出口商。
The overall setup could leave European equities in something of a sweet spot: enough currency weakness to create upside earnings surprises, without overwhelming the domestic forces supporting the broader market. The result could be a foreign exchange boost that reaches well beyond the exporters benefiting from it directly.