全球基金经理再次对日本债券市场升温,随着国内需求复苏迹象和更有利的政策环境出现,高收益率的吸引力进一步增强。
Global fund managers are warming to Japan’s bond market again as signs of recovering domestic demand and a more supportive policy backdrop add to the appeal of elevated yields.
今年早些时候削减日本国债敞口的 T. Rowe Price Group Inc.(普信集团)目前青睐久期较长的债券。Allianz Global Investors(安联全球投资)正有选择地增持中长期债券,而 BNP Paribas Asset Management(法国巴黎银行资产管理)则增加了超长期债务的敞口。
T. Rowe Price Group Inc., which scaled back exposure to Japanese government bonds earlier this year, now favors bonds with longer maturities. Allianz Global Investors is selectively adding intermediate- and long-dated bonds, while BNP Paribas Asset Management has built up its exposure to super-long debt.
这一转变标志着今年早些时候趋势的逆转,当时仅凭高收益率不足以补偿投资者面对的担忧:日本央行加息步伐过慢、财政支出将膨胀债务供给、传统国内买家依然在场外观望。对日本央行进一步加息的预期以及保险公司需求回归的迹象,如今让基金经理更有信心利用这些收益率。
The shift marks a reversal from earlier this year, when high yields alone weren’t enough to compensate investors for concerns that the Bank of Japan was raising rates too slowly, fiscal spending would swell debt supply and traditional domestic buyers remained on the sidelines. Expectations for further BOJ rate hikes and signs of returning demand from insurers are now giving fund managers more confidence to take advantage of those yields.
“我们对日本国债久期的看法变得更加建设性,并有选择地增加敞口,特别是在收益率曲线的中长端部分,”管理 6530 亿欧元资产的安联全球投资亚太区固定收益首席投资官 Mark Tay(马克·泰)表示。“实际收益率更具吸引力,我们看到国内需求回归和外资兴趣增加的证据不断增多,这应有助于支撑市场。” 这种基调变化伴随着长期债券的复苏。
“We have become more constructive on JGB duration and have been selectively adding exposure, particularly in the intermediate to long end part of the curve,” said Mark Tay, chief investment officer for fixed income in Asia Pacific at AllianzGI, which manages €653 billion in assets. “Real yields are more attractive and we are seeing growing evidence of domestic demand returning and foreign interest, which should help support the market.”The change in tone has coincided with a recovery in longer-dated debt.
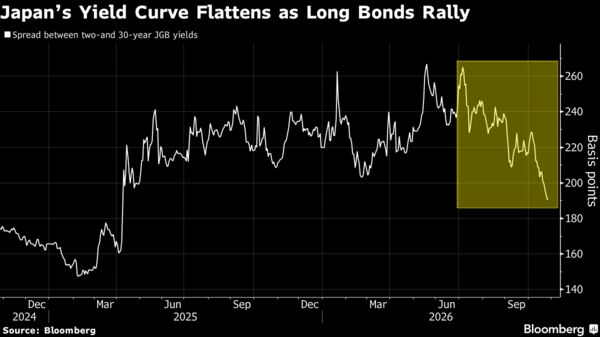
本月早些时候,30 年期日本国债收益率从 4.25% 的高点下跌了近 40 个基点,即使全球债券市场波动持续。2 年期与 30 年期日本国债收益率的利差自 7 月以来收窄了约 70 个基点。日本将于周四举行 2 年期国债拍卖,预计需求将保持强劲。
The 30-year JGB yield has fallen almost 40 basis points from a peak of 4.25% earlier this month, even as volatility persisted across global bond markets. The gap between two- and 30-year JGB yields has narrowed by about 70 basis points since July. Japan will hold an auction of two-year government bonds on Thursday, where demand is expected to be solid.
德意志证券首席日本固定收益策略师大森祥树(Shoki Omori)表示,随着今年早些时候10年期收益率升破3%、30年期收益率触及4%,达到数十年来未见的水平,估值变得越来越有吸引力。
Valuations became increasingly attractive as the 10-year yield climbed above 3% and the 30-year reached 4% earlier this year, levels unseen in decades, according to Shoki Omori, chief Japan fixed-income strategist at Deutsche Securities.
他估计,这些收益率中大约三分之二反映了期限溢价——即投资者要求的持有长期债务的额外补偿。大森认为,一旦日本央行(BOJ)加息周期结束进入视野,该溢价有望收窄,从而使长端债券表现优于短端,即使加息仍在继续。
He estimates roughly two-thirds of those yields reflected term premium — the extra compensation investors demand for holding longer-maturity debt. Omori sees scope for that premium to shrink once the end of the BOJ’s tightening cycle comes into view, allowing the long end to outperform even as rate hikes continue.
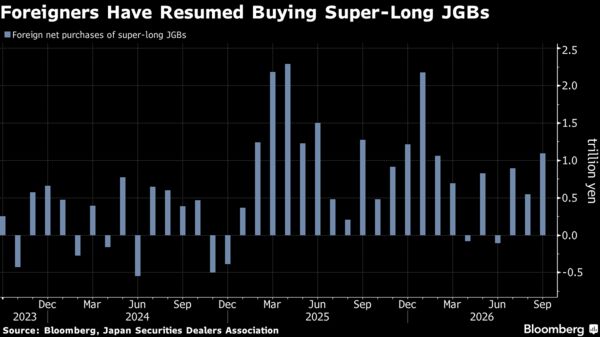
改善需求的迹象已经出现。日本人寿保险公司已连续四个月净买入超长期国债,部分公司表示计划维持或增加国内债券购买。根据日本证券业协会数据,海外投资者也已连续三个月净买入超长期日本国债(JGB),扭转了4月和6月的净卖出局面。
Signs of improving demand are already emerging. Japanese life insurers have bought super-long government bonds on a net basis for the past four months, and some have signaled plans to maintain or increase domestic debt purchases. Overseas investors have also been net buyers of super-long JGBs for three straight months, reversing net selling in April and June, according to Japan Securities Dealers Association data.
T. Rowe Price投资组合经理Vincent Chung现在在日本央行加息之际看好长端债券,预期收益率曲线将趋平。这标志着较今年早些时候的转变,当时他在此前低配一年后于1月买入日本国债,但一个月后因财政担忧加剧而削减了持仓。
Vincent Chung, a portfolio manager at T. Rowe Price, now favors the long end as the BOJ raises rates, expecting the yield curve to flatten. That marks a turnaround from earlier this year, when he bought JGBs in January after being underweight for the previous year, only to scale back a month later as fiscal concerns intensified.
Chung现在认为,在近期散户买入以及拟议税收优惠若推出可能带来额外需求的帮助下,供需关系将在年底前变得更加平衡。政府养老基金(GPIF)资产配置的潜在变化可能提供另一支撑来源,但他表示,任何决定将部分取决于全球市场表现。
Chung now sees supply and demand becoming more balanced toward year-end, helped by recent retail buying and the prospect of additional demand if proposed tax incentives are introduced. Potential changes to the Government Pension Investment Fund’s allocations could provide another source of support, though he said any decision would depend partly on global market performance.
法国巴黎资产管理(BNP Paribas Asset Management)也在增加敞口。全球综合及绝对收益主管James McAlevey表示,该公司今年早些时候将长端日本国债仓位从“极小规模”增至“中等偏小至中等规模”,青睐20年期和30年期债券。
BNP Paribas Asset Management has also been increasing exposure. James McAlevey, head of global aggregate and absolute return, said the firm has grown its long-end JGB position from a “very small size” early this year to a “moderate to medium size,” favoring 20- and 30-year bonds.
财政政策仍是更持续反弹的最大障碍,2027财年发债计划将考验债市情绪初步复苏的成色。投资者正密切关注政府计划如何为拟议的食品减税和增加防卫开支提供资金。
Fiscal policy remains the biggest obstacle to a more sustained rally, with the fiscal 2027 debt-issuance plan set to test the nascent recovery in bond-market sentiment. Investors are closely watching how the government plans to fund a proposed sales-tax cut on food and higher defense spending.
T. Rowe Price的钟(Chung)表示,如果预算未能明确资金来源,他对收益率曲线趋平的看法将面临风险。德意志证券的大森(Omori)警告称,更大规模的补充预算,或未能进一步削减超长期债券供给的发行计划,都可能扭转日本国债(JGB)近期趋平的走势。
T. Rowe Price’s Chung said his curve-flattening view would be at risk if the budget fails to identify clear funding sources. Deutsche Securities’ Omori warned that a larger supplementary budget or an issuance plan that fails to further reduce super-long supply could reverse the recent flattening in JGBs.
Brandywine Global Investment Management今年早些时候削减了日债敞口并抛售了30年期持仓,至今未回补。投资组合经理Carol Lye表示,高市早苗(Sanae Takaichi)内阁基调转变、不再宣扬再通胀言论,有助于锚定收益率,但投资者仍在等待一个可信的融资方案。随着10年期收益率重回3%以下,她也看到需求放缓的空间。
Brandywine Global Investment Management, which cut its JGB exposure and sold its 30-year holdings earlier this year, hasn’t bought back in. Portfolio manager Carol Lye said a shift in tone under Prime Minister Sanae Takaichi’s administration away from reflationary rhetoric has helped anchor yields, but investors are still waiting for a credible funding plan. With the 10-year yield back below 3%, she also sees scope for demand to slow.
日本央行(BOJ)将在周五的政策决定中带来另一项考验。官员们普遍预计将维持利率不变,投资者聚焦于植田和男(Kazuo Ueda)行长关于加息节奏的指引,以及利率距离最终峰值可能有多近。
The BOJ will provide another test at its policy decision Friday. Officials are widely expected to keep rates unchanged, leaving investors focused on Governor Kazuo Ueda’s guidance on the pace of tightening and how close rates may be to their eventual peak.
BNP的McAlevey认为,要进一步增强信心,需要政府给出“相对受约束的财政应对”以及日本央行持续收紧。他表示,央行本周不一定非要加息,但12月行动加上持续“相对鹰派”的沟通就足够了。
For BNP’s McAlevey, further conviction would require both a “relatively constrained fiscal response” from the government and continued BOJ tightening. The central bank doesn’t necessarily need to hike this week, he said, but a December move and continued “relatively hawkish” communication would be sufficient.