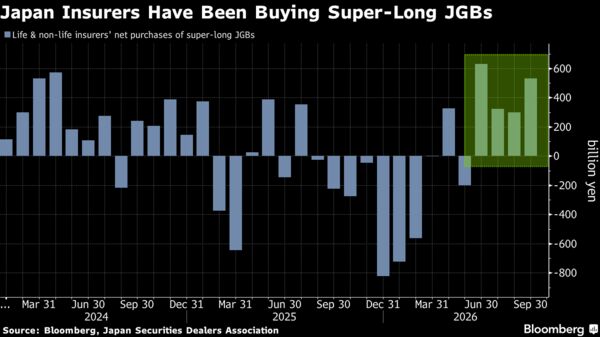
日本各大人寿保险公司纷纷发出信号,表示将在本财年下半年维持或增加对国内债券的购买,这为即将到来的政府债务招标活动提供了潜在的支撑来源。
Japanese life insurers are signaling they will maintain or increase purchases of domestic bonds in the second half of the fiscal year, offering a potential source of support for upcoming government debt auctions.
日本邮政保险公司表示,计划增加日元计价债券的购买,但未明确具体品种;大同生命保险公司则提高了其国内债券持仓的计划增幅,主要通过公司债来实现。与此同时,明治安田生命保险公司计划将其国债持仓保持大致不变,同时将低收益债券置换为高收益证券。
Japan Post Insurance Co. said it intends to increase purchases of yen-denominated bonds without specifying which ones, while Daido Life Insurance Co. has raised its planned increase in domestic bond holdings, mainly through corporate debt. Meanwhile, Meiji Yasuda Life Insurance Co. plans to keep its government bond holdings roughly unchanged while switching out of lower-yielding debt into higher-yielding securities.
这些计划进一步表明,来自日本最重要的债券投资者群体之一的需求正开始复苏。日本证券交易商协会的数据显示,在过去四个月里,保险公司一直是超长期日本国债的净买家,策略师们表示,这一趋势可能会为即将到来的招标提供更稳固的锚定。
The plans add to signs that demand from one of Japan’s most important groups of bond investors is beginning to recover. Insurers have been net buyers of super-long JGBs for the past four months, according to Japan Securities Dealers Association data, a trend strategists say could provide a firmer anchor for upcoming auctions.
法国兴业银行策略师斯蒂芬·斯普拉特表示:“寿险公司在下半年似乎可能会上调对日本国债的胃口。国内需求正开始回升,而与此同时,超长期国债的招标规模有所缩减。”在此次转变发生之际,经过多年超低利率迫使日本机构转向海外及更高风险资产之后,更高的收益率改变了它们的投资算盘。超长期日本国债收益率近期已接近数十年来的高点,这提升了国内债务的吸引力,尽管投资者仍对利率可能进一步攀升保持警惕。
“Life insurers appear likely to revise up their appetite for JGBs in the second half,” said Stephen Spratt, a strategist at Societe Generale SA. “Domestic demand is beginning to pick up and this comes against the reduced size in super-long auctions.”The shift comes as higher yields alter the investment calculus for Japanese institutions after years of ultra-low rates pushed them toward overseas and riskier assets. Super-long JGB yields have recently approached multi-decade highs, increasing the appeal of domestic debt even as investors remain wary that rates could climb further.
人寿保险公司是长期政府债券尤为重要的买家,因为它们利用这些债券来匹配长期负债。其需求传统上集中在超长期领域,这使得它们的投资计划备受关注,因为在政府寻求为其债务寻找买家的同时,日本央行正在减少其在市场上的存在感。
Life insurers are particularly important buyers of longer-dated government bonds because they use them to match long-term liabilities. Their demand has traditionally been concentrated in the super-long sector, making their investment plans closely watched as the government seeks buyers for its debt while the Bank of Japan reduces its presence in the market.
周二进行的20年期日本国债招标显现出了需求改善的迹象,该次招标吸引了有记录以来最高的认购倍数。这一结果表明,即便在由中东局势升级、油价上涨以及对通胀和政府借款的担忧所引发的全球债券抛售潮之后,走高的收益率仍在吸引买家。
Signs of improving demand were evident at Tuesday’s 20-year JGB auction, which drew the strongest bid-to-cover ratio on record. The result suggested elevated yields are enticing buyers even after a global bond selloff driven by escalating tensions in the Middle East, higher oil prices and concerns over inflation and government borrowing.
根据日本人寿保险协会截至7月底的数据,日本各保险公司拥有约386万亿日元(合2.4万亿美元)的投资资产,这意味着它们资产配置的微小变化也可能对国内和海外市场产生影响。
Japanese insurers have about ¥386 trillion ($2.4 trillion) of invested assets, according to end-July data from the Life Insurance Association of Japan, meaning even incremental changes in their allocations can have implications for domestic and overseas markets.
隆奥高级宏观策略师李浩民表示,来自首相高市早苗执政下的第二次补充预算案可能性、2027财年初步预算案以及日本央行政策前景的风险依然存在。尽管如此,他补充说,随着供应前景变得更加明朗且需求趋于稳定,招标在“未来几周内很可能找到一个稍微更好的锚”。
Risks remain from the possibility of a second supplementary budget under Prime Minister Sanae Takaichi, the fiscal 2027 initial budget and the outlook for BOJ policy, said Homin Lee, senior macro strategist at Lombard Odier. Even so, auctions are likely to find “a slightly better anchor in the next few weeks” as the outlook for supply becomes clearer and demand stabilizes, he added.
汇丰控股亚太区利率策略师贾斯汀·恒表示,日元的相对稳定也可能鼓励了投资者增加对日本国债的敞口,鉴于其具有吸引力的绝对收益率以及更陡峭的收益率曲线。“在我们看来,日本国债市场的这段相对平静期可能会持续更长时间。”
Relative stability in the yen may also have encouraged investors to add JGB exposure given attractive absolute yields and a steeper curve, according to Justin Heng, APAC rates strategist at HSBC Holdings Plc. “In our view, this period of relative calm in the JGB market could persist for a while longer.”