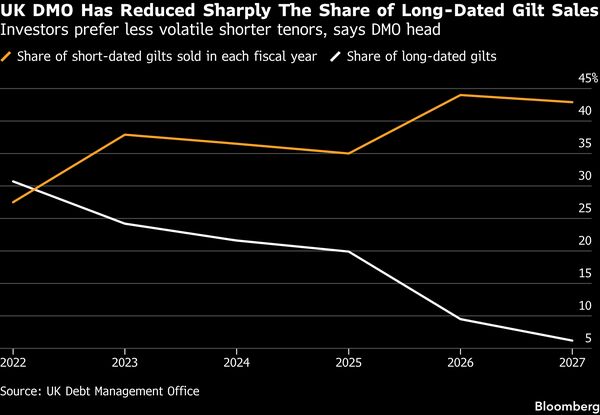
英国债务管理办公室(DMO)正进一步减少长期英国国债的发行,以满足投资者对受债券市场波动影响较小的短期债券的需求,首席执行官杰西卡·普莱(Jessica Pulay)表示。
The UK Debt Management Office is pulling back further from long-dated gilts to meet investor demand for shorter tenors that are less exposed to swings in the bond market, Chief Executive Jessica Pulay said.
DMO周三上调了本财年英国国债发行计划数十亿英镑,但关键的是将发行进一步从长期债务转移出去,将长期债券发行规模较4月的数字下调约三分之一,至155亿英镑(约合208亿美元)。
The DMO raised this fiscal year’s gilt sale plan by a few billion pounds on Wednesday, while crucially shifting issuance further away from longer-dated debt, revising it down by around a third to £15.5 billion ($20.8 billion) from April’s figure.
长期英国国债现在将占今年发行总量的约6%,较五年前的30%大幅下降。
Long gilts will now make up around 6% of this year’s issuance, a large drop from the 30% seen five years ago.
“短期英国国债需求强劲,”普莱在接受采访时表示。“我认为这只是反映了投资者需求的持续转变,”她补充道,并指出与长期债券相比,短期债券的需求依然更强。“尤其是考虑到全球债券市场持续的波动,这对长期债券的影响尤为明显。”她表示,根据DMO的评估,与长期债券相比,短期债券为政府支出融资更具成本效益。
“There is a strong demand for short-dated gilts,” Pulay said in an interview. “I think that just reflects the ongoing shift in investor demand,” she added, noting that this remained stronger at the shorter end relative to longer maturities. “Not least given the persistent volatility in global bond markets, which particularly affects the longer maturities.”Based on the DMO’s assessment, shorter maturities are more cost-effective relative to longer maturities to fund government spending, she said.
英国一直在削减长期债务发行,帮助将加权平均期限从五年前的约17年降至约11年。随着美伊战争导致油价飙升、引发通胀担忧,并推高英国30年期国债收益率至6%——使其成为自2012年欧元区债务危机以来首个支付如此高利率的七国集团经济体——这一转变变得更加重要。
The UK has been cutting long-dated debt issuance, helping reduce the weighted-average maturity to around 11 years from 17 about five years ago. That shift took on greater significance as the US-Iran war sent oil prices spiraling, stoked inflation fears and pushed the UK’s 30-year yield to 6% — making it the first Group of Seven economy to pay a rate that high since the 2012 euro area debt crisis.
然而,自那些高点以来,英国国债市场已降温,本周在伯纳姆政府的首份预算案及随附的DMO发行指令大体符合预期、并强化了向短期发行转移的预期后,录得温和涨幅。
However, the gilt market has since cooled from those peaks and posted modest gains this week after the Burnham government’s first budget and accompanying DMO remit broadly met expectations and reinforced the anticipated shift toward shorter-dated issuance.
英国债务管理办公室(DMO)取消了本财年剩余时间的三场长期常规拍卖,并公布了将于1月启动的国库券计划细节,以回应市场对短期限债券日益增长的需求。同时还将设立回购机制,以支持这一新计划。
The DMO cancelled three long conventional auctions for the rest of the fiscal year and set out details of a Treasury bill program due to start in January, responding to growing demand for shorter-dated maturities. There will also be a repo facility to support the new program.
“总体而言,市场参与者希望看到国库券拥有更高的流动性,”她表示。回购市场“在英国长期国债市场已高效运行多年。因此我们认为,尝试在国库券市场复制这一模式非常重要。”
“Overall, market participants are keen to see greater liquidity in Treasury bills,” she said. Repo markets “have worked very efficiently over a number of years in the gilt market. So we felt it was important to try to replicate that for Treasury bills.”