我们不想陷入太深的细枝末节。不要把事情复杂化,那只会导致次优的思考。我之所以从这个简单的原则说起,是因为当你面对数据中心的崛起——这个“史上最伟大的故事”——迄今最大的挑战时,你只需要像“水门事件”调查中的记者们那样跟着钱走。你会发现,这个投资故事已经破裂,资金已经转移——也许不是永远,但在数据中心建设的尘埃落定之前。
We don't want to get caught too deep in the weeds. Don't overcomplicate things. It will only lead to suboptimal thinking. I start with that simple precept because when you're facing the biggest challenge yet to The Greatest Story Ever Told — the rise of the data center — you just need to follow the money, as the reporters did in the Watergate investigation. You'll find that the investment story has broken down, and the money has moved on — perhaps not for good, but until the dust settles around the data center buildout.
让我们回顾一下上周的残酷景象。我们经历了一场令人元气大伤的抛售,一次真正的“放弃”,前所未见。这其中包括7月下旬“态势感知”基金的崩盘,那是由利奥波德·阿申布伦纳管理的一只被荒谬炒作的对冲基金,由于没有风险控制而爆仓。我鄙视那种鲁莽。在我的整个职业生涯中,我一直把风险控制置于选股之上,这可以追溯到上世纪80年代我在高盛工作的时候。
Let's revisit the brutal tableau of last week. We had a debilitating sell-off, a real "give up" that was unlike anything we have seen. That includes the collapse in late July of Situational Awareness , that ridiculously hyped hedge fund led by Leopold Aschenbrenner that blew up because it had no risk controls. I have contempt for that kind of recklessness. Throughout my career, I've prioritized risk control over stock picking, dating back to my time at Goldman Sachs in the 1980s.
如果你没有风险控制,就趁早滚出这一行。但“态势感知”并不是因为阿申布伦纳的论点而爆仓——他的论点是,可能再也不会有比数据中心建设更好的投资故事了,因为它涉及如此多的行业。它因一个瞬间的小故障而爆仓,缺乏风控放大了这一故障。而这一次,爆掉的恰恰是论点本身。就在同一时刻,我们终于得到了一个反向论点:利率下降的前景。
If you don't have risk controls, get the heck out of the business. But Situational didn't get blown out because of Aschenbrenner's thesis: that there may never be a better investment story than the data center buildout, which touches so many sectors. It got blown out by a momentary glitch, magnified by his lack of controls. This time, it was the thesis itself that blew up. At the exact same time, we finally got a countervailing thesis: the prospect of lower interest rates.
在投资中,利率总是胜过任何其他概念,因为利率是塑造市场的所有力量的总和——美联储、经济、通胀、国债、货币需求。利率太庞大,无法说谎。上周利率略有下降,我听到的全是投资者“逃向优质资产”的说法。但这只说对了一部分。我们开始看到通胀放缓。
Rates always trump any other concept in investing because they are the sum total of the forces shaping the market — the Federal Reserve, the economy, inflation, Treasury debt, money demand. Rates are too big to lie. Rates fell slightly last week, and all I heard about was a "flight to quality" among investors. But that's only partially true. We are beginning to see a slowdown in inflation.
9月份那次四分之一百分点的加息,在美联储主席凯文·沃什的坚定立场下,正发挥着非常强大的作用,而沃什似乎并不打算配合总统。沃什看起来很独立,人们没有料到这一点。这种转变是真实的,超越人工智能交易的替代方案也是真实的——食品、医药和非耐用消费品股票。生物科技可能提供最好的长期机会。它们已从昙花一现的萤火虫,转变为下一代默克或礼来。
That quarter-point rate increase in September is proving very powerful when coupled with a determined Fed Chair in Kevin Warsh, who doesn't seem to be playing ball with the president. Warsh seems independent, and people didn't count on that. The shift is real, and so are the alternatives beyond the AI trade — food, drugs, and soft-goods stocks. Biotech may offer the best long-term opportunities. They have been transformed from fly-by-night fireflies to the next Merck or Eli Lilly .
作为一家长期处于二流地位的公司,阿斯利康正在实时重新定价。这些人工智能交易的替代方案可能具有持久力。也许获胜者的估值会不断增长?我们能为默克支付200美元吗?也许可以。看起来过分了。但难道我们不是开始为科技股支付极高的倍数吗?难道这不是卖出一些苹果股票获利了结的理由吗,除非你像我一样,对长期持有苹果有着执着的偏好?
AstraZeneca , a perennial second-rater, gets rerated in real time. These alternatives to the AI trade might have staying power. Maybe the valuations of the winners keep growing? Can we pay $200 for Merck? Maybe. Seems excessive. But didn't we start paying incredibly high multiples for tech? Isn't that a reason to take some profits in Apple unless you are as storied about holding it through thick and thin as I am? (Obviously, I am signaling that if you want to step aside from the impossible situation of Apple at 40 times earnings and revisit it, that makes sense.)
(显然,我在暗示,如果你想暂时避开苹果40倍市盈率的不可能局面,稍后再回头,那是合理的。)我们就顺势买入吗?这取决于你的投资策略。如果你认同我们的策略,那它就给了你一个自动买入的信号,因此才会不断提及强生。因此才有金伯利-肯维的博弈。因此才钟爱可口可乐。人工智能建设仍然是房间里的大象。
Do we just buy into the rotation? The answer to that depends on your investing strategy. If you share ours, it gives you an automatic buy-in, hence the endless references to Johnson & Johnson . Hence the Kimberly-Kenvue gambit. Hence the love of Coca-Cola . The AI buildout remains the elephant in the room.
降息可能让替代方案更具吸引力,但并不会让“最伟大的故事”消失。到底发生了什么?随着中期选举临近,局势变得如此紧张,即使是铁杆支持者也难以承受压力。让我们来看看正在击败数据中心的三大力量。第一,选举据称是对数据中心的公投。我们知道它们仍会被建造。但如果民主党表现良好,我们必须假设推进的项目会减少。例如,如果需要200个,只有150个会启动。难道这不是GE维诺瓦股价下跌的原因吗?
Lower rates may make alternatives more attractive, but they don't make The Greatest Story go away. What's really happening? With the midterm elections looming, the moment has become so fraught that even the diehards are struggling to bear the pressure. Let's go over the three big forces that are defeating the data center. First, the election is allegedly a referendum on the data center. We know they will still be built. But if the Democrats do well, we have to presume fewer will go ahead. For example, if we need 200, only 150 are put in motion. Isn't that why GE Vernova is down?
燃气涡轮机制造商报告称,没有取消订单,订单积压量继续增长,尽管其季度业绩并不完美。投资者还是抛售了股票,使得糟糕的一周雪上加霜,而这一周的压轴戏是英特尔那支“打不准枪”的团队。如果民主党大胜,超大规模云服务商和转型为数据中心建设商的比特币经理们可能会受损。诉讼使得选举变得混乱不堪,前所未见。
The gas turbine maker reported zero cancellations and an order book that continues to grow, even though its quarter wasn't perfect . Investors bailed anyway, compounding a dreadful week capped off by the gang that couldn't shoot straight at Intel . The hyperscalers and the bitcoin managers turned data center builders could suffer if the Dems score a landslide. Lawsuits make it a disorderly election unlike any we have seen.
我们知道,数据中心建设商在设施建成后没有雇佣足够的人员来运营。起初,他们污染了水资源并推高了电价。但这已不再属实。数据中心建设商在建设地点提供补贴,而非相反。然而,损害已经造成,且因关于工作被夺走的无休止讨论而雪上加霜,这场讨论的领头人正是财务上自杀式的达里奥·阿莫代。Anthropic首席执行官竟敢对即将到来的白领工作“恐龙时代”说出如此多自毁性言论。
We know data center builders didn't hire enough people to operate their facilities once they were finished. Initially, they despoiled the water supplies and raised electricity prices. That's no longer true. Data center builders subsidize where they build, not the other way around. However, the damage was already done, compounded by the endless discussion of jobs taken, led by none other than the financially suicidal Dario Amodei. The Anthropic CEO had the temerity to say so many self-destructive things about the coming dinosaur age of white-collar jobs.
当你听到AI可能在未来一到五年内取代一半初级白领工作——正如阿莫代所说——你就能看到恐龙正蹒跚走向死亡。他和OpenAI首席执行官萨姆·阿尔特曼真是令人费解的人物:对自己言辞的力量如此幼稚不成熟,对后果如此漠不关心。他们怎么知道工作会消失?为什么他们看不到AI的积极面——甚至包括递归系统,其中“小妖”会创造更多“小妖”——可能会创造新工作,甚至更多工作?
When you hear AI could displace half of all entry-level white-collar jobs in the next one to five years, as Amodei said, you can see the dinosaurs trudging to their deaths. He and OpenAI CEO Sam Altman are such quizzical figures: so dreadfully immature about the power of their words, so cavalier about the consequences. How do they know jobs will disappear? Why can't they see AI's positives — even recursive systems, where gremlins create more gremlins — could create new jobs and maybe more of them?
为什么要如此悲观,以至于给AI最大的反对者们提供弹药?他们不能说“既有好处也有坏处”吗?他们至少不能把自己的工作与之前的工业革命联系起来,向乐观而又有历史感的英伟达首席执行官黄仁勋致敬吗?为什么要拥抱歇斯底里而非历史?难道我们就该站在他们一边吗?最终,AI领导者们自己的傲慢——所有这些大惊小怪——会不会扼杀Anthropic的首次公开募股?
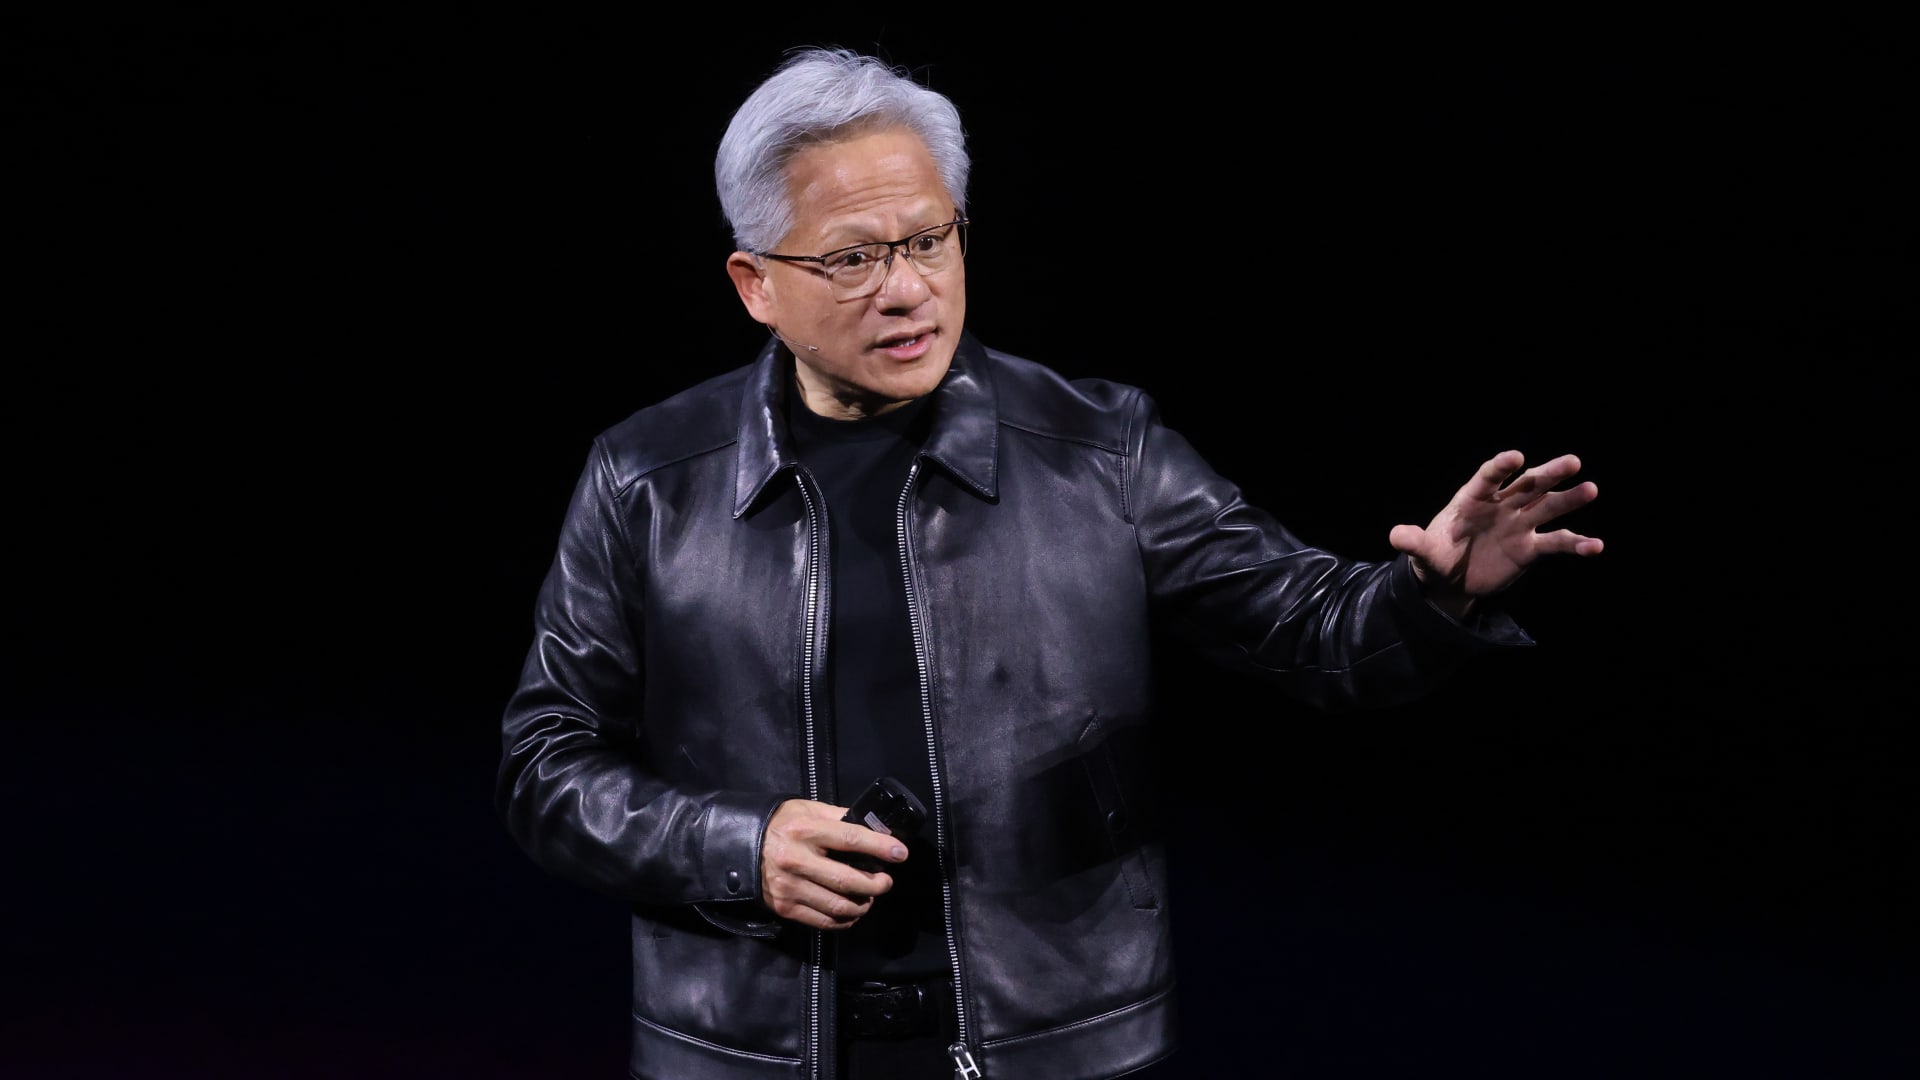
Why be so downbeat that it gives ammo to AI's biggest haters? Can't they just say, "Some good, some bad?" Can't they at least relate their own work to previous industrial revolutions, giving a nod to the optimistic yet historical Nvidia CEO Jensen Huang? Why embrace the hysterical over the historical? So we are supposed to side with them? In the end, could the AI leaders' own hubris — all this much ado about nothing — kill Anthropic's IPO?
那将比选民拒绝人工智能建设本身更糟。那不会是压死骆驼的最后一根稻草,而是火化。现实是什么?无论如何,都会建设大量数据中心。但去年12月,当我们意识到建设规模可能有多么巨大时,那个重大举措似乎注定会不断被推翻。是否会回到12月?这个国家正处于对人工智能参与者转为负面的情绪中。因此,我们有更多禁令和更多选址问题,无论如何都必须下调数字。
That would be worse than the electorate rejecting the AI buildout itself. That wouldn't be a nail in the coffin; it would be cremation. What's the reality? There will be plenty of data centers built either way. But the big move from December, when we realized how gigantic the build-out could be, still seems destined to be continually reversed. Does it go back to December? The country's in a mood to turn negative on the AI players. So we have more bans and more siting issues, and we have to take numbers down no matter what.
那是上周那场灾难的直接原因。第二?英伟达。众所周知,英伟达多年来一直是我最喜欢的股票。它赚最多的钱。它是所有数据中心行星围绕其旋转的太阳。但英伟达开始看起来像理查德·尼克松1970年形容的美国:一个“可怜的、无助的巨人”。英伟达就是那个可怜的、无助的巨人,如今据看跌者称,被揭露只是为了自身收益而支撑了一个生态系统,其首席执行官也被揭露是个可疑人物。
That was the proximate cause of last week's debacle. Second? Nvidia. As you know, Nvidia has been my favorite stock for ages. It makes the most money. It is the sun around which all the data center planets revolve. But Nvidia is starting to look like what Richard Nixon called the United States in 1970: a "pitiful, helpless giant." Nvidia is the pitiful, helpless giant, now revealed, according to the bears, to have just propped up an ecosystem for its own earnings, with a CEO now revealed to be a dubious character.
现在,你的作者,对这个人及其公司表示忠诚,完全不同意。据《纽约时报》上周的一篇报道,黄仁勋与一家新加坡数据中心公司的一位高管建立了密切关系,该高管被发现是向北京传递信息的间谍。黄仁勋无法阻止一家似乎需要尽可能多芯片的客户将部分芯片转运到中国。这种情况已经持续数十年。暗示是,特朗普总统被告知了这一情况,但因为黄仁勋奉承了他而视而不见——这一观点,得益于《纽约时报》的报道,如今甚至连股票圈外的人也持有。
Now your author, showing fealty to the man and his company, completely disagrees. According to a report in The New York Times last week, Huang formed a close relationship with a top executive at a Singapore-based data center company who was found to be a spy passing information to Beijing. Huang can't stop a customer that appears to need every chip it can get from transshipping some to China. That's been happening for decades. The implication is that President Donald Trump was informed of the situation but looked the other way because Huang flattered him — a view even people outside the stock world now hold, thanks to the Times' story.
事实上,所有高管,每一个,都与总统玩同样的游戏。特朗普已经认定了赢家,他想帮助他们。黄仁勋只是一直在做他一直做的事:出售芯片,帮助他的公司赚钱,并确保美国在数据中心文化中占据主导地位。
In truth, all executives, every one, play the same game with the president. Trump has identified the winners and he wants to help them. Jensen's just doing what Jensen has always done: selling chips to help his company make money and to ensure the U.S. dominates data center culture.
他想再次把芯片卖给中国,因为他知道这对股东和美国都有好处——如果中国不自行发展生态系统,而是依赖英伟达的话。没有别的原因。但我也知道我的观点并不重要。墙上的字迹显示,局面仍在逆转,盘中冲高后回落的旋转式拉升是最高点。现在卖出还不算太晚,但等到时机再次合适再买回非常困难。不过我承认,眼下几乎所有股票都已难以维持。
He wanted to sell his chips to China again because he knew it was good for shareholders and for the U.S. if China didn't develop its own ecosystem and instead relied on Nvidia's. There isn't more to it. But I also know that my view was irrelevant. The writing on the wall says the reverse continues, and the pirouette rally-to-intraday crash was the top. It's not too late to sell, but to buy it back when it's right again is very hard. But I concede that the stock is untenable for almost all right now.
为什么会这样?为什么长期持有的刀子刚刚变得更锋利?原因很简单:对数据中心的厌恶已经不止于选民。所有参与其中的人都想退出。我们厌倦了新云以及它们无法兑现承诺的能力。我们对它们的资产负债表持怀疑态度。我们知道它们的债券糟透了。我们知道它们的订单可疑。最重要的是,微软是这个令人绝望的板块中表现最好的股票,因为它将资本支出削减到恰好在自身承受范围内。
Why is that? Why have the long knives just gotten sharper? Simple: the hatred for the data center hasn't just reached the electorate. Everyone who is a part of it wants out. We are sick of the neo-clouds and their inability to pull off what they said they could. We are dubious about their balance sheets. We know their bonds suck. We know their orders are suspect. Most important, Microsoft is the best stock in this godforsaken group because it trimmed capex just enough to stay within its means.
它没有通过场内发售股票来给股价设上上限。它的核心业务没有像谷歌那样被侵蚀。它也没有像亚马逊那样承诺回报即将到来。亚马逊的业绩呼应了格特鲁德·斯坦在《神圣的艾米莉》中写的句子:“失误就是失误,就是失误”。微软现在因在支出上保持理性而受到赞扬。如果你持有美光、Iren 或 Nebius,这并不是你想听到的。
It isn't issuing shares through at-the-market sales that could put a lid on the stock. Its core business isn't eroding, as at Google. And it isn't promising that returns are just around the corner, as Amazon is. Amazon's results echoed Gertrude Stein's line in "Sacred Emily": a miss is a miss is a miss. Microsoft is now praised for being reasonable with its spending. That's not what you want to hear if you own Micron , Iren or Nebius .
后两者脆弱,仅靠荒唐的高空头持仓支撑。亚马逊则因试图满足客户需求而受到指责。首席执行官安迪·贾西和首席财务官布赖恩·奥尔萨夫斯基愿意超出自身能力范围进行支出,因为他们看到一个可能获胜的时机。他们认为,除谷歌云之外,Alphabet 的核心业务已经变得一团糟,因为它现在似乎更倾向于为广告主服务,而不是为客户服务。
The latter two are vulnerable and are only propped up by the ridiculous amount of short interest. Amazon, though, gets chastised for trying to meet its customers' demands. CEO Andy Jassy and CFO Brian Olsavsky are willing to spend beyond their means because they see a moment when they could win. They see that Alphabet's core business, aside from Google Cloud, has become a mess because it seems to be set up now for its advertisers, not its customers.
而这一切发生在其AI助手Gemini跌至ChatGPT、Claude甚至Grok之下的时刻。贾西似乎意识到谷歌已陷入困境——这让我想抛售我们的持仓。我们之所以持有,是因为其估值较低,且我相信其领导人不是糊涂虫,不会对威胁的严重性视而不见。贾西知道微软目前正受到赞誉,但两年后不会了,届时亚马逊云服务仍将以40%的速度增长,其零售业务也将逼近万亿美元。
And it's happening at the very moment when its AI assistant Gemini has dropped back below ChatGPT, Claude, and even Grok. Jassy seems to recognize that Google is hobbled — something that makes me want to sell our position. We've held on because of its lower valuation and my belief that its leaders aren't chowderheads, oblivious to how serious the threat is. Jassy knows that Microsoft is getting credit now, but won't two years from now when Amazon Web Services is still growing at 40%, and its retail business is closing in on a trillion dollars.
他掌握着主导权,即使支出暂时让股东承受压力。与投资者如今鄙弃的英特尔不同,亚马逊表示,其支出将在2027年下半年开始带来巨大回报,届时其半导体业务将腾飞并实现巨额盈利。相信贾西,自担风险?还是继续持有?我属于后者,这眼下看起来像是自寻死路,但我不是对冲基金经理,也不会被短期思维所评判。
He is in the driver's seat, even if the spending is momentarily punishing shareholders. Unlike Intel, which investors now despise, Amazon said there will be a huge return on its spending beginning in the second half of 2027, when its semiconductor business takes off for massive profitability. Believe Jassy at your own peril? Or let 'er ride? I am in the latter camp, which comes off right now as a death wish, but I am not a hedge fund manager, and I won't be judged by short-term thinking.
最后,还有股票本身。我现在先抛出几个想法,深入分析留到周五的年度股东大会再说。可以肯定的是,几乎所有季度业绩都很出色,只有一个例外:日本存储芯片制造商铠侠下调了指引。这不仅表明铠侠一团糟,也表明尽管SK海力士业绩非凡,该集团仍不可靠。当然,GE Vernova破坏了短期表现,卡特彼勒也更像一家卡车公司,我们也没有收到来自Lam的订单激增,但收益不会回落到2025年之前的水平。
And lastly, there are the stocks themselves. I'll tease you with a few thoughts now and save the in-depth analysis for Friday's Annual Meeting. Suffice it to say, nearly all of the quarterly results have been excellent, with one exception: Kioxia , the Japanese memory chipmaker, lowered its guidance. That doesn't just show that Kioxia is a mess, but also that the group is unreliable despite SK Hynix's extraordinary numbers. Sure, GE Vernova ruined the short term, and yes, Caterpillar became more of a truck company, and we didn't get the order spike from Lam , but earnings aren't reverting to pre-2025 levels.
股票也不应该回落到2025年12月,那时它们还没有飙升。然而,应该与否并不重要。就在此刻,我们正面对结局,并试图判断它是否会在选举以及总统将油价推至每桶150美元的举措之后到来。
And the stocks shouldn't revert to December of 2025, before they levitated. Yet, should doesn't matter. At this very moment, we are looking at the denouement and trying to figure out whether it will come after the election and the president's move to send oil to the $150s.
我们正在努力弄清楚,Marvell Tech 对 Lumentum 的收购要约是否会实际发生,以及它是否会让两只股票都上涨或下跌,后者令人恐惧,让我们无处可逃、无处可藏。所以我留给你们的是,除了脑残或被洗脑的人之外,每个多头经理的心态,我至少已经告诉了你们人们的感受,最好的可能性是,选举是一个清算事件,而 neoclouds 无论结果如何都不会崩溃和瓦解。
We are trying to figure out if Marvell Tech 's bid for Lumentum actually happens and whether it sends both stocks up or down, the latter being dreadful and giving us nowhere to run, nowhere to hide. So I leave you with the mindset of every long manager except the braindead or the brainwashed, and I at least have given you how people feel, with the best possibility being that the election is a clearing event and the neoclouds don't collapse and crumble regardless of the outcome. ()