Micro Devices Inc. 是今年表现最好的芯片股之一,但随着人们对人工智能支出的怀疑日益增加,该公司在周二下午发布财报时,需要强劲的业绩和激进的前景展望来维持涨势。
Micro Devices Inc. is one of this year’s best-performing chip stocks, but with skepticism about artificial-intelligence spending on the rise, it could use strong results and an aggressive outlook to maintain the momentum when the firm reports earnings Tuesday afternoon.
“要让它继续保持火热,不仅需要业绩超预期,还需要一个非常显著的超预期,并伴随一个相当显著的前景展望,”拥有该股票的 Allspring Global Investments 投资组合经理 Neville Javeri 表示。“温和的报告根本不够。”虽然华尔街预期 AMD 将发布强劲报告,但这正值投资者迅速抛售令其失望的股票之际。根据追溯至 1982 年的数据,Intel Corp. 因疲软的前景展望,在周五经历了股市上最糟糕的一天。
“What’s needed for it to keep on humming is not just a beat, but a significant beat that comes with a pretty significant outlook,” said Neville Javeri, portfolio manager at Allspring Global Investments, which owns the stock. “A modest report just won’t cut it.”While Wall Street expects a strong report from AMD, it lands at a time when investors have been quick to sell disappointment. Intel Corp. had its worst day in the stock market on Friday based on data going back to 1982, because of its weak outlook.
在此之前,Alphabet Inc.、Meta Platforms Inc. 和 Amazon.com Inc. 等大型 AI 支出者因其巨额承诺侵蚀现金流,股价也遭到惩罚。
And prior to that, big AI spenders like Alphabet Inc., Meta Platforms Inc. and Amazon.com Inc. have seen their shares punished because their massive commitments are eating away at cash flows.
与 AMD 一样,Intel 今年也是大幅跑赢大盘的股票,因为 AI 支出推动了对其中央处理器(CPU)芯片的需求。在发布财报前,Intel 2026 年累计上涨 150%。但到周一收盘时,该涨幅已缩减至 63%。
Like AMD, Intel had been a significant outperformer this year as AI spending drove demand for its central processing unit, or CPU, chips. Prior to its report, Intel was up 150% in 2026. But by the end of trading on Monday, that gain was cut to 63%.
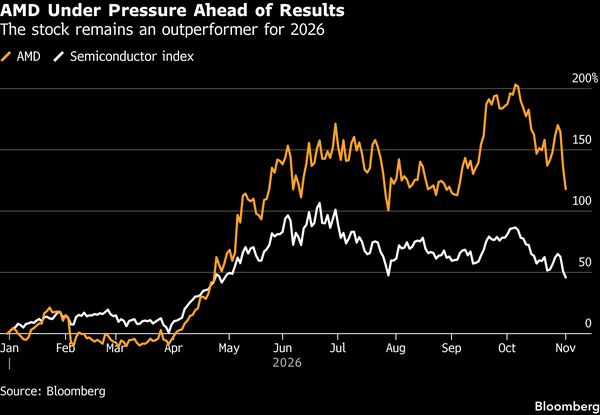
AMD 股价因同情 Intel 而下跌,周五下跌 10%,导致 10 月份累计跌幅超过 17%。但今年以来仍上涨约 118%,远超费城证券交易所半导体指数(即 SOX 指数)46% 的涨幅。
AMD shares have sold off in sympathy with Intel, losing 10% on Friday to close October down more than 17%. But they’re still up about 118% for the year, far outpacing the 46% gain in the Philadelphia Stock Exchange Semiconductor Index, better known as the SOX.
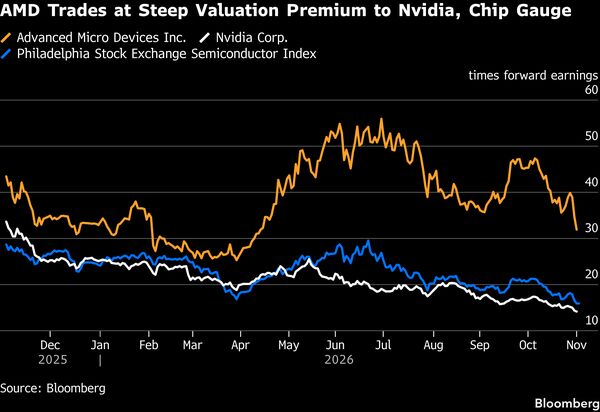
这波上涨使 AMD 股票相较于其他芯片制造商显得相对昂贵。其市盈率为未来 12 个月预估利润的 32 倍,是 SOX 指数中第四高的倍数。这低于 6 月 30 日 56 倍的高点。然而,AMD 向来是一只高估值股票,自 2017 年以来的平均倍数约为 34 倍。
The rally has made AMD’s stock look relatively expensive compared with shares of other chipmakers. It’s trading at 32 times profits estimated over the next 12 months, which is the fourth-highest multiple in the SOX. That’s down from a high of 56 on June 30. However, AMD is traditionally a pricey stock, with an average multiple of around 34 since 2017.
华尔街分析师预计,AMD 第三季度盈利将激增 92%,营收将增长 41%,且这两项指标预计将在 2027 年进一步增加。首席执行官苏姿丰上个月表示,公司预期未来几年将出现“非常高”的芯片需求,且需求将超过供应。
Wall Street analysts expect AMD to report a 92% jump in third-quarter earnings on a 41% rise in revenue, and both figures are projected to increase further in 2027. The company is anticipating “very high” chip demand that exceeds supply over the coming few years, Chief Executive Officer Lisa Su said last month.
CPU 在 AI 基础设施中发挥着关键作用,因为它们对所谓的智能体运行至关重要,而智能体因 Meta 的 Muse 取得成功而风靡市场。根据彭博汇编的数据,这些芯片占 AMD 2025 年营收的近四分之一。
CPUs play a critical role in AI infrastructure because they’re crucial to the functioning of so-called agents, which have taken the market by storm thanks to the success of Meta’s Muse. The chips were responsible for nearly a quarter of AMD’s 2025 revenue, according to data compiled by Bloomberg.
根据彭博汇编的供应链数据,Meta 是 AMD 第二大客户,贡献了这家芯片制造商 5.5% 的营收。Muse 的流行促使一些分析师上调了对该芯片制造商的目标价,Rosenblatt Securities 分析师 Kevin Cassidy 将其评为财报发布前的最佳长线投资标的。
Meta is AMD’s second-largest customer, accounting for 5.5% of the chipmaker’s revenue, according to supply chain data compiled by Bloomberg. Muse’s popularity has led some analysts to raise their targets for the chipmaker, which was named the top long idea going into earnings by Rosenblatt Securities analyst Kevin Cassidy.
Allspring 的 Javeri 表示:“投资者需要看到增长加速的证据,而 Muse 绝对是一个可信的催化剂。”
“Investors need to see evidence that growth is accelerating, and Muse absolutely is a credible catalyst,” Allspring’s Javeri said.
这解释了为什么华尔街对 AMD 2027 年净利润的共识预期在过去三个月里上升了 23%,营收预期上升了 14%,且 2028 年的增幅预期甚至更强。根据彭博追踪的分析师平均目标价,该股票预计在未来 12 个月内将上涨 40%。
This would explain why Wall Street’s consensus expectations for AMD’s 2027 net income have risen 23% over the last three months and estimates for revenue are up 14%, with even stronger gains seen in 2028. The stock is expected to rise 40% over the next 12 months based on the average of analysts’ price targets tracked by Bloomberg.
AMD 在发布财报前面临的最大风险,可能是围绕 AI 交易的情绪恶化,以及投资者对任何失望表现的紧张不安。过去两周 AI 超大规模厂商在财报中对 AI 资本支出的负面反应,引发了对支出收缩的担忧,这将深刻影响 AMD 等依赖这种慷慨支出持续的芯片制造商。
The biggest risk for AMD heading into its report may be the deteriorating sentiment around the AI trade and investors’ skittishness about any disappointment. The negative reaction to AI capital expenditures in the earnings reports by AI hyperscalers over the past two weeks is raising fears of a spending pullback, which would deeply affect chipmakers like AMD that are relying on that largesse continuing.
Wealth Consulting Group首席投资官Jim Worden因前景不明朗及股价估值过高而卖出了AMD持仓,但他继续持有英伟达、博通和台积电等其他芯片制造商的股票。
Jim Worden, chief investment officer at the Wealth Consulting Group, exited his AMD position because of the uncertain backdrop and the stock’s high valuation, but he continues to hold other chipmakers like Nvidia Corp., Broadcom Inc. and Taiwan Semiconductor Manufacturing Co.
他说:“我们可能正处于一个AMD从良性增长转向超高速增长的时期,Muse等因素可能成为加速器,但我对目前的估值就是不太放心。问题实在太多了。”
“It’s possible we’re in a period where AMD goes from good growth to hypergrowth, with things like Muse acting as an accelerator, but I’m just not super comfortable with the valuation,” he said. “There are just too many questions.”