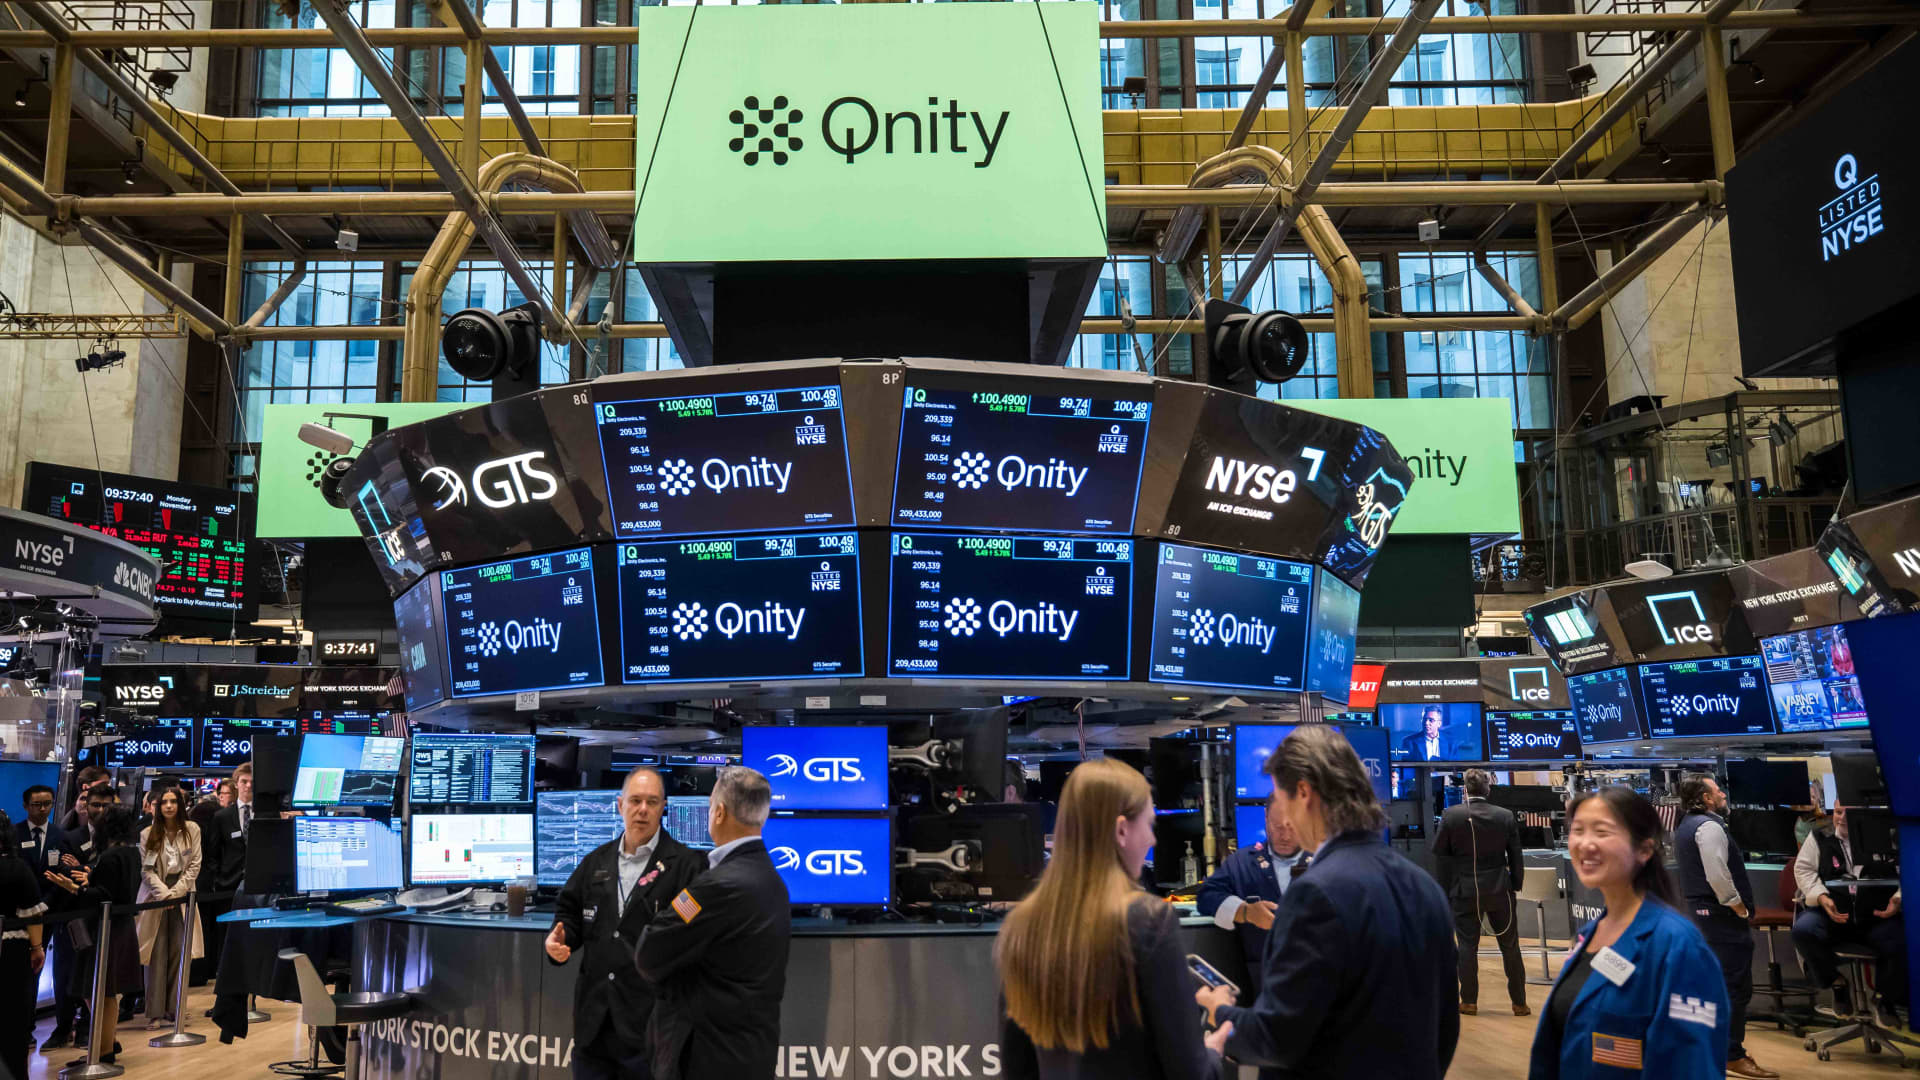
半导体供应链关键环节 Qnity Electronics(以下简称“Qnity”)在周三开盘前公布了一份超预期且上调指引的季度财报。该股早盘一度跌近 6% 至盘中低点,但随后收复了大部分跌幅。第三季度营收同比增长 22% 至 15.6 亿美元,超越 LSEG 汇总的分析师共识预期 14.9 亿美元。经调整每股收益(EPS)激增 55% 至 1.46 美元,同样高于预期的 1.20 美元。
Qnity Electronics , a crucial link in the semiconductor supply chain, reported a nice beat-and-raise quarter before Wednesday's open. The stock fell nearly 6% to session lows mid-morning but erased most of those losses later in the day. Revenue in the third quarter increased 22% from a year ago to $1.56 billion, outpacing the $1.49 billion LSEG-compiled analyst consensus estimate. Adjusted earnings per share (EPS) surged 55% to $1.46, also above the $1.20 expected.
Qnity 生产许多芯片制造必不可少的专用化学品和材料。在国会山中期选举民主党大胜后,芯片制造商和芯片设备供应商承压,Qnity 早盘下跌并不令人意外。这股“蓝色浪潮”被视为人工智能繁荣的逆风因素。
Qnity makes many of the specialized chemicals and materials that are essential to chip manufacturing. With chipmakers and chip equipment providers under pressure following the midterm Democratic sweep on Capitol Hill, it was not surprising to see Qnity initially lower. The blue wave is seen as a headwind for the artificial intelligence boom.
Q 1Y mountain Qnity Electronics 1-year performance然而,Jim Cramer 并不把选举结果视为非黑即白的事件,因为对半导体所赋能的算力的需求依然强劲。我们在财报发布前就将 Qnity 视为买入标的,Jim 在俱乐部早盘会议上表示,财报后的回调让该股看起来更具吸引力。底线是:Qnity 实现了连续第十个季度盈利增长,这一纪录可追溯至公司还在杜邦旗下的时期。
Q 1Y mountain Qnity Electronics 1-year performance Jim Cramer, however, doesn't view the election result as a binary event because there is still so much demand for the computing power that semiconductors enable. We saw Qnity as a buy before the quarter, and Jim said on the Club's Morning Meeting that Qnity's post-earnings drop makes the stock look even more enticing. Bottom line Qnity delivered its tenth consecutive quarter of profitable growth, a streak dating back to the company's days under the DuPont umbrella.
Qnity 从杜邦分拆上市刚刚超过一年。该股于 2025 年 11 月 3 日首日收于 97 美元,此后累计上涨逾 20%。期间股价曾于 6 月下旬飙升至 177 美元以上的历史高点,随后在夏季回落。分拆股在寻找投资者基础过程中出现大幅波动并不罕见。虽然本季度表现强劲,但 Qnity 的全年展望更为强劲。管理层上调营收和盈利指引,远超预期。这让我们更有信心,Qnity 不会因任何与选举相关的数据中心反弹而受到太大阻碍。
Qnity was spun off from DuPont a little over one year ago. The stock closed at $97 on its debut on Nov. 3, 2025, and is up more than 20% since then. Along the way, shares soared to all-time highs above $177 in late June before a summer swoon. It's not uncommon to see big swings in spinoff stocks as they find an investor base. While the quarter was strong, Qnity's full-year outlook was even stronger. Management raised guidance for sales and earnings that far exceeded expectations. That makes us feel more confident that Qnity won't be held back much by any election-related data center backlash.
民主党控制众议院和参议院将使 AI 基础设施资金更难获得,这对需要尽快建设以产生借贷资本回报的亏损新云厂商构成问题。CoreWeave 再度下跌 10%。然而,数据中心建设放缓可能利好超大规模云服务商,如亚马逊,后者曾是自由现金流机器。在市场力量驱动下,尽管 CEO 可能希望加快投资步伐,但它们不得不放缓投资节奏,自由现金流有望反弹。
Sure, Democrats controlling the House and Senate will make AI infrastructure funding more difficult, which is problematic for money-losing neoclouds that need to build as quickly as possible to generate a return on their borrowed capital. CoreWeave was down another 10%. However, slower data center construction could bode well for the hyperscalers, such as Amazon , which were once free cash flow machines. With market forces driving them to curtail the pace of investment, despite what the CEOs may want, free cash flow has a chance to rebound.
这就是为什么亚马逊周三上涨逾 7%。但这也是为什么 Qnity —— 这家“供应商的供应商” —— 尽管发布了积极财报,股价却可能下跌。尽管如此,我们认为总体 AI 需求依然非常真实,并将 Qnity 这类为整个半导体行业提供关键基石的公司股价走弱,视为长线投资者应当寻找的机会。归根结底,来自消费者和企业的 AI 需求正在增加 —— 以及随之而来的对 Qnity 的需求。
That's why Amazon was up more than 7% on Wednesday. But it's also why Qnity, which is a "supplier to the suppliers" of AI infrastructure, can trade lower on the back of such a positive release. Nonetheless, we think AI demand in aggregate is still very real and view any weakness in a name like Qnity, which provides the crucial building blocks for the entire semiconductor industry, as exactly what longer-term investors should be looking for. Ultimately, the demand for AI from consumers and enterprise alike is increasing — and with it, demand for Qnity.
我们最近前往 Qnity 波士顿郊外的实验室,实地拍摄了其科学家如何制造和测试产品的视频。鉴于 Qnity 季度表现强劲且前景稳健,我们重申买入等同的 1 级评级。不过,我们将目标价从 180 美元下调至 165 美元,以反映半导体板块面临的压力。即便如此,我们的新目标价依然看涨,意味着较当前水平有 38% 的上涨空间。
We recently went to the company's labs outside Boston for a video tour of how its scientists make and test the products. Given Qnity's quarterly strength and robust outlook, we're reiterating our buy-equivalent 1 rating . However, we're lowering our price target to $165 from $180 to reflect the pressure on semiconductors. Still, our new PT is bullish, implying 38% upside from current levels.
季度点评Qnity 第三季度全线表现强劲。按报告基准和有机基准计算,销售额均增长 22%。看到强劲的有机增长总是令人欣慰,因为它代表了公司无需依靠并购、凭自身能力拓展业务的能力。
Quarterly commentary Qnity's third quarter was strong across the board. Sales increased 22% on a reported basis and organically. It's always nice to see strong organic growth because it represents a company's ability to expand its businesses on its own without the help of mergers or acquisitions.
在业绩电话会上,首席执行官 Jon Kemp 指出了几个推动 Qnity 增长的重要行业趋势,包括 DRAM(动态随机存取存储器)制造的产能利用率处于“80% 高位区间”,以及 NAND(闪存)生产的产能利用率持续改善至“80% 低位至中位区间”。这比去年同期有所改善。存储芯片制造工厂以更高的产能利用率运行,意味着对 Qnity 那些在生产过程中不可或缺的产品需求更大。
On the earnings call, CEO Jon Kemp noted several important industry trends powering Qnity's growth, including capacity utilization in DRAM manufacturing in the "high 80% range" and continued improvement in NAND production in the "low- to mid-80s." That's an improvement from this time last year. So, memory manufacturing facilities operating at higher rates of their capacity means more demand for Qnity's products that are integral to the production process.
DRAM 是短期记忆,NAND 是长期记忆。两者对运行数据中心都至关重要。由于海量的 AI 需求,全球出现了存储芯片短缺,这让生产这些芯片的公司满负荷运转。
DRAM is short-term memory, and NAND is long-term memory. Both are key to running data centers. There has been a global shortage in memory due to massive AI demand, which has the companies making those chips working flat out.
除了效率提升,Kemp 表示,他的团队正在关注明年针对的 15 多座先进制造设施。“设备安装完毕后,工艺认证可能需要 12 到 18 个月。随后,随着客户向满产冲刺,材料需求会逐步增加。”他将 AI 基建视为“多年机遇”。此外,首席执行官还表示,AI 正“超越数据中心,延伸至工厂自动化、航空航天与国防、自动驾驶等领域的物理人工智能”。
In addition to efficiency improvements, Kemp said his team is monitoring more than 15 advanced manufacturing facilities targeted for the next year. "Once equipment is installed, process qualifications can take 12 to 18 months. From there, materials demand builds as customers ramp toward full capacity." He sees the AI buildout as a "multiyear opportunity." Additionally, the CEO said that AI is "broadening beyond data centers into physical artificial intelligence across factory automation, aerospace and defense, and autonomous driving."
公司在两大运营板块——半导体技术和互联解决方案——均实现了好于预期的营收增长。第三季度盈益得益于两大板块同比大幅扩张的利润率。Qnity 最大的客户是三星电子和台湾积体电路制造公司。它还与俱乐部成员股英伟达和苹果合作。今年 3 月,Qnity 与英伟达合作,共同开发半导体材料和先进封装。同月稍晚,苹果扩大了在美国拓展制造业务的力度,新增多家合作伙伴,其中包括 Qnity。Qnity 将为 iPhone 18 Pro 相机系统的新款可变光圈生产技术。
The company delivered better-than-expected topline growth in both operating segments, Semiconductor Technologies and Interconnect Solutions . Earnings in the third quarter benefited from strong year-over-year margin expansion in both segments. Qnity's biggest customers are Samsung Electronics and Taiwan Semiconductor Manufacturing Company . It also works with fellow Club names Nvidia and Apple . Back in March, Qnity partnered with Nvidia to co-develop semiconductor materials and advanced packaging. Later that month, Apple widened its push to expand manufacturing in the United States, adding several new partners, including Qnity. Qnity will produce technology for the new variable aperture in the iPhone 18 Pro camera system.
在半导体技术业务部门,该部门帮助客户制造计算机芯片和电子设备,管理层指出先进制程节点实现了25%的增长,即精密制造工艺,且公司的半导体设备耗材业务——主要是Kalrez——表现强劲,Kalrez是一种特种密封材料,用于从电子、航空航天到能源等各行各业的产品中。在互联解决方案业务部门,该部门解决包括能效、散热管理、信号完整性和长期可靠性在内的性能挑战,销售受益于散热管理、先进封装和AI印刷电路板的强劲表现,以及来自数据中心、工业和高端消费电子终端市场的持续需求。
In Semiconductor Technologies , which helps its customers build computer chips and electronic devices, management called out 25% growth in advanced nodes, or precision manufacturing processes, and strong performance from the company's semiconductor equipment consumables business — primarily Kalrez, which is a specialty sealing material used in products from a variety of industries, from electronics to aerospace to energy. In Interconnect Solutions , which addresses performance challenges, including power efficiency, heat management, signal integrity, and long-term reliability, sales benefited from strength in thermal management, advanced packaging, and AI printed circuit boards, as well as sustained demand from data center, industrial,m and premium consumer electronics end markets.
坎普表示:“散热管理是我们增长最快的平台,已成为AI性能的基础。例如,随着更强大的逻辑芯片和存储模块被紧密封装进AI应用中,热量迅速积聚,可能限制性能和可靠性。我们广泛的产品组合可在每一层级管理热量,从芯片和存储组件到电路板及更广泛的系统,这为我们提供了更多机会,帮助客户优化系统效率并最大化AI算力。”
Kemp said, "Thermal management is our fastest-growing platform and has become fundamental to AI performance. For example, as more powerful logic chips and memory modules are tightly packed into AI applications, heat builds quickly and can limit performance and reliability. Our expansive portfolio manages heat at every level, from the chip and memory components to the board and broader system, giving us more opportunities to help customers optimize system efficiency and maximize AI compute."
这与我们本周从伊顿公司的财报电话会上听到的关于该公司收购博伊德热管理公司(Boyd Thermal)的95亿美元交易的情况相吻合。周二,伊顿报告了一个强劲的季度并上调了全年业绩指引。Guidance Qnity利用第三季度的强劲表现上调了全年展望。该公司预计销售额为57.7亿至58.3亿美元,较此前指引的中值增加2亿美元,且领先于LSEG统计的56.5亿美元共识预估中值。
This aligns with what we heard from Club name Eaton during this week's earnings call concerning the company's $9.5 billion acquisition of Boyd Thermal. On Tuesday, Eaton reported a strong quarter and raised full-year guidance. Guidance Qnity used the Q3 strength to raise its full-year outlook. The company expects sales of $5.77 billion to $5.83 billion, a $200 million increase at the midpoint from the previous guide and ahead of the $5.65 billion consensus estimate at the midpoint, according to LSEG.
该公司预计调整后运营EBITDA为17.9亿至18亿美元,较此前指引的中值增加9500万美元,且高于FactSet统计的17.1亿美元共识预估。
The company expects adjusted operating EBITDA of $1.79 billion to $1.8 billion, a $95 million increase at the midpoint and above the $1.71 billion consensus estimate, according to FactSet.
EBITDA 是息税折旧摊销前利润的英文缩写。根据 LSEG 数据,该公司预计调整后每股收益为 4.95 美元至 5.05 美元,中位数较此前上调 0.50 美元,并高于 4.56 美元的市场共识预期。根据 FactSet 数据,该公司预计调整后自由现金流为 8 亿美元至 9 亿美元,中位数较此前上调 2 亿美元,并高于 5.55 亿美元的市场共识预期。(吉姆·克莱默慈善信托基金持有 Q、AMZN 的多头头寸。)
EBITDA stands for earnings before interest, taxes, depreciation, and amortization. The company expects adjusted EPS of $4.95 to $5.05, a 50-cent increase at the midpoint and ahead of the $4.56 consensus estimate, according to LSEG. The company expects adjusted free cash flow of $800 million to $900 million, a $200 million increase at the midpoint and above the $555 million consensus estimate, according to FactSet. (Jim Cramer's Charitable Trust is long Q, AMZN. )