数据中心建设商可能面临大幅上升的借贷成本,因为数十亿美元的债务将在未来几个月到期,这是美国基准收益率上升的副产品,恐将使为人工智能行业扩张融资的成本更加高昂。
Data center builders may face significantly higher borrowing costs when billions of dollars in debt comes due in the months ahead, a byproduct of rising benchmark US yields that threatens to make financing the AI industry’s expansion that much more expensive.
根据彭博新能源财经的一份新报告,预计约134亿美元的未偿还固定利率美元计价债务将于2027年到期。报告发现,如果这些债务完全按2026年10月的现行美国国债收益率进行再融资,开发商将面临债务利率上升2.85个百分点的局面——使费用至少增加3.8亿美元。这假设信用利差保持不变。
Some $13.4 billion of outstanding fixed-rate, dollar-denominated debt is expected to mature 2027, according to a new report by BloombergNEF. If that debt were fully refinanced based on prevailing Treasury yields as of October 2026, developers would face a 2.85 percentage-point surge in the interest rates on their debt — increasing expenses by at least $380 million, the report found. That’s assuming credit spreads stay the same.
更广泛地说,报告发现,未来五年内至少有1万亿美元的数据中心借款将到期。到2030年到期的大部分债务集中在八家公司手中,包括开发商Vantage Data Centers、Switch和Databank,这三家公司到期债务量最大。
More broadly, at least $1 trillion of data center borrowings are maturing within the next five years, the report found. Most of the debt maturing by 2030 is concentrated among eight firms, including developers Vantage Data Centers, Switch and Databank, which have the largest volume of debt maturing.
与任何在利率高企时期寻求筹资的借款人一样,数据中心开发商需要做好准备,仅基于基准收益率就可能面临更高的融资成本。虽然美国国债收益率在未来几个月可能会下降,但这些公司还面临其他可能影响其债务融资利率的压力,包括人们对其巨额债务负担的日益担忧,以及被认为过度依赖超大规模云服务商和芯片制造商的财务支持。
Like any borrower looking to raise money at a time of elevated rates, data center developers will need to be prepared for a potentially higher cost of financing based on benchmark yields alone. While Treasury yields could decline in the months ahead, these companies also face other pressures that may influence the rates they’re asked to pay on their debt, including growing concerns over their large debt loads and perceived overreliance on financial support from hyperscalers and chipmakers.
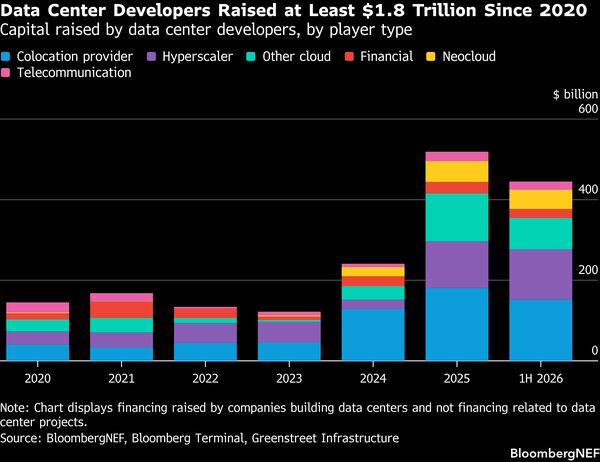
根据报告,银行在选择向哪些开发商放贷方面也变得更加挑剔,这可能限制信贷供给,进一步减少开发商的再融资能力或提高其借贷成本。
Banks are also becoming more selective about which developers to lend to, which could limit credit availability and further reduce refinancing capacity or raise costs for developers to borrow, according to the report.
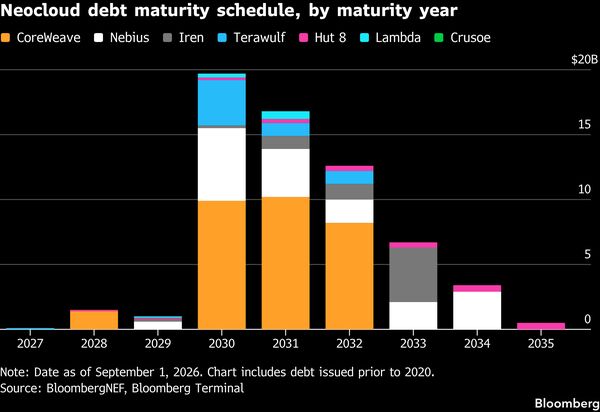
所谓的“新云”企业面临从2030年开始集中的再融资压力。报告发现,这些企业在2030年至2032年间有约490亿美元债务到期,约占截至2026年9月未偿还“新云”借款总额的65%。报告发现,为人工智能用途采购并出租芯片的科技公司CoreWeave和Nebius Group NV占这些到期债务的80%。
So-called neoclouds face a concentrated refinancing pressure starting in 2030. Some $49 billion of their debt matures between 2030 and 2032, or about 65% of total outstanding neocloud borrowings as of September 2026, the report found. CoreWeave and Nebius Group NV, tech firms that buy and lease out chips for use in artificial intelligence, account for 80% of those maturities, the report found.
CoreWeave现有债券近几周已遭遇一波抛售潮,导致价格暴跌、收益率飙升至高达15%。本周,在主张放缓数据中心建设的民主党候选人在包括得克萨斯州在内的多个州长选举中获胜后,该公司债券再度大跌。
CoreWeave’s existing debt has already been hit with a wave of selling in recent weeks, sending prices plunging and yields soaring to as high as 15%. This week, the company’s bonds tumbled anew after Democratic candidates in favor of slowing down data center construction won a number of gubernatorial races, including in Texas.
与此同时,报告发现,从比特币挖矿转型为AI开发商的企业,如Terawulf Inc.和Crusoe,正面临大量建设债务。报告指出,总体而言,项目一直在应对更长的并网排队和熟练劳动力短缺问题,这可能推迟租金收入,若延误持续,将使开发商更难偿还或再融资贷款。
Meanwhile, Bitcoin mining-turned-AI developers such as Terawulf Inc. and Crusoe are contending with large amounts of construction debt, the report found. Projects, in general, have been dealing with longer interconnection queues and skilled labor shortages, which could postpone rental income and make it harder for developers to repay or refinance loans if the delays are prolonged, per the report.