尔·巴伊戈里短短48小时内,Firmus Grid Ltd.便从人工智能数据中心领域的后起之秀,沦为近年来最失败的IPO案例之一。
In 48 hours, Firmus Grid Ltd. went from a rising star of the artificial intelligence data center boom to one of the biggest deal flops in recent memory.
数月来,这家获得英伟达公司支持的企业一直标榜自己是人工智能领域的核心投资标的,眼看就要完成澳大利亚有史以来规模最大的IPO之一,其估值也足以跻身行业前十行列。然而,当银行家们寄予厚望的美国基金经理们开始仔细审视这家公司时,这一切美好预期便瞬间破灭。
After months of touting itself as an essential artificial intelligence play, the Nvidia Corp.-backed company was on the cusp of pulling off one of Australia’s biggest-ever initial public offerings at a valuation fit for a top 10 player in the industry. But that story wilted under the scrutiny of US fund managers that bankers were counting on to buy a chunk of the deal.
截至悉尼时间周二晚间,投行团队接连收到多家基金发来的相同反馈:Firmus所要求的300亿美元估值实在过高。到了周三清晨,显然此次IPO无法按原计划推进,于是各方紧急商讨补救方案,包括下调发行价或缩减募资规模。但最终,这笔交易还是宣告失败。
Through Tuesday night Sydney time the deal team kept getting the same message from one fund after the other: the $30 billion valuation Firmus sought was just too rich. By Wednesday morning, it became clear that the IPO wouldn’t fly as pitched, prompting frenzied brainstorming to try to salvage it, with a cut in the price or the size. Ultimately, the deal collapsed.
本文内容基于多位知情人士的讲述,出于保密考虑他们要求匿名。Firmus公司方面则拒绝置评。
The story is based on multiple conversations with people close to the situation who asked not to be identified citing confidentiality. A representative from Firmus declined to comment.
最初,外界开始意识到此次IPO面临重重阻力,是因为有消息称现有股东无需遵守托管协议,可能大量抛售股票冲击市场。当时,许多投资者仍被有关市场需求旺盛的乐观言论所安抚。
Major headwinds first became clear to the wider public when news emerged earlier that existing shareholders wouldn’t be subject to an escrow agreement and could potentially flood the market. At that point, many investors were still reassured by the optimistic messages about demand.
然而到了周三,手机推送的新闻开始充斥着需求疲软及可能降价的消息。一位基金经理不得不匆忙中断在香港一家咖啡馆的会议去核实情况。当天下午,投资者们都在绞尽脑汁试图弄清此次IPO究竟出了什么问题,整个夜晚也变得漫长难熬。
But by Wednesday, headlines were popping up in phone alerts about weak demand and a potential price cut. One fund manager had to abruptly abandon a meeting at a coffee shop in Hong Kong to run checks. That afternoon turned into an endless evening as investors tried to figure out what was really going on with the deal.
此时,银行家们已全面进入紧急救援模式,因为他们清楚地意识到:这个内部代号为“Australis”的交易项目,按原定规模根本无法顺利推进。于是有人提议将融资规模缩减至约30亿美元,同时将公司估值定在200亿至250亿美元之间。周三晚间,该公司及其顾问团队全员出动,试图说服美国投资者以较低价格认购规模缩小的交易项目,但一切努力均徒劳无功。
By that time, bankers were in full rescue mode as it was clear to them that the deal — running under the internal code name ‘Australis’ — wouldn’t work at the proposed size. Ideas were floated to cut it to about $3 billion and the valuation to somewhere between $20 billion and $25 billion. Wednesday night was all hands on deck for the company and its advisers to convince US investors to buy into the smaller deal at a lower price, all to no avail.
美国银行、摩根大通、摩根士丹利以及Morgans Financial Ltd.共同担任此次IPO的联席主承销商。摩根士丹利发言人拒绝置评,其他几家银行的代表也未回应置评请求。
Bank of America Corp., JPMorgan Chase & Co., Morgan Stanley and Morgans Financial Ltd. were acting as joint lead managers on the IPO. A spokesperson for Morgan Stanley declined to comment, and representatives for the other banks didn’t respond to requests for comment.
外界信息匮乏令市场情绪愈发紧张,且短期内难以缓和。周四上午11点刚过,澳大利亚方面按计划结束了股票认购程序,但此时市场上已弥漫着担忧情绪:该公司似乎未能获得足够支持来实现原定每股11澳元的发行价。直至认购结束,发行价格及交易结构仍无定论。
On the outside, a dearth of information kept people on edge, and it wouldn’t get better for a while. Shortly after 11 a.m. Thursday in Australia, the bookbuilding was closed as scheduled, but by then there was swirling concern that the company failed to attract adequate support for the A$11 marketed share price.
市场焦虑情绪日益加剧的一个迹象是:作为Firmus背后的支持企业,Maas Group Holdings Ltd.的股价在悉尼交易所一度暴跌30%,创下历史最大单日跌幅。
Even at the time of closing, there was no clear indication of the price or the deal structure.
众多寻求最新动态的基金经理们陷入茫然:部分人减少了认购订单,另一些人则察觉到IPO前景堪忧,干脆完全取消了订单。
In a sign of the mounting concern, shares of Firmus backer Maas Group Holdings Ltd. dipped as much as 30% in Sydney, the most on record.
就在此时,Ten Cap Investment的联合创始人兼首席投资组合经理刘俊贝在彭博电视上被问及该交易项目。她表示:“我从未见过如此引发两极分化的IPO。”她还补充道,如果上市失败,这家数据中心运营商将直接向现有支持方寻求融资。
Fund managers seeking updates were left hanging; some shrank their orders while others pulled them completely upon sensing the IPO was in trouble. It was around that time that Jun Bei Liu, co-founder and lead portfolio manager at Ten Cap Investment, was asked about the deal on Bloomberg TV. “I’ve never seen an IPO so polarizing,” she said, adding that the data center operator would go straight to its existing backers to raise money if the listing fails.
投资者对人工智能基础设施建设所需资金的担忧日益加深,这在一定程度上解释了市场的疑虑情绪,尤其是对于那些缺乏成功业绩记录的企业而言。这也引发了人们的疑问:该公司及其顾问团队为何会对市场需求做出如此严重的误判?
Growing investor nervousness about the funding needs of the AI buildout explain some of the skepticism, particularly for firms without a proven track record. It also raises questions about how the company and its advisers got the demand so wrong.
在Firmus宣布IPO定价时称“战略投资者及全球投资者需求旺盛”,且投行方面也表示认购需求远超发行规模后,情况出现了戏剧性转折。不过,许多投资者长期以来一直对该公司及其估值持怀疑态度。
It was an abrupt turn after Firmus claimed “strong strategic and global investor demand” as it priced the IPO and bankers said indications were in excess of the offer size. But many investors had long been skeptical about the company and its valuation.
澳大利亚规模最大的养老基金之一UniSuper早在7月份就表示不会参与此次IPO,理由是对该公司的业务情况了解甚少。
UniSuper, one of Australia’s largest pension funds, said as early as July that it would not participate in the IPO, saying too little was known about its business.
当时Firmus正处于发展势头良好的阶段,估值也相对较低。不久之后,该公司完成了20亿美元的融资,估值升至105亿美元以上,Jane Street Group与黑石集团等行业巨头纷纷参与投资。这一估值水平较4月份由Coatue Management LLC与英伟达牵头进行的融资时高出一倍有余——当时该公司的估值仅为55亿美元。
That was at a time when Firmus was riding high and its valuation was much lower. Not long after, the company closed a $2 billion funding round at a valuation of more than $10.5 billion, attracting heavyweights such as Jane Street Group and Blackstone Inc. It was a huge leap from an earlier round in April with Coatue Management LLC and Nvidia that valued the company at $5.5 billion. But the IPO valuation was another major jump, one that didn’t survive the more exacting scrutiny of the public process.
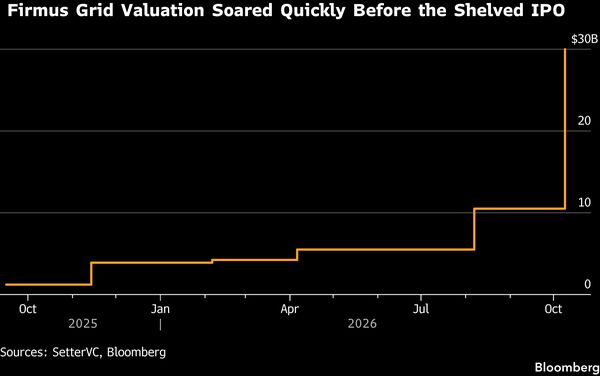
然而此次IPO的估值水平又出现了大幅提升,可惜这一估值在公开市场的严格审核下未能维持。
Firmus began formally gauging investor demand for its IPO late September.
9月下旬,Firmus正式开始评估投资者对其IPO的需求。最终确定的估值高达55亿美元,这一数值远超市场预期,显示出该公司试图说服投资者为尚未实现的业绩买单。
At up to $5.5 billion, it was already a lot larger than expected, showing the company was looking to convince investors to pay up for results that had not yet materialized. Prospective investors, though, saw a business that was still in its early stages, with a lot of execution risk: Of its 912 megawatt pipeline, just 46MW had been built.
但潜在投资者们看到的却是一家仍处于发展初期、面临诸多执行风险的企业:在其规划建设的912兆瓦产能中,实际建成的仅46兆瓦。投资者们被要求基于数据中心能否顺利建成这一前提,来预估公司的未来收益并据此定价。
They were being asked to value the company on future earnings contingent on the data centers being successfully delivered. Firmus pitched an enterprise value-to-earnings before interest and tax multiple, used by neocloud peers such as CoreWeave Inc. in the US.
Firmus还采用了美国同类云服务商CoreWeave Inc.所使用的企业价值与息税前利润比率作为估值依据。尽管这一比率仅为13倍,较CoreWeave的估值水平低了不少,但它所依据的却是两年后的息税前利润预测值。相比之下,CoreWeave不仅发展历史更为悠久,营收规模也远超Firmus。在当前的市场环境下,投资者们实在难以做出如此冒险的押注。
Even if at 13 times it was at a significant discount to CoreWeave, it was based on EBIT forecasts two years down the line. The US company has both a longer track record and revenue that’s several orders of magnitude greater than Firmus’. In the current environment, it was hard to make such a leap of faith. “Poorly structured, too big, terrible prices, silly metrics — had the lot! Worth under $2 billion a year ago, $10 billion in August, then asking for three times that in October,” said Leonid Mironov, portfolio manager at Gavekal Capital Ltd.
“结构混乱、规模过大、定价离谱、评估指标荒唐——问题一个接一个!一年前该公司的估值还不到20亿美元,8月份升至100亿美元,到了10月份却要按300亿美元的价格发行股票,”Gavekal Capital Ltd.的投资组合经理列昂尼德·米罗诺夫说道。
Many investors were nevertheless comfortable with a valuation around $25 billion.
尽管如此,许多投资者仍认为约250亿美元的估值在合理范围内。不过,在IPO定价确定前几天,Firmus宣布与老客户Meta Platforms Inc.达成协议,后者将购买其在东南亚工厂的计算能力。
But a few days before the IPO price was set, Firmus announced an agreement with Meta Platforms Inc., an existing customer, for computing capacity at its factories in Southeast Asia. It revised its numbers on the back of that announcement leading to the IPO price.
受此消息影响,Firmus重新调整了财务预测数据,进而确定了IPO定价。
Some investors saw that as the company pushing the envelope.
部分投资者认为该公司是在刻意抬高估值。按照其设定的增长目标,这家2026财年营收仅为5100万美元的企业竟被要求定出超过300亿美元的估值;而要实现这些目标,公司还需投入目前尚不具备的数十亿美元资金。
They were being asked to value a company that had $51 million in revenue in the 2026 financial year at over $30 billion, based on ambitious growth targets that would require it to spend billions of dollars it didn’t yet have. On top of all that, there was the background of co-founder Oliver Curtis, who served a prison sentence for insider trading a decade ago.
除此之外,联合创始人奥利弗·柯蒂斯十年前曾因内幕交易入狱,这一背景也令投资者心存顾虑。虽然这并未成为阻碍交易的绝对因素,却增加了不少不确定性。澳大利亚媒体上的一些负面报道同样对公司形象造成了负面影响。
While not cited as a deal-breaker, it added an element of caution. Some negative press in the vibrant Australian media also didn’t help. In the end, US investors just didn’t show up as expected and domestic demand wasn’t enough to cover the deal.
最终,美国投资者并未如预期般踊跃参与认购,本土市场需求也不足以支撑此次发行。周五上午,Firmus无奈决定取消IPO,转而寻求与现有投资者进行规模缩小的私募融资——这些投资者原本就计划认购IPO股票的一半份额。
By Friday morning, Firmus bit the bullet. The IPO was pulled and the company instead started exploring a pared-down private funding round with existing investors, who were poised to buy half the IPO shares anyway.