这家流媒体巨头需要证明其能够再次制作出热门电影和电视剧,以阻止今年已抹去超过1350亿美元市值的跌势。
Inc. needs to prove that it can produce hit movies and TV series again to stop a slide that has erased more than $135 billion in market value this year.
这家流媒体巨头将于周二收盘后发布财报,相比于公司的第三季度财报数据,投资者可能更关注内容高管们所说的未来六个月的安排。
The streaming giant reports earnings after the close Tuesday, and investors will likely be more more attuned to what content executives say is coming over the next six months than the company’s third-quarter numbers.
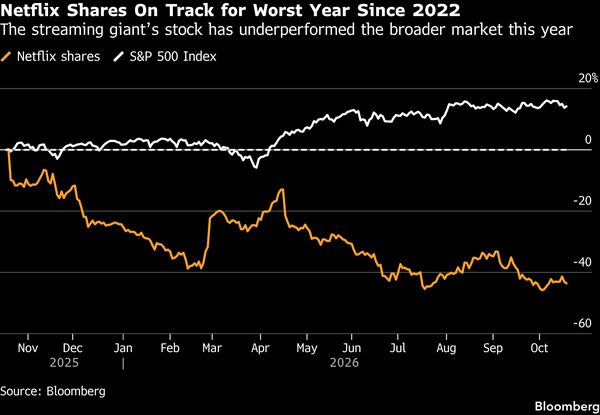
该股票在2026年已下跌26%,使奈飞跻身以科技股为主的纳斯达克100指数中表现最差的10只股票之列,并创下自2022年以来最糟糕的一年,此前它在9月份还经历了一次14%的跌幅。对于任何关注该公司的人来说,原因并不是秘密——尽管在一个拥挤、竞争激烈的娱乐市场推动下进行了大量支出,但由于缺乏受欢迎的内容,用户参与度已经陷入停滞。
The stock is down 26% in 2026, putting Netflix among the 10 worst performers in the technology-heavy Nasdaq 100 Index and on track for its worst year since 2022, and it’s coming off a 14% decline in September. The reason is no secret to anyone following the company — user engagement has stalled due to a lack of popular content despite heavy spending driven by a crowded, competitive entertainment landscape.
联席首席执行官泰德·萨兰多斯表示,奈飞今年赢得的艾美奖数量创下了十年来的最低纪录,且公司的增长速度不够快。
Netflix won the fewest Emmy Awards in a decade this year, and the company isn’t growing fast enough, according to Co-Chief Executive Officer Ted Sarandos.
马霍尼资产管理公司的肯·马霍尼表示:“内容变得非常昂贵,而且玩家依然太多。我认为外面有那么多比奈飞更好的科技故事,它们拥有黏性极高的客户。”奈飞正在采取措施改善其内容并提高观众数量。周二,该公司宣布其电影部门负责人丹·林将离职,上周则用前华特迪士尼电视董事长彼得·赖斯取代了首席内容官贝拉·巴贾里亚。该公司还计划在全球各个部门裁员约1000个岗位,以此来降低成本。
“The content’s getting very expensive, and there’s just still too many players,” said Ken Mahoney of Mahoney Asset Management. “I think there’s so many better tech stories out there than Netflix that have sticky customers.”Netflix is taking steps to improve its content and raise its audience numbers. On Monday, it announced that the head of its film division, Dan Lin, was leaving, and last week replaced its chief content officer, Bela Bajaria, with Peter Rice, the former chairman of Walt Disney Television. The company also plans to cut about 1,000 positions in various departments globally in a bid to reduce costs.
然而,对投资者而言,问题在于这份财报不会反映出这些举措。彭博行业研究分析师吉塔·拉加纳坦表示,即便高管们给出了稳健的营收展望,也不大可能平息围绕参与度的争论。
For investors, however, the issue is this earnings report won’t reflect those moves. And even if executives give a solid revenue outlook, it’s unlikely to quell the debate around engagement, according to Bloomberg Intelligence analyst Geetha Raganathan.
她在10月19日的一份报告中写道:“第四季度更强大的作品阵容可能会恢复观看量和广告,但投资者需要证据来证明参与度能够在不脱离利润率扩张轨道的情况下得到改善。”她补充说,赖斯的加入标志着潜在的战略转向,将倾向于“更多优质的、引发讨论的原创内容以及更高的2027年内容支出”。
“A stronger 4Q slate could revive viewing and ads, but investors will want proof that engagement can improve without derailing margin expansion,” she wrote in an Oct. 19 note. The addition of Rice signals a potential pivot toward “more premium, conversation-driving originals and higher 2027 content spending,” she added.
根据彭博社汇编的数据,跟踪该公司的分析师预计其第三季度营收将增长12%,达到129亿美元,盈利将跃升39%,至每股82美分。其毛利率预计为51%,较第二季度略有下降。
Analysts following the company expect it to report a 12% rise in revenue in the third quarter to $12.9 billion, and a 39% jump in earnings to 82 cents a share, according to data compiled by Bloomberg. Its gross margin is expected to be 51%, down slightly from the second quarter.
华尔街总体上仍看好该股票,平均目标价约为92美元,暗示未来12个月有32%的涨幅。尽管由于过去一个月有两位分析师将该股票评级下调至卖出相当水平导致市场情绪减弱,但多头们看到了市场氛围的转变。
Wall Street remains generally bullish on the stock, with an average price target of about $92 suggesting a 32% rise over the next 12 months. And while sentiment has weakened, with two analysts putting sell-equivalent ratings on the shares in the last month, bulls see a vibe shift coming.
以杰森·赫尔夫斯坦为首的奥本海默分析师在10月14日的一份报告中写道:“虽然整体观看量依然疲软,但质量有所提高,这体现在小时/前十名剧集上,且续集数量正在增加”,并将持续到年底。他们补充说,美国为期三个月的价格上涨和一个月的更高广告费率应该会提振营收,最近的裁员将允许在营销或内容上进行更多支出,或者为利润率带来上行空间。
“While total viewing is still weak, quality has improved as reflected in hour/top-10 title and the number of sequels is increasing” through the end of the year, Oppenheimer analysts led by Jason Helfstein wrote in an Oct. 14 note. Three months of US price increases and one month of higher ad rates should give revenue a boost, and the recent headcount reductions will allow for more spending on marketing or content or provide upside to margins, they added.
Evercore ISI的马克·马哈尼表示,管理层可能会提供一些对其2027年预期的迹象,但该公司不太可能提供详尽的指引。他特别对奈飞最近发布的内容表现出热情。
Management may offer some indications for what it expects in 2027, but the company is unlikely to offer thorough guidance, according to Mark Mahaney of Evercore ISI. He was particularly enthusiastic about Netflix’s recent release of .
马哈尼在10月16日致客户的报告中写道:“对我们来说,看起来非常棒。斯坦贝克回来了!”根据韦德布什公司的阿利西娅·里斯的说法,广告收入对投资者而言可能比观众参与度更重要,她表示该业务板块有望在2026年翻一番,达到约30亿美元。
“ looks very promising to us,” Mahaney wrote in a note to clients on Oct. 16. “Steinbeck is BACK!”Ad revenue may be more important to investors than audience engagement, according to Wedbush’s Alicia Reese, who says the segment is on track to double to roughly $3 billion in 2026.
里斯在10月16日的一份报告中写道:“奈飞正在积极做出改变,这些改变应该既能解决其参与度问题,又能将资金从沉重的基础设施转移到更具针对性的内容支出上。”。
“Netflix is actively making changes that should address both its engagement issues and shift dollars from heavy infrastructure to more focused content spend,” Reese wrote in an Oct. 16 note.
购买该股票的一个理由是估值,考虑到其未来12个月预测盈利的市盈率不到19倍,这是自2022年以来的最低估值,较其49倍的10年平均水平大幅折价。
One argument for buying the stock would be valuation, considering it’s priced at less than 19 times earnings projected over the next 12 months, the lowest valuation since 2022 and a steep discount to its 10-year average of 49.
这有助于解释为什么KeyBanc资本市场分析师贾斯汀·帕特森认为奈飞的看空理由已经体现在股价中了。
That helps explain why KeyBanc Capital Markets analyst Justin Patterson believes the Netflix bear case is already priced into the share price.
他在10月12日的报告中写道:“关于参与度放缓和利润率扩张更温和的看空理由可以说已经完全定价。我们相信管理层已经意识到了这些问题,并期望看到在内容投资和费用重组方面采取纠正行动,以提振增长和盈利,并交付价值。”
“The bear case on slowing engagement and more modest margin expansion is arguably priced in,” he wrote in an Oct. 12 note. “We believe management is aware of these issues, and expect to see corrective action taken across content investment and expense realignment to bolster growth and earnings, and deliver value.”