和 P R Sanjai十年前,穆克什·安巴尼(Mukesh Ambani)旗下的数字业务以免费通话和廉价数据冲击印度电信市场,重创对手。十年后的本周,这家新贵正冲刺一个历史性里程碑——印度有史以来规模最大的首次公开募股(IPO)。
By Chiranjivi Chakraborty and P R Sanjai A decade after storming into the Indian telecom market with free calls and cheap data that decimated its rivals, Mukesh Ambani’s digital venture is aiming for a historic milestone this week with India’s largest-ever initial public offering.
但与 2016 年秋天那场凯旋式的进场不同,当时其激进策略引发价格战,仅留下一家竞争对手盈利;如今安巴尼的这家新军入市姿态更为审慎谦逊。拥有印度最大无线运营商的 Jio Platforms Ltd.(以下简称 Jio Platforms)寻求的估值,比其最近的同行竞争对手 Bharti Airtel Ltd.(巴蒂艾特尔)低约 10%。
But unlike in the triumphant fall of 2016, when its aggressive strategy stoked a price war that left only a single competitor profitable, Ambani’s upstart is coming to the market more cautious and humble. Jio Platforms Ltd., the owner of India’s largest wireless operator, is seeking a valuation that’s roughly 10% lower than its nearest sector rival, Bharti Airtel Ltd.
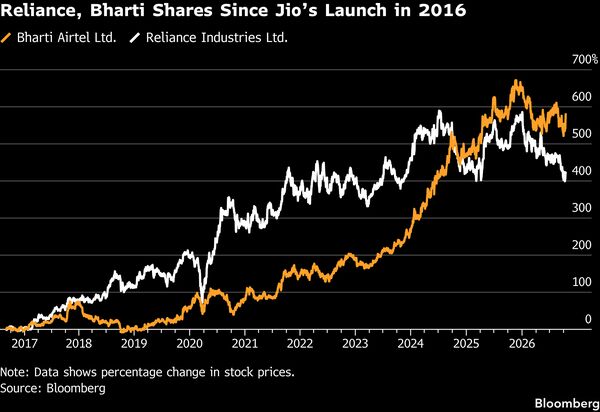
此次上市标志着亿万富翁安巴尼时隔 20 年重返资本市场,他表示此举将为母公司 Reliance Industries Ltd.(信实工业)“释放巨大价值”。但细看之下,图景更为清醒:信实工业股价有望录得自 2011 年以来最差全年表现,这家从能源到娱乐的大型企业集团不得不下调 Jio 估值,以吸引明星投资者。
The listing marks billionaire Ambani’s return to the capital market after 20 years, an offering that he said will “unlock great value” for parent Reliance Industries Ltd. But a closer look paints a more sobering picture. Reliance shares are on track for their worst annual performance since 2011 and the energy-to-entertainment conglomerate had to prune Jio’s valuations to attract marquee investors.
这折射出印度电信行业的过山车般历程:该行业拥有全球最廉价的数据资费套餐和庞大用户群。Jio 估值的调整显示,市场正在快速饱和,投资者现在更青睐单用户收入更高的公司,而非服务更多用户的公司。
It’s a reflection of the roller-coaster ride for the nation’s telecom sector, which features some of the world’s cheapest data plans and a massive user base. Jio’s market value adjustment shows that the market is saturating fast and investors now prefer companies that earn more from each customer over those that service more subscribers.
野村控股(Nomura Holdings Inc.)分析师 Bineet Banka 和 Abhishek Bhandari 在 10 月 10 日的一份报告中写道:“我们认为,上市后 Jio 很可能需要向公众股东展示增长。”他们补充称,Bharti Airtel 仍是他们在该板块的首选,“因其拥有更高比例的高端用户,若电信服务涨价,这应能使其免受降级和用户流失的影响”。
“We believe that, following its listing, Jio will likely need to demonstrate growth to public shareholders,” Nomura Holdings Inc. analysts Bineet Banka and Abhishek Bhandari wrote in a note dated Oct. 10. They added that Bharti Airtel remains their top pick in the sector “due to its higher proportion of premium subscribers, which should insulate it from downtrading and subscriber attrition” if telecom services get costlier.
Jio的首次公开募股(IPO)将于周三向散户投资者开放认购,认购期将于10月23日结束。包括贝莱德公司、富达管理研究公司、资本集团和安联保险在内的锚定投资者,以发行价区间上限认购了总价值8.54亿美元的股份。
Jio’s IPO opens its books for retail investors on Wednesday, for a subscription period that ends Oct. 23. Anchor investors including BlackRock Inc., Fidelity Management & Research, Capital Group and Allianz SE took stakes worth a combined $854 million at the top end of the marketed range.
按发行价区间1065卢比至1119卢比/股的上限计算,Jio这笔31亿美元的股份发行使公司估值达到1070亿美元,而亿万富翁苏尼尔·巴蒂·米塔尔旗下的无线运营商巴蒂艾特尔估值约为1230亿美元。
Jio’s $3.1 billion share sale values the company at $107 billion at the top end of the marketed price range of 1,065 rupees to 1,119 rupees apiece, compared with about $123 billion for billionaire Sunil Bharti Mittal’s wireless operator.
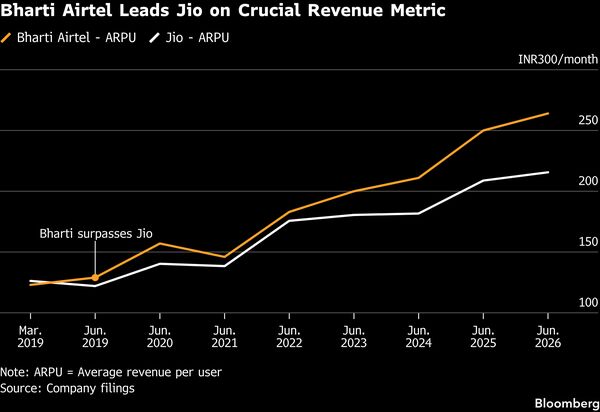
从纸面数据看,Jio在大多数指标上都大于巴蒂艾特尔。它在无线和固定宽带市场均居领先地位,拥有超过5亿用户,并在家庭宽带等尚未充分渗透的新机遇领域领先于巴蒂。但在平均每用户收入(ARPU)这一行业分析师和投资者重点关注的关键指标上,据彭博汇编数据显示,安巴尼旗下的这项业务已连续七年落后于巴蒂。
On paper, Jio is bigger than Bharti Airtel on most counts. It leads in both wireless and fixed broadband markets, boasts more than 500 million subscribers and is ahead of Bharti in new opportunities such as the under-penetrated home broadband. But in average revenue per user, or ARPU — a key metric monitored by sector analysts and investors — Ambani’s venture has lagged Bharti for seven straight years, according to data compiled by Bloomberg.
截至6月结束的季度,巴蒂报告的ARPU为264卢比,而Jio为216卢比——这是其长期坚持的策略所致,即修剪低价值客户,转而青睐需求缺乏弹性、付费能力更强的高价值用户。
For the quarter ended June, Bharti reported an ARPU of 264 rupees, compared with Jio’s 216 rupees — an outcome of its long-standing strategy to prune low-value customers in favor of more inelastic, high-paying users.
利润呈现类似趋势,巴蒂以息税折旧摊销前利润(EBITDA)57.4%的利润率领跑行业,而Jio为53.3%。
Profits show a similar trend as Bharti leads the industry with a 57.4% margin on earnings before interest, tax, depreciation and amortization, compared with 53.3% for Jio.
因此,Jio的市盈率(滚动市盈率)为33.2倍,而巴蒂接近37倍。野村证券和莫提拉尔·奥斯瓦尔金融服务公司基于企业价值与EBITDA之比,给予Jio Platforms高于巴蒂的估值溢价。
As a result, Jio is valued at 33.2 times trailing earnings versus Bharti’s nearly 37 times. Nomura and Motilal Oswal Financial Services Ltd. valued Jio Platforms at a premium to Bharti based on enterprise value-to-Ebitda.
自2016年安巴尼将Jio推向印度曾经竞争异常激烈的电信市场以来,局面已发生巨变。
That’s a long way since Ambani unleashed Jio on India’s once hyper-competitive telecom market in 2016.
延续这位大亨的标志性风格,这家后来者以颠覆者姿态进入,并最终主导了这个碎片化的行业。其推出的首个免费通话和数据服务方案,引发了该国任何行业所见最激烈价格战之一,导致竞争对手退出、合并或面临破产。
In the tycoon’s signature style, the upstart came to disrupt and eventually dominate a fragmented industry. Its inaugural plan of free call and data services kicked off one of the most intense price wars in any sector the country had seen, causing rivals to exit, merge or consider bankruptcy.
这一战略引发了法庭诉讼,竞争对手指责其掠夺性定价 —— 当时的市场领导者巴蒂艾特尔警告称,这将“扼杀整个行业的其余部分并制造垄断”。对穆克什·安巴尼而言,这是他第二次试图在手机业务上取得成功,并遵循父亲的建议,让通话费像明信片一样便宜。他的第一次创业在2005年突然停滞,当时弟弟阿尼尔在一场激烈的继承权争夺战后获得了通信业务板块。
The strategy triggered courtroom battles and accusations of predatory pricing by rivals, with Bharti Airtel — then the market leader — warning it would “kill the rest of the industry and create a monopoly.”For Mukesh Ambani, this was his second attempt at getting mobile phones right and follow his father’s advice to make phone calls as cheap as postcards. Progress on his first venture halted abruptly in 2005, when younger brother Anil ended up with the communication portfolio after an acrimonious succession battle.
2010年,兄弟俩取消了竞业禁止条款,局势发生逆转。穆克什推出了Jio,而阿尼尔的印度信实通讯有限公司无法跟上步伐,最终倒闭。
The balance shifted in 2010, when the brothers scrapped their non-compete clause. Mukesh launched Jio and Anil’s Reliance Communications Ltd. couldn’t keep up, and eventually went under.
Jio推出三年内便登上市场榜首。到2019年夏季,Jio拥有最大的用户群、最大的营收份额,并已准备好投入更多资源以赢得向5G的过渡。据彭博汇编的数据显示,在此期间,该业务为信实工业的股票增加了逾700亿美元的市值。巧合的是,那个夏天也标志着巴蒂艾特尔的转折点。
Within three years of Jio’s launch, it was at the top of the market. By the summer of 2019, Jio had the biggest user base, the biggest share of revenues and was primed to invest more to win the transition to 5G. In that time, the venture had added over $70 billion in market value to Reliance’s shares, Bloomberg-compiled data show. Coincidentally, that summer also marked the point of turnaround for Bharti Airtel.
在随后的几年里,巴蒂调整了战略,专注于带来更多利润的客户并放弃那些不盈利的客户 —— 而Jio仍在追逐新用户。
Over the next few years, Bharti shifted its strategy to focus on customers that made it more money and jettison those that didn’t — while Jio still chased new users.
安巴尼家族更倾向于强调Jio的潜力。领导IPO的穆克什长子阿卡什对公司的增长前景保持乐观。
The Ambanis prefer to emphasize Jio’s potential. Mukesh’s oldest son Akash, who is leading the IPO, remains optimistic about his company’s growth prospects.
上市后的Jio Platforms计划利用IPO募集的资金提前偿还大部分债务。这将使公司拥有更强劲的资产负债表,以便与埃隆·马斯克的星链在卫星通信领域竞争。印度监管机构尚未批准两家公司的申请。
A listed Jio Platforms plans to pre-pay a substantial chunk of its debt with the money raised from the IPO. That will leave the firm with a stronger balance sheet to compete with Elon Musk’s Starlink on satellite communications. Indian regulators are yet to clear both firms’ applications.
“我们始终有能力提高价格,但我们想做的是真正为客户提供更多服务,让他们非常满意,”阿卡什在上周的新闻发布会上表示。
“We always have the ability to take prices up, but what we want to do is to really deliver more services to our customers so that they’re very happy,” Akash said, while addressing a press conference last week.
对于股东而言,眼前的催化剂将是备受期待的移动资费上调,这有望为盈利提供助力。
For shareholders, though, the immediate trigger will be the much-awaited hike in mobile tariffs that should provide a kicker to earnings.
许多分析师与公司的乐观看法不谋而合。Centrum Broking Ltd. 认为,凭借强大的网络领先地位、大规模基础设施以及不断深化的数字生态系统,Jio 有望在中长期保持行业领先的增长。
Many analysts share the company’s optimism. With strong network leadership, large-scale infrastructure, and a deepening digital ecosystem, Jio is well positioned to sustain industry-leading growth over the medium- to long-term, according to Centrum Broking Ltd.
RSB LLP 管理合伙人 Chakri Lokapriya 表示,相较于同业,该公司估值具有吸引力,拥有庞大的用户基数、强大的客户服务,以及对 Bharti Airtel 和 Vodafone Idea Ltd 具有吸引力的竞争优势。
The company is attractively valued relative to its peers, with a subscriber base, strong customer service, and a compelling competitive position against Bharti Airtel and Vodafone Idea Ltd, said Chakri Lokapriya, managing partner, RSB LLP.
Lokapriya 说:“除了核心电信业务,Jio 在卫星通信、数字服务、人工智能及其他技术驱动型业务等新兴增长机遇方面也处于有利位置,提供了多重潜在的长期价值创造驱动力。”
“Beyond its core telecom business, Jio is well positioned to capitalize on emerging growth opportunities in satellite communications, digital services, AI and other technology-led businesses, providing multiple potential drivers of long-term value creation,” Lokapriya said.