投资者开始要求美国和欧洲银行发行的最具风险工具在新发行交易中提供更高补偿。
Investors in the riskiest instruments sold by US and European banks are starting to demand more compensation on new deals.
纽约梅隆银行公司本周发行的最新优先股定价,其利差比今夏创下的金融危机后最低点扩大了六分之一以上。比利时贝尔菲斯银行发行的一笔额外一级资本债券发行后即被指示低于面值交易,而意大利BBPM银行上周发行的额外一级资本债券在销售过程中订单量萎缩。
Bank of New York Mellon Corp’s latest preferred stock priced this week at a spthan a sixth wider than the post-crisis low it set this summer. An Additional Tier 1 bond by Belgium’s Belfius Bank SA was indicated below face value immediately after issuance, while orders for Banco BPM SpA’s AT1 deal last week shrank during the sales process.
这是信贷市场一个角风向的逆转,此前旺盛的需求曾将估值推至金融危机以来最紧水平。全球债券市场更广泛的波动正在抑制投资者胃口,促使买家质疑他们是否获得了足够补偿以应对包括证券未能在预期时被赎回在内的风险。
It’s a reversal for a corner of credit where rampant demand had recently pushed valuations to the tightest since the financial crisis. Broader volatility in the global bond market is weighing on appetite, prompting buyers to question whether they’re being adequately compensated for risks including that securities aren’t called when expected.
“大西洋全球资产管理公司基金经理兼研究主管罗曼·米吉尼亚克表示:“新发行溢价成为一层额外保护,新发行交易出现更多纪律约束,我不感到惊讶。在较弱的市场环境下,当延期风险开始显现时,一些重置利率极低、赎回日期较远的新发行产品可能会让人痛苦。”新发行交易遭遇的抵触情绪继二级市场交易的预警信号之后出现,现有债券和股份在二级市场易手。
“I’m not surprised that there is more discipline on new issues as your new issue premium becomes an extra layer of protection,” said Romain Miginiac, fund manager and head of research at Atlanticomnium SA. “In a weaker environment, some of these new issues with very low resets and longer call dates can be painful when extension risk starts to bite.”The pushback in new deals follows warning signs in secondary trading, where existing bonds and shares change hands.
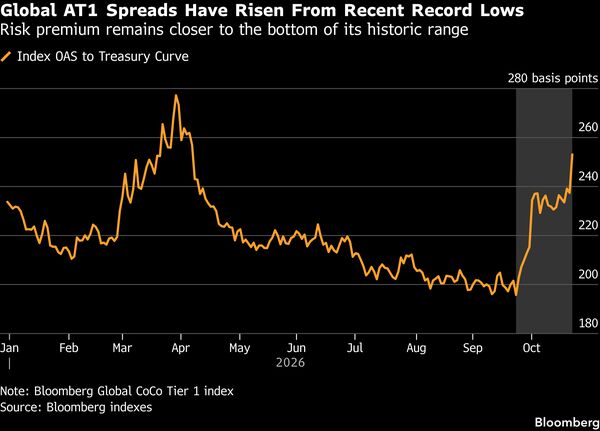
彭博全球多币种或有可转换债券指数的平均利差已升至253个基点,此前曾在8月和9月首次跌破200个基点。
The average spread in a multicurrency index of global contingent convertible bonds by Bloomberg has risen to 253 basis points after dipping below 200 basis points for the first time ever in August and September.
在美国,这种回撤体现在纽约梅隆银行最近的美元计价交易中。该笔交易提供的利差比三个月前高出32.4个基点,而三个月前基本相同的结构曾被冠以“荒谬地紧”,并创下了固定转浮动利率结构类别中金融危机后的最低利差纪录。
In the US, the pullback was on display on BNY’s recent dollar-denominated deal. It offered 32.4 basis points more for essentially the same structure that three months earlier had been branded “ridiculously tight” and set a post-crisis low for spreads in the fixed-to-reset type structure.
随着投资者变得厌恶风险,一些银行不得不通过增甜剂来激发需求,在想要融资时附加新发行优惠。
As investors grow risk-averse, some banks are resorting to sweeteners to drum up demand, tacking on a new-issue concession when they want to raise money.
但也有发行人牺牲订单量以换取激进定价。以意大利的Banco BPM为例。该行近期发行的一笔4亿欧元(约合4.48亿美元)AT1债券,最初吸引了约15亿欧元的订单,但在推销过程中,随着指导价位下调,订单量减半。
But others are sacrificing orders to win aggressive pricing. Take Banco BPM. The Italian bank’s recent AT1 issue, for €400 million ($448 million), had drawn orders of about €1.5 billion, but that fell by half over the course of marketing as indicative levels were cut.
Spring Investments SA首席投资官Jackie Ineke泛泛而谈道:“对我们而言,目前问题不在于新发债券看起来是否便宜,而在于市场是否正在企稳,以及我们能否在未来几周以更低价格买入。”她表示:“目前我们更倾向于后一种看法。”BNY和BPM的代表拒绝置评。Belfius的代表未回应置评请求。
“For us right now, it’s not a question of do the new issues look cheap, it’s more about is the market stabilizing, and can we pick these up cheaper, in the next few weeks?,” said Jackie Ineke, chief investment officer at Spring Investments SA, speaking generally. “At the moment, we think more the latter.”Representatives at BNY and BPM declined to comment. A Belfius representative didn’t respond to a request for comment.
美国的优先股和海外的额外一级资本债券(AT1)允许银行筹集监管资本,而不必完全依赖成本更高的普通股权。
Preferred shares in the US and Additional Tier 1 bonds abroad allow banks to raise regulatory capital without relying solely on more expensive common equity.
据彭博指数显示,近年来AT1债券在信贷资产中回报率名列前茅,2024年和2025年以美元对冲计算均实现了两位数回报。但其次级地位和复杂结构意味着它们涨得快、跌得也快。
AT1s have delivered some of the strongest returns in credit in recent years, in the double digits on a dollar-hedged basis in 2024 and 2025, according to Bloomberg indexes. But their subordination status and complex structures mean they can rise as quickly as they can fall.
随着全球债券市场在能源价格上涨、通胀担忧重燃以及货币政策预期收紧的压力下承压,今年以来回报率已从8月下旬的3.6%滑落至1.6%。法国债务市场的动荡增加了压力。
Returns have slipped to 1.6% year-to-date from 3.6% in late August as global bond markets buckle under higher energy prices, renewed inflation concerns and expectations for tighter monetary policy. Turmoil in France’s debt markets has added to the pressure.
公平地说,银行目前尚未被拒之市场门外,也远未面临是否跳过旧有工具赎回期权的痛苦抉择。
To be sure, banks do not find themselves shut off the market yet and are nowhere near having to make painful decisions on whether to skip call options on their older instruments.
全球或有可转换债券(CoCo债券)信用利差目前仍比该类债券在全球金融危机后推出以来的平均水平低约160个基点。
Global contingent-convertible spreads remain about 160 basis points below the average since this type of bond was introduced after the global financial crisis.
也存在反弹空间。ABN Amro Bank信贷策略主管Shanawaz Bhimji表示,如果收益率曲线变陡峭、银行兑现净利息收入承诺并维持早前指引,信用利差可能再度收窄。
There’s also scope for recovery. Spreads could tighten again if yield curves steepen, banks deliver on net interest income and uphold earlier guidance, according to Shanawaz Bhimji, head of credit strategy at ABN Amro Bank.
尽管如此,银行的融资负责人不得不适应这样一个现实:下一次筹集资本时,他们可能无法达成有史以来最优惠的交易条件。
Still, funding officers at banks are having to adjust to the reality that next time they raise capital, it may not be the best deal they could ever strike.
“我们大概率不会回到夏季前的水平,”摩根士丹利EMEA(欧洲、中东和非洲)区金融机构集团债务资本市场主管Charles-Antoine Dozin表示。“从历史角度看,当前水平仍具吸引力,务实的发行人依然能够达成良好的交易。”
“We are probably not going back to the pre-summer days,” said Charles-Antoine Dozin, Morgan Stanley’s EMEA head of FIG debt capital markets. “Current levels are still attractive in a historical context and pragmatic issuers can get good transactions done.”