在财政部长斯科特·贝森特近几个月出人意料地表示愿意干预债券市场以压低收益率后,华尔街正在为美国国债发行指引自2024年初以来最大规模的改版做准备。
After Treasury Secretary Scott Bessent surprised dealers with his willingness to intervene in the bond market to drive down yields in recent months, Wall Street is now girding for the biggest revamp in guidance for US Treasuries issuance since early 2024.
作者:格雷格·里奇、叶曦(音译) 许多交易商预计,财政部将在其季度政策声明中修改指引,该指引两年多来一直列出票据和债券发行的稳定计划。周三声明中的转变可能为2027年潜在削减最长期限债务销售铺平道路,并以扩大短期国库券和较短期限票据的拍卖规模来平衡。
By Greg Ritchie and Ye Xie Many dealers expect the Treasury to alter the guidance in its quarterly policy statement, which for more than two years has laid out steady plans for note and bond issuance A shift in Wednesday’s announcement could pave the way for potential cuts in 2027 to sales of the longest-dated debt, balanced by bigger auctions of bills and shorter-term notes.
一些机构正在为更激进的行动做准备。花旗集团预测,财政部将宣布从本月开始削减20年期和30年期债券的销售——这实际上违背了上一份所谓“季度再融资声明”发布的指引。就在上一份计划发布仅一周后,贝森特意外加大了对在外流通证券的回购力度,此举被视为对收益率飙升的反应。
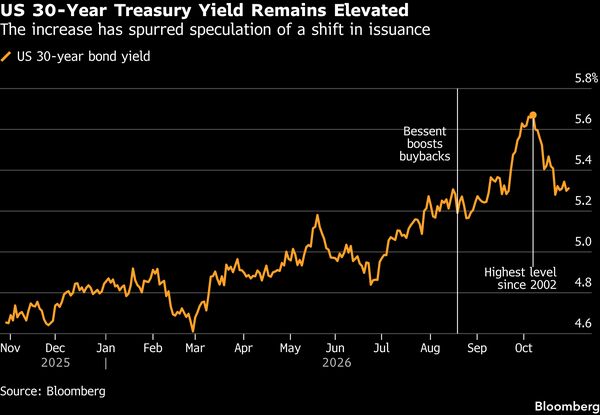
Some are prepping for more drastic action. Citigroup Inc. predicts the Treasury will announce cuts to sales of 20- and 30-year bonds starting this month — effectively violating the guidance issued in the last so-called quarterly refunding statement. Just one week after that last plan, Bessent unexpectedly ramped up buybacks of outstanding securities, in a move seen as a reaction to a surge in yields.
“回购规模太小,无法真正扭转局面,”洞见投资投资专家主管艾普丽尔·拉鲁斯在接受采访时表示。她直截了当地说:“如果你掌管财政部,你的主要权力是发行,如果你不喜欢收益率所在的位置,你就调整你的发行量。” 本周任何大规模调整的前提条件是,收益率已从10月初长期利率触及20多年来最高点以来有所回落。
“Buybacks are too small to really move the needle,” April LaRusse, head of investment specialists at Insight Investment, said in an interview. She put it simply: “if you’re running the Treasury and your main power is issuance, if you don’t like where the yields are, you adjust your issuance.”The proviso for any major shakeup this week is that yields have retreated since longer-dated rates hit their highest in more than two decades in early October.
尽管如此,周五30年期债券的交易收益率仍高于5.30%,处于贝森特8月通过扩大回购计划进行干预时的水平左右。另一个考量因素是:更加严重地依赖期限最长一年的短期国库券来满足不断扩大的融资需求,迟早会考验投资者的胃口。由于到期短期国库券需要不断再融资,美国目前在任何一周拍卖的国债规模都超过5000亿美元,使财政部面临突然波动的风险。
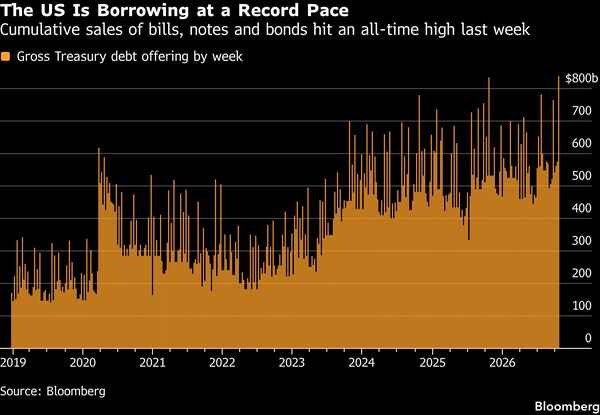
Still, 30-year bonds on Friday were trading with yields above 5.30%, around levels seen in mid-August when Bessent intervened with his expanded buyback program. Another consideration: relying even more heavily on bills, which mature in up to a year, to meet expanding funding needs at some point is bound at some point to test the appetite of investors. With rapidly maturing bills having to be refunded constantly, the US now auctions in excess of half a trillion dollars in any given week, leaving the Treasury exposed to sudden swings.
上周,官员们拍卖了创纪录的8390亿美元。美国财政部本周拍卖借入创纪录8390亿美元“指引调整比立即采取行动更有可能”改变发行策略,瑞银集团美国利率策略主管菲比·怀特表示。不过,财政部最近的“非常规”行为确实“增加了财政部行动继续偏离历史惯例的可能性”,她说。
Last week, officials sold a record $839 billion. US Treasury Borrows Record $839 Billion in Auctions This Week“Guidance is more likely than immediate action” to alter issuance strategy, said Phoebe White, head of US rates strategy at UBS Group AG. Still, the Treasury’s recent “unconventional” behavior does “increase the odds that Treasury actions continue to deviate from historical precedent,” she said.
瑞银是预计实际发行量直到5月都不会变化的机构之一。财政部早在8月就为政策转向敞开了大门,当时官员对指引进行了微妙调整,称正在评估未来票息债券和浮息债券发行可能出现的“变化”,而不再像以前那样提及潜在的“增加”。
UBS is among those seeing no change in actual issuance until May. The Treasury already opened the door to a shift in August, when officials made a subtle tweak to their guidance, saying they were evaluating potential future “changes” in coupon and floating-rate note sales instead of the previous reference to potential “increases.”
至于下周的季度再融资拍卖,如果发行规模保持不变,总额将达到1250亿美元,包括:11月9日拍卖580亿美元3年期债券11月12日拍卖250亿美元30年期债券自贝森特的前任珍妮特·耶伦确立目前的指引——预期在未来几个季度维持债券发行规模稳定——以来,交易商一直预期增发终将恢复。这是因为公共债务不断增加,政府每年赤字约2万亿美元。周一,财政部将更新其最新的季度借款需求估计。
As for next week’s quarterly refunding auctions, unchanged issuance sizes would mean they will total $125 billion, and consist of: $58 billion of 3-year notes on Nov. 9 $25 billion of 30-year bonds on Nov. 12 Ever since Bessent’s predecessor, Janet Yellen, established the current guidance about expecting to hold note and bond sales steady for quarters to come, dealers have expected increases to resume in time. That’s due to the ever-increasing amount of public debt, with the government running annual deficits of around $2 trillion On Monday, the Treasury will offer an update of its latest estimate of quarterly borrowing needs.
在为周三的声明做准备时,财政部利用其向一级交易商定期发放的再融资问卷,询问了关于国债“投资者需求的结构性变化”以及“财政部应考虑对拍卖规模做出哪些未来调整”的问题。摩根大通策略师杰伊·巴里(Jay Barry)率领的团队在其再融资前瞻报告中写道,财政部此举的核心在于其“对收益率水平感到不适”。即便如此,该团队预计财政部将把“未来几个季度”这一措辞延续至2027年,并将拍卖规模维持不变至明年8月,随后开启一系列增发,重点集中在2年至10年期债券上。
In preparing for Wednesday’s statement, the Treasury used its regular pre-refunding questionnaire of primary dealers to ask about “structural changes in investor demand” for Treasuries, and “what futures changes to auction sizes should Treasury consider.”At the heart of what the Treasury’s been engaged in is its “discomfort with the level of yields,” JPMorgan Chase and Co. strategists led by Jay Barry wrote in their refunding preview. Even so, the team expects the Treasury to maintain the “next several quarters” language into 2027, and to keep auction sizes unchanged through next August, before embarking on a series of increases focused on 2- to 10-year securities.
摩根大通的观点与许多预期会有变化的交易商形成对比。巴克莱团队由安舒尔·普拉丹(Anshul Pradhan)率领,建议官员们将“至少未来几个季度”这一措辞替换为“未来几个季度”——他们表示,此举将为财政部在“发行时机和结构上提供灵活性”。华尔街认为贝森特进入债务管理“新世界” 这一版本的措辞自2024年1月以来一直沿用,尽管投资者曾间歇性呼吁取消它。美国银行、高盛集团和瑞银集团等其他银行也在密切关注是否会有变化。
JPMorgan’s view contrasts with the many dealers anticipating a change. The Barclays Plc team led by Anshul Pradhan suggested officials replace the “at least the next several quarters” language with “the coming quarters” — a move they say would provide the Treasury with “flexibility over both the timing and composition of issuance.”Wall Street Sees Bessent Entering ‘New World’ For Debt Some version of the current language has been in place since January 2024, despite intermittent investor calls to get rid of it. Bank of America Corp., Goldman Sachs Group Inc. and UBS are among other banks on the lookout for a change.
观察人士周三还将关注财政部借款咨询委员会(TBAC)的讨论要点,该委员会由投资者、交易商和其他市场参与者组成,定期与高层官员会面。TBAC 就市场吸纳更多短期国库券发行能力的任何反馈可能尤为重要。
Observers will also on Wednesday be on watch for discussion points from the Treasury Borrowing Advisory Committee, a panel of investors, dealers and other market participants that meets with top officials. Any TBAC feedback on the market’s ability to keep absorbing bigger bill sales could be particularly meaningful.
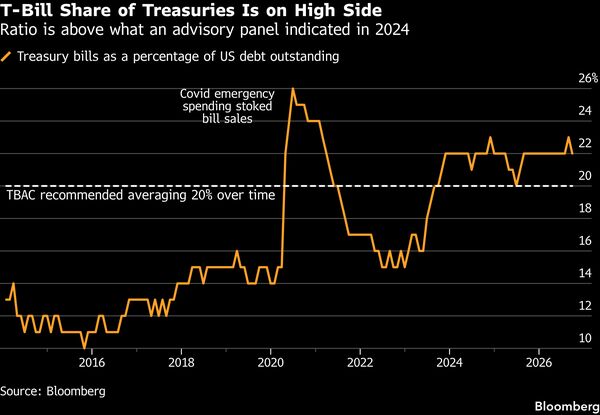
随着联邦借款持续增加,而中长期债券发行量未相应增加以弥补缺口,短期国库券在未偿还债务中的占比稳步上升,截至9月已达22%左右。这高于TBAC在2024年建议的长期平均20%水平。
With federal borrowing continuing to rise and no increase in note and bond sales to help pay for it, the bill share of debt outstanding has steadily risen, to around 22% as of September. That’s above the 20% level that the TBAC in 2024 advised as an average over time.
摩根大通团队辩称,考虑到未来几年所需借款的规模,削减长期债券发行并不明智,且有早期迹象显示对短期国库券的需求正在停滞。与此同时,稳定币购买国库券——财政部官员曾将其吹捧为新的需求来源——尚未大规模实现。周三还可能就国债回购发布新指引,此前官员已将10年至30年期领域的回购规模增加两倍至每次60亿美元。大多数投资者预计官员将维持这一规模,同时保留调整的选项。
JPMorgan’s team argued that cutting long bond sales wouldn’t be prudent given the scale of borrowing required over the coming years, and early signs that demand for Treasury bills is stalling Meantime, bill purchases from stablecoins, which Treasury officials have touted as a new source of demand, have yet to materalize at scale Wednesday may also bring new guidance on Treasury buybacks, after officials tripled those in the 10-year to 30-year sector to $6 billion each. Most investors expect officials will stick at that amount going forward, while maintaining the option to change.
“明确回购是管理未偿债务期限结构工具箱的一部分”,可能会增强市场影响,高盛由威廉·马歇尔领导的策略师团队在一份报告中写道。他们的想法可能是,“这为财政部在操作中降低价格敏感度铺平了道路”,他们写道。
“Making explicit that buybacks are part of the toolkit for managing the maturity composition of debt outstanding,” could strengthen the market impact, Goldman strategists led by William Marshall wrote in a note. The thinking might be that “it paves the way for Treasury to become less price sensitive in its operations,” they wrote.