自人工智能热潮兴起以来,投资者一直担心谷歌在互联网搜索领域的统治地位能否在AI时代保持下去。
Since the artificial intelligence boom began, investors have worried about how Google’s dominance in internet search would hold up in an AI world.
如果上周Alphabet Inc.(谷歌母公司)发布的财报显示搜索收入不及预期有任何指示意义的话,那些担忧是有充分理由的。而在一番讽刺性的转折中,至少部分威胁来自内部,因为谷歌不断扩大的AI布局正在吞噬其优势之一的过程中。
If last week’s earnings report from parent Alphabet Inc. showing weaker-than-expected search revenue is any indication, those fears were well founded. And in a twist of irony, at least part of the threat is coming from inside the house, as Google’s expanding AI presence cannibalizes one of its strengths in the process.
“如果下金蛋的鹅不再下金蛋,那就有理由担心了,”拥有Alphabet股份的Graham Capital Wealth Management首席投资官Stash Graham表示。
“If the golden goose isn’t a golden goose anymore, then there’s reason to be worried,” said Stash Graham, chief investment officer at Graham Capital Wealth Management, which owns Alphabet shares.
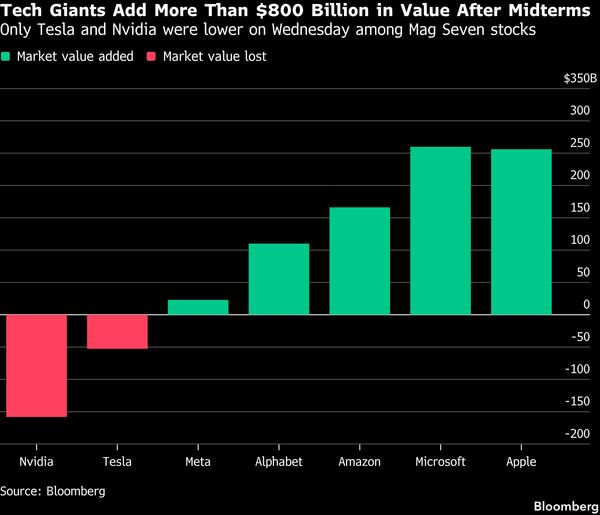
周三,在大选后的狂欢情绪推动大多数大型科技股上涨的带动下,Alphabet股价反弹。但这无法掩盖上周财报发布后的历史性抛售。不仅搜索收入不及预期,公司还表示,其搜索AI模式的普及(该模式的变现率低于传统搜索)是一个促成因素。
Alphabet shares rallied on Wednesday amid the post-election euphoria that lifted most Big Tech stocks. But that doesn’t hide the historic selloff last week after the company reported earnings. Not only did search revenue miss, the company said the popularity of its AI Mode for search, which it monetizes at a lower rate than traditional search, was a contributing factor.
搜索业务前景疲软——2025年搜索占Alphabet收入的一半以上——成为投资者的最新危险信号,此前他们已因公司飙升的资本支出、担心其在尖端AI模型上落后以及上一季度自由现金流为负而受创。这标志着其从历史上作为可靠的自由现金流机器的形象发生了转变。
The prospect of weakness in search, which accounted for more than half of Alphabet’s 2025 revenue, was the latest red flag for investors, who had already been stung by its soaring capital expenditures, concerns it’s falling behind in cutting-edge AI models and negative free cash flow in the previous quarter. That marked a shift from its historic profile as a reliable free cash flow machine.
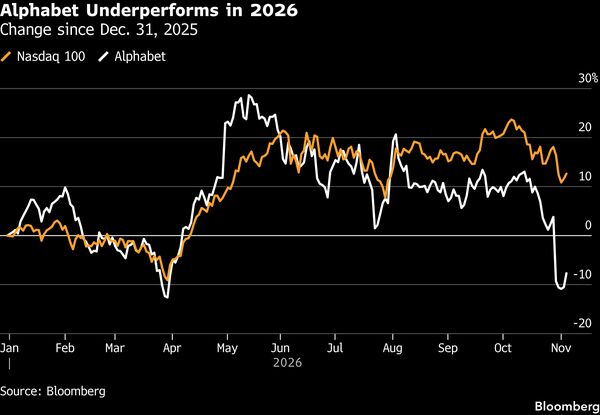
Alphabet股价今年表现挣扎,在2025年飙升65%后转为下跌。抛售自春季以来加速,股价在下半年暴跌19%,成为该时期标普500指数第二大拖累股。仅10月就下跌近19%,创下有史以来最差单月表现,市值蒸发7580亿美元。
Alphabet shares have struggled this year, sliding into the red after soaring 65% in 2025. The selloff has accelerated since the spring, with the stock tumbling 19% in the second half, making it the second-biggest drag on the S&P 500 in that time. It lost almost 19% in October alone, marking its worst month ever and wiping out $758 billion in market value.
反过来看,股价下跌也让该股显得相对便宜。目前其市盈率约为未来12个月预估盈利的18倍,低于2月份的29倍,也低于其10年平均约21倍的水平。格雷厄姆表示,向高资本支出和负现金流的转变证明了低估值的合理性。不过,他对搜索业务增速放缓感到意外,这让股票估值变得更加困难。
On the flipside, the downturn has also made the stock relatively cheap. It’s currently trading at about 18 times earnings estimated over the next 12 months, down from 29 times in February and a discount to its 10-year average of roughly 21. The shift to high capex and negative cash flow justifies the low valuation, Graham said. However, he was surprised by the deceleration in search growth, which makes the shares harder to value.
他说:“如果搜索疲软是暂时的,正如我认为的那样,那么目前的估值倍数是体面的。但如果出现持久恶化,那么股价应该交易得更低。”考虑到谷歌几乎等同于互联网搜索,很难过分强调该业务对Alphabet股东的重要性。该股在2023年、2024年和2025年也曾因搜索相关担忧而遭遇抛售。然而,这一次担忧似乎更为严峻,特别是Meta Platforms Inc.凭借其Muse AI智能体产品大放异彩。
“It is trading at a respectable multiple right now if the search weakness is temporary, as I think it is,” he said. “But if there’s a lasting deterioration, then it should trade even lower.”Considering Google is essentially synonymous with internet search, it’s difficult to overstate the importance of that business to Alphabet shareholders. The stock also saw search-related selloffs in 2023, 2024 and 2025 as well. However, the concerns seem more acute this time around, especially with Meta Platforms Inc. making a big splash with its Muse AI agent product.
Citizens Inc.分析师安德鲁·布恩在10月29日的报告中写道:“随着来自智能体的竞争加剧,我们认为智能体是通往互联网的未来入口(将取代浏览器或搜索),谷歌在搜索变现转型过程中面临重大执行风险。”他在报告中将Alphabet评级从“跑赢大盘”下调至“大盘表现”。
“With greater competition from agents, which we view as the future gateway to the internet (replacing the browser or search), Google has significant execution risk ahead as it transitions search monetization,” Citizens Inc. analyst Andrew Boone wrote in an Oct. 29 report in which he downgraded Alphabet to market perform from outperform.
著名看多分析师、Yorkville Ives的丹·艾夫斯在10月30日的报告中写道:“这是‘AI冲击搜索’这一负面论点首次在一个季度中站得住脚。”
“This is the first quarter that the negative thesis around AI crushing search has legs,” famously bullish analyst Dan Ives of Yorkville Ives wrote in an Oct. 30 note.
过去一周,分析师们将Alphabet 2026财年每股收益预期下调了4.5%。除了搜索问题,华尔街还担心该公司在构建AI基础设施方面的巨额投资何时能产生显著回报。
Over the past week, analysts have cut their estimates for Alphabet’s 2026 earnings per share by 4.5%. Beyond the search issue, Wall Street is also concerned about the company’s heavy investments in building out AI infrastructure and when they will generate significant returns.
话虽如此,看多者可以从Alphabet云业务加速增长以及股票相对较低的估值中找到安慰。
That said, bulls can find comfort in the accelerating growth in Alphabet’s cloud business and the stock’s relatively low valuation.
“玫瑰花期已过,但股价已跌至开始显得便宜的程度,”拥有Alphabet股份的River Wealth Advisors首席执行官Ed O’Gorman表示。
“The bloom is off the rose, but shares are getting to a point where they’re starting to look cheap,” said Ed O’Gorman, chief executive officer of River Wealth Advisors, which owns Alphabet shares.
“关于代理式搜索最终的营收模式会是什么样,仍存在真正的疑问,但Alphabet拥有其他增长相当不错的营收来源,云业务就是首屈一指的例子,”他说。“当出现如此显著的膝跳式抛售时,很可能存在进场机会。我认为这可能有点过度了,因为我们在如何演变这一问题上仍处于非常早期阶段。”
“There are still real questions about what the revenue model will ultimately look like for agentic search, but Alphabet has other sources of revenue that are growing quite nicely, with cloud being the number one example,” he said. “There’s likely an opportunity to step in when you get such a significant knee-jerk selloff. I think it might be a bit overdone, since we’re still in the very early days for how this will play out.”