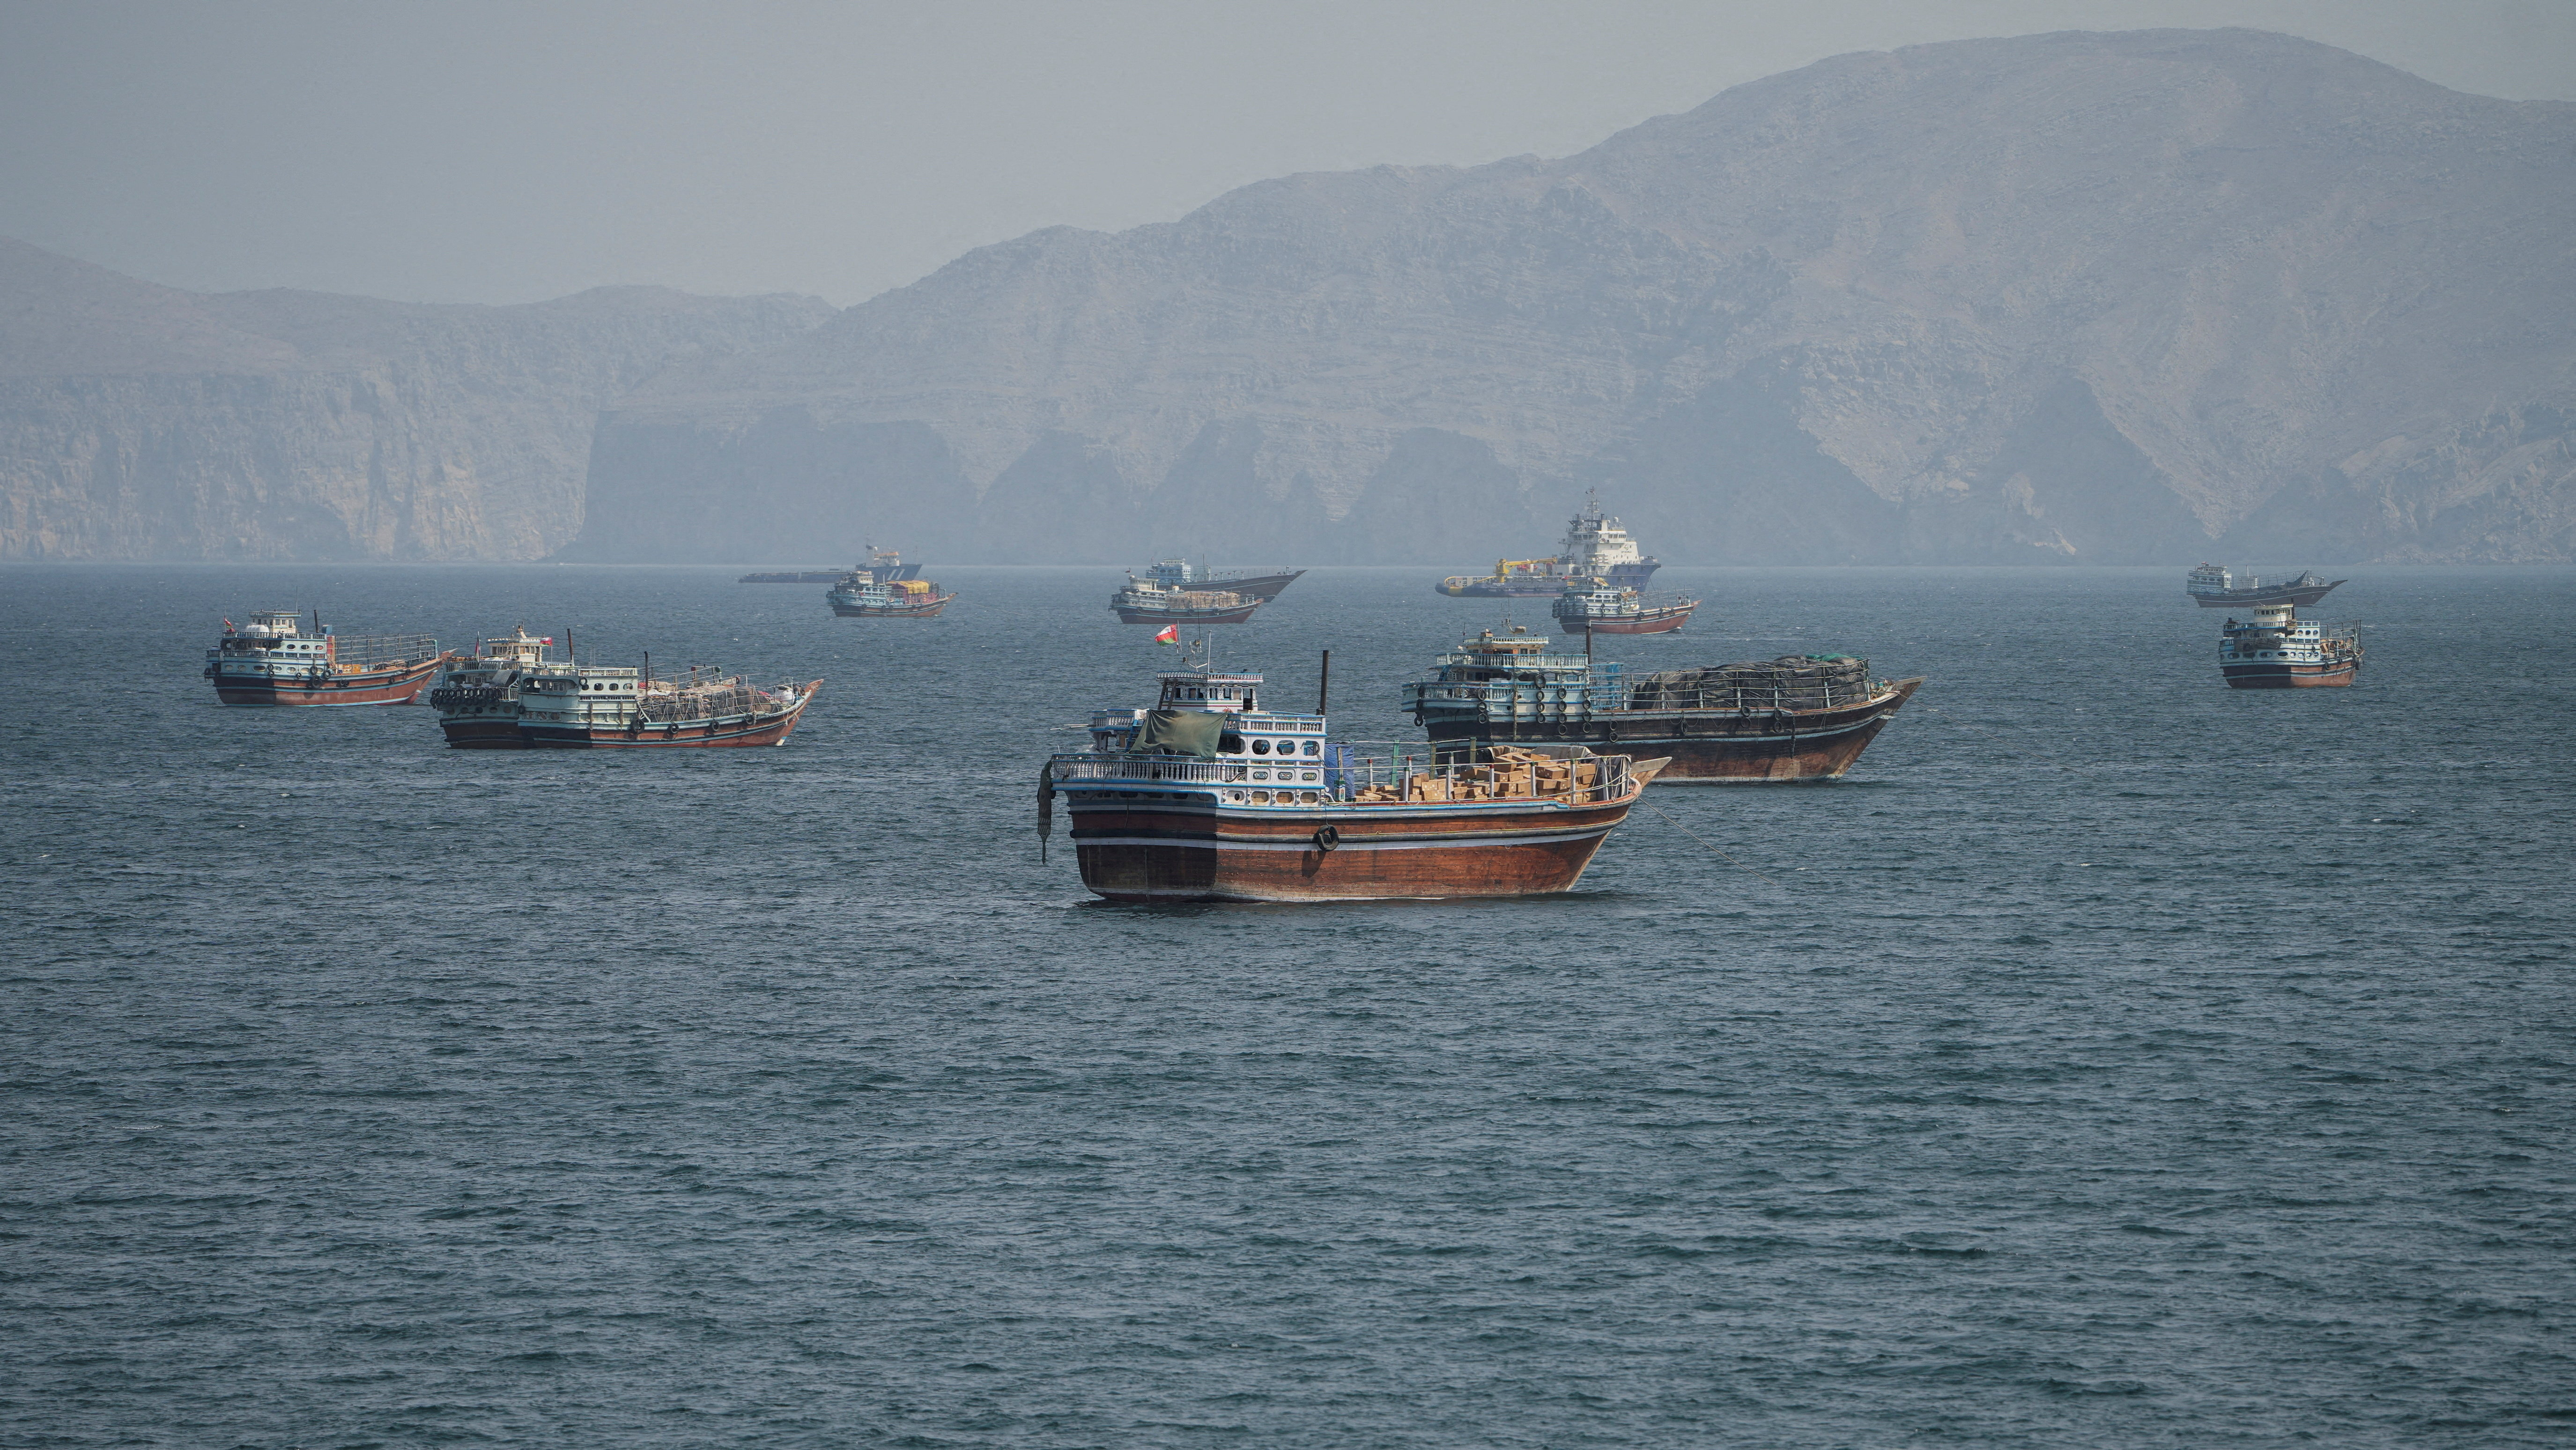
分析师和交易员表示,尽管自3月以来扰乱中东出口的伊朗战争仍未解决,但由于高油价导致需求下降,全球石油市场正呈现出重现供应过剩的迹象。
The global oil market is showing signs of a return to excess supply as demand drops due to high prices, analysts and traders said, despite the lack of a resolution to the Iran war, which has disrupted exports from the Middle East since March.
在2026年初,市场普遍预计将出现供应过剩,但2月下旬伊朗战争的爆发引发了国际能源署所称的全球有史以来最大规模的供应中断,并削减了中东出口,从而颠覆了过剩的预测。
The market was widely expected at the start of 2026 to be in a surplus, but the outbreak of the Iran war in late February led to what the International Energy Agency called the world's biggest ever supply disruption and cut Middle East exports, overturning the surplus projections.
部分由于高油价,银行和政府预测机构下调了2026年全球石油需求预测。随着供应恢复,疲软的需求正帮助市场实现平衡。
Banks and government forecasters have cut global oil demand forecasts in 2026 in part due to high prices. As supplies recover, weak demand is helping the market to balance.
摩根大通在一份报告中表示,中东石油流量的恢复、其他国家产量的增加以及疲软的需求,已再次将全球供应推高至消费水平之上。
Recovering Middle Eastern oil flows, rising production from other countries and weak demand have pushed global supply above consumption once again, JP Morgan said in a report.
该行表示:“我们估计,全球石油市场在9月恢复了每日110万桶的过剩,并在10月扩大至每日140万桶,几乎与去年每日130万桶的平均水平相当。”
"We estimate the global oil market returned to a surplus of 1.1 million barrels per day in September, widening to 1.4 million bpd in October, nearly matching last year’s average of 1.3 million bpd," the bank said.
该行指出,10月份全球原油进口量升至高于2025年平均水平,而需求却在滞后。
Global crude oil imports in October rose above average 2025 levels, the bank said, while demand lags.
伊朗战争促使国际能源署安排了工业化国家战略储备有史以来最大规模的石油释放,并消耗了商业库存。
The Iran war prompted the IEA to arrange a record release of oil from industrialised nations' strategic reserves, and has drawn down commercial inventories.
然而,高盛估计,在经历自伊朗战争爆发后几个月的大幅下降之后,全球库存并未在9月至10月期间下降。
However, Goldman Sachs estimates that global stocks did not decline in September to October after falling sizeably in the months following the start of the Iran war.
高盛认为,与今年3月的供应短缺相比,9月至10月期间市场大致处于平衡状态。该行表示,去年的微幅过剩、海湾地区以外产量的回升以及需求的下降,共同帮助市场恢复了平衡。
Goldman sees the market as broadly balanced in the September-October period, compared to a deficit in March this year. A marginal surplus from last year, an uptick in production outside the Gulf, along with a decline in demand helped balance the market, the bank said.
这两家银行还指出,自战争初期以来,来自中东的石油流量有所回升。
Both banks also pointed to an uptick of oil flows from the Middle East since the early months of the war.
*来自该地区的石油运输量在10月较9月的水准略有下降,9月的运量曾达到伊朗战争爆发以来的最高水平。两家船舶追踪机构表示,随着更多运输细节的浮现,10月份的数据可能会向上修正。
Oil shipments from the region edged lower in October from September's levels, which were the highest since the Iran war started. Two ship-tracking firms said the October figures could be revised upwards as more details on shipments emerge.
船舶追踪机构Vortexa表示,10月份来自海湾地区的原油和凝析油出口平均为每日1400万桶,约为战前水平的86%,而精炼产品出口平均为每日310万桶,刚超过正常水准的一半。
Crude and condensate exports from the Gulf averaged 14 million bpd in October, or about 86% of pre-war levels, while refined product exports averaged 3.1 million bpd, or just over half of normal volumes, ship-tracking firm Vortexa said.
作为实体市场出现短期供应过剩的迹象,被称为差价合约的布伦特互换价格曲线已经发生了变化。
In a sign of a short-term surplus of supply in the physical market, the price curve of Brent swaps, called contracts for differences, has moved.
根据伦敦证券交易所集团的数据,本周交割的合约交易价格低于下周交割的合约,且创下7月以来的最大贴水幅度。第二周和第三周合约的价格也较下周合约呈贴水交易。
The contract for delivery this week is trading below that for the following week and at the steepest discount since July, according to LSEG data. The prices of the second- and third-week contracts are also trading at a discount to the next week.
这种市场结构被称为期货溢价,通常反映出市场对即期交付供应充足的看法。
This market structure is called contango and generally reflects a perception that supply for immediate delivery is ample.
相比之下,2027年1月及之后交割的布伦特原油期货仍保持与期货溢价相反的结构,即现货价格高于远期合约的现货升水。这表明近期供应仍然紧张。
By contrast, Brent crude futures starting from January 2027 delivery remain in the opposite structure to contango, known as backwardation, where prompt prices are higher than later contracts . This indicates that supply remains tight in the near term.
资深石油交易员兼市场专家阿迪·伊姆西罗维奇表示,如果互换合约继续保持这种状态,布伦特期货也可能转为期货溢价结构,因为市场结构的此类变化通常始于实体市场。
Brent futures could also move into a contango structure if the swaps remain there, said Adi Imsirovic, a veteran oil trader and market expert, as such changes in the market structure usually start in the physical market.