近期美国债券市场上看涨头寸的涌入遭遇重挫,原因是两位美联储官员的表态以及粘性通胀的最新证据,加大了加息的可能性,导致美国国债暴跌。
A recent influx of bullish positioning across the US bond market just got smacked, as comments from a pair of Federal Reserve officials and fresh evidence of sticky inflation increased the odds of interest-rate hikes, sending Treasuries into a tailspin.
周二的抛售波及整个国债收益率曲线,交易员开始定价美联储更激进的紧缩路径,此前美联储理事克里斯托弗·沃勒表示,他支持加息,并倾向于如果通胀继续加速,就支持加息半个百分点。一份高于预期的消费者物价报告为这一转变添了柴,达拉斯联储行长洛丽·洛根进一步的鹰派表态也起到了推波助澜的作用。
Tuesday’s selloff rippled throughout the Treasury curve, with traders pricing in a more aggressive Fed tightening path after Governor Christopher Waller said he supported a rate increase and that he’d favor a half-point hike if inflation continued to accelerate. A hotter-than-expected consumer price report added fuel to the shift, as did further hawkish comments from Dallas Fed President Lori Logan.
这场抛售——使两年期美国国债收益率飙升19个月来最大涨幅,并一度将10年期收益率重新推高至5%以上——打乱了近期投资者的计划,这些投资者此前因人工智能交易周边的市场动荡,一直涌入国债或减少看空押注。
The rout — which sent two-year US yields soaring by the most in 19 months and briefly pushed 10-year yields back over 5% — upended investors who lately had been flocking to Treasuries or turning less bearish in response to recent market jitters around the AI trade.
在过去一周里,资产管理人员继续在收益率曲线各期限上建立期货多头头寸,同时平掉长端的看空押注,美国银行公司策略师在11月8日的一份报告中写道。
Over the last week, asset managers continued to establish long positions in futures across the curve, while covering bearish wagers in the long end, Bank of America Corp. strategists wrote in a Nov. 8 note.
不过,随着交易员越来越多地定价美联储紧缩政策将在明年3月会议前“前置”,政策敏感的两年期收益率“仍有空间回到9月底的水平”,当时该收益率触及略低于5%的峰值,哥伦比亚索德尼投资组合经理埃德·阿尔-侯赛尼表示。该收益率周二收于4.73%。
Now, though, with traders increasingly pricing in “frontloading” of Fed tightening into the March meeting next year, the policy-sensitive two-year yield “still has room to get where we were at the end of September,” when it peaked just shy of 5%, said Ed Al-Hussainy, portfolio manager at Columbia Threadneedle Investments. It ended Tuesday at 4.73%.
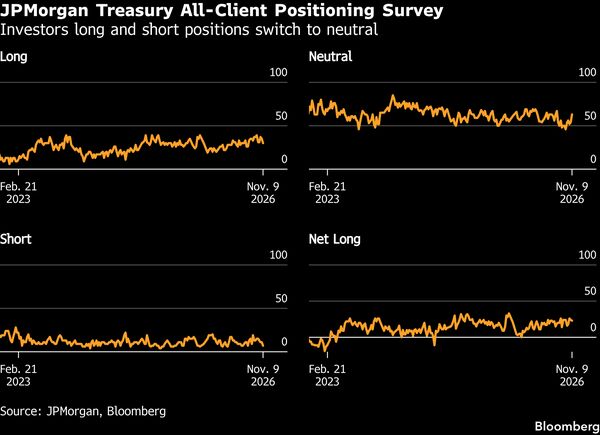
在现券市场,分歧的交叉潮流让一些投资者难以确定方向。摩根大通公司周二发布的国债客户调查显示,信心程度有所下降,避险战术多头和更长期的空头头寸相互对抗。该调查显示,多头和空头头寸均大幅下降,中性头寸升至约12周来的最高水平。
In the cash market, the divergent cross-currents have left some investors struggling for direction. JPMorgan Chase & Co.’s Treasury client survey released Tuesday reveals diminishing levels of conviction, with safe-haven tactical longs and longer-term short positions battling against each other. The poll showed both long and short positions dropping sharply, leaving neutrals at their most elevated in about 12 weeks.
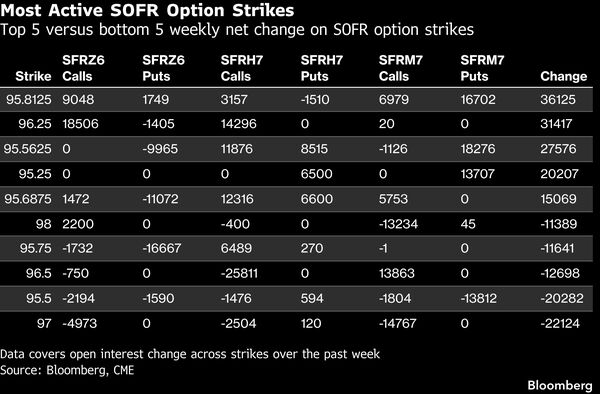
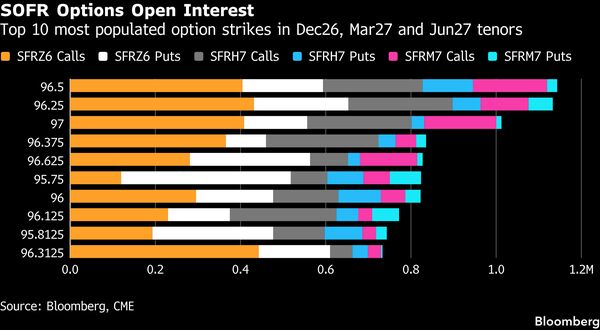
并非所有交易员都被周二的抛售措手不及。在期权市场,过去一周的资金流向开始显示出交易员正在平仓避险对冲的迹象。周一,一名五年期1月107.00看涨期权的大卖家似乎平仓了在10月下旬建立的看涨对冲,但损失约300万美元。以下是过去一周利率市场其他定位指标的概述:在SOFR 12月26日、3月27日和6月27日期权中,由于过去一周对SFRH7 95.75/95.8125/95.875/95.9375看涨期权组合策略的需求不错,多个3月27日看涨期权行权价新增了相当数量的风险,同时SFRH7 95.4375/95.5625/95.6875看涨期权组合策略在过去一周也被买入。
Not all traders were wrong-footed by Tuesday’s selloff. In the options market, flows over the past week have started to show signs that traders are unwinding safe-haven hedges. On Monday, a large seller of five-year January 107.00 calls appeared to unwind a bullish hedge set in late October, though at a loss of roughly $3 million. Here’s a rundown of other positioning indicators across the rates market over the past week: Across SOFR Dec26, Mar27 and Jun27 options, there was a decent amount of new risk added across a number of Mar27 call strikes due to decent demand seen over the past week for SFRH7 95.75/95.8125/95.875/95.9375 call condors, while SFRH7 95.4375/95.5625/95.6875 call flies were also bought over the past week.
在12月26日、3月27日和6月27日SOFR期权中,96.50行权价仍是最集中的行权价之一,这得益于近期SFRM7 96.50/97.25 2x3看涨期权价差的大额持仓,该价差是通过卖出3月27日96.25/97.00 2x3看涨期权价差而买入的。
Across Dec26, Mar27 and Jun27 SOFR options, the 96.50 strike remains among the most populated, aided by recent large position of SFRM7 96.50/97.25 2x3 call spreads, which were bought vs selling Mar27 96.25/97.00 2x3 call spreads.
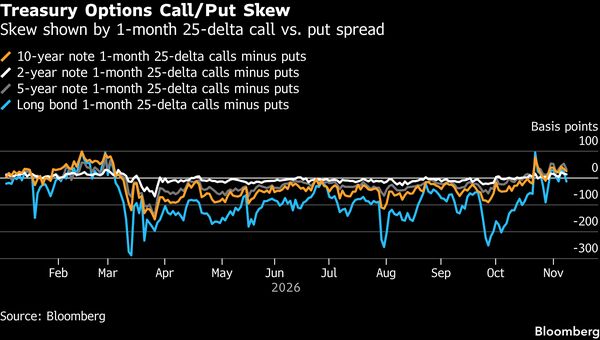
过去几周,对冲国债期权的溢价已重新转向看涨期权,因为交易员为对冲债券上涨而支付的溢价高于对冲抛售。期权市场最近的显著资金流向是卖出上行保护,因为非农就业、中期选举和美国财政部再融资公告等事件风险已过去。周一,出现了一名大卖家,在5年期看涨期权中进行亏损平仓,该对冲似乎是在10月建立的。
The premium to hedge Treasury options has trended back toward calls over the past couple of weeks, as traders pay a higher premium to hedge a bond rally versus a selloff. Recent standout flows in options have been to sell upside protection, with event risks such as payrolls, midterm elections and the Treasury’s refunding announcement now in the past. On Monday, there was a large seller for loss liquidation in 5-year calls, a hedge which looked to be initiated in October.
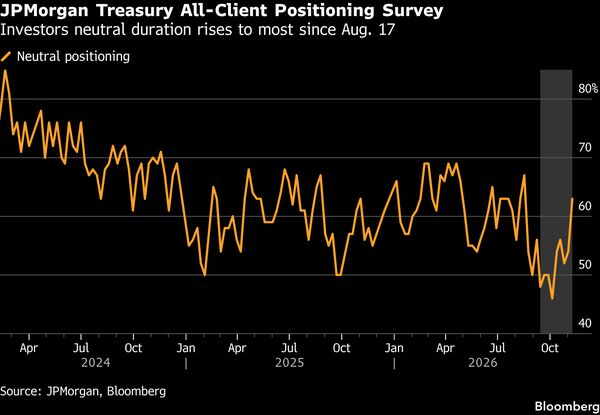
截至11月9日这一周,投资者的信心有所减弱,空头和多头均有所减少(空头减少4个百分点,多头减少5个百分点),转而持有中性头寸(上升9个百分点)。该调查现在显示,中性头寸数量最高,而纯粹的空头和多头数量最低,自8月17日以来首次。
In the week up to Nov. 9, investors showed diminishing conviction, with both shorts (4 percentage points cut) and longs (5 percentage points cut) reduced, switching into neutrals (rising 9 percentage points). The survey now shows the highest amount of neutrals and lowest outright shorts and longs since Aug. 17.