中国银行股获得顺风,因英伟达公司周围的动荡加深了人工智能交易的裂痕,推动投资者转向防御性押注。
Chinese bank stocks are gaining a tailwind as turmoil around Nvidia Corp. deepens cracks in the artificial intelligence trade and drives investors toward defensive bets.
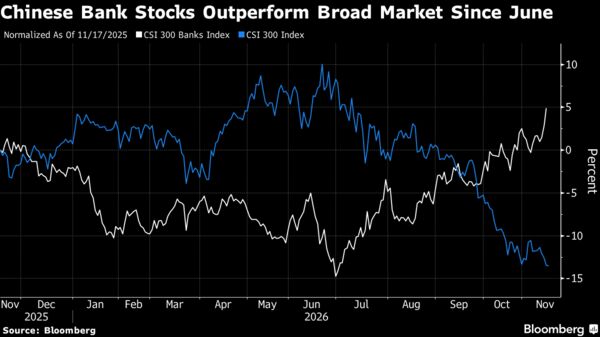
自上周初英伟达丑闻浮出水面以来,沪深300银行指数已上涨逾4%,有望实现连续第五个月上涨。与此同时,科技股云集的科创50指数下跌约3%,自6月高点以来的跌幅扩大至45%。
The CSI 300 Banks Index has risen more than 4% since the Nvidia scandal surfaced early last week, putting it on course for its fifth straight month of advance. Meanwhile, the tech-heavy Star 50 Index has declined about 3%, taking its drop from a June high to 45%.
中国银行股自6月下旬低点以来已反弹逾20%,得益于创纪录利润和利差改善。分析师表示,随着对AI支出的信心动摇,以及美国最新限制中国获取先进芯片的举措,推动资金轮动至高股息股票,加之国内基金配置偏低,留有进一步买入空间,该涨势可能具有持续性。
Chinese lenders have rallied more than 20% from a low in late June, buoyed by record profits and improving margins. The advance may have staying power as wavering confidence in AI spending and fresh US curbs on China’s access to advanced chips spur a rotation toward higher-yielding shares, while underweight positioning among domestic funds leaves room for further buying, analysts said.
“银行已成为反AI交易:体量大、流动性好,能够吸纳从科技股轮动出来的资金,”美国银行全球研究亚洲股票策略主管兼中国股票研究联席主管吴雯(Winnie Wu)表示。“甚至那些本无需持有中国资产的新加坡对冲基金现在也在持有国有大行股票,”她称,这给予了看涨支撑。
“Banks have become the anti-AI trade: large, liquid, and able to absorb flows rotating out of tech,” said Winnie Wu, head of Asia equity strategy and co-head of China equity research at BofA Global Research. “Even Singapore-based hedge funds with no need to own China are now owning SOE banks,” giving them a bullish support, she said.
自民主党在美国中期选举中大胜以来,对AI建设放缓的担忧加剧,英伟达的动荡更增加了对这一推动市场交易的怀疑。相比之下,中国银行基本面保持完好,受较高利差支撑。
Fears of a slowdown in the AI buildout have grown since the Democrats swept the US midterm elections, with turmoil at Nvidia adding to doubts over a trade that has powered markets. By contrast, fundamentals for Chinese banks remain intact, supported by higher margins.
按资产计算全球最大银行——中国工商银行股份有限公司报告称,第三季度净利润同比增长10%,为五年来最大增幅。较小竞争对手中国农业银行股份有限公司也录得双位数增长,而中国建设银行股份有限公司和中国银行股份有限公司分别录得9.8%和6.4%的增幅。工商银行和中国银行股价在香港徘徊于历史高位附近。
Industrial & Commercial Bank of China Ltd., the world’s biggest bank by assets, reported a 10% year-on-year increase in third-quarter net income, its steepest gain in five years. Smaller rival Agricultural Bank of China Ltd. also posted double-digit increases, while China Construction Bank Corp. and Bank of China Ltd. recorded gains of 9.8% and 6.4%, respectively. Shares of ICBC and Bank of China are hovering near record highs in Hong Kong.
大华继显私人财富管理总监吴健荣表示,银行股的吸引力在于稳定的股息,其收益率远高于10年期中国国债收益率。未来12个月中国主要银行股的预期收益率约为4.6%,而基准沪深300指数为3.2%,10年期国债约为1.6%。
Banks’ appeal rests on dependable dividends, with yields well above the 10-year Chinese government bond yields, said Kenneth Goh, director of private wealth management at UOB Kay Hian. The expected yield on Chinese major bank stocks over the next 12 months is about 4.6%, compared with 3.2% for the benchmark CSI 300 Index and about 1.6% on the 10-year government bond.
季节性因素可能提供进一步支撑。彭博汇编的数据显示,过去10年中有7年沪深300银行指数在第四季度上涨。
Seasonality may offer further support. The CSI 300 Banks Index has gained in the fourth quarter in seven of the past 10 years, Bloomberg-compiled data show.
不过,在经济复苏乏力的背景下,明年利润增长可能放缓。花旗集团预计,大型银行的平均盈利增速将从2026年的5.7%放缓至2027年的4.5%,而税前拨备经营利润增速可能从12.4%放缓至6.7%。
To be sure, profit growth may moderate next year amid a sluggish economic recovery. Citigroup Inc. expects average earnings growth at large banks to ease to 4.5% in 2027 from 5.7% in 2026, while pre-provision operating profit growth may slow to 6.7% from 12.4%.
国债利息收入潜在征税构成另一风险。花旗估计,若拟议的25%税率实施,中国银行未来五年每年盈利可能面临2%-3%的冲击,中国邮政储蓄银行和中国农业银行可能受影响最大。
A potential tax on government-bond interest income poses another risk. Citigroup estimates Chinese banks could face a 2%-3% annual hit to earnings for five years if a proposed 25% tax is implemented, with Postal Savings Bank of China Co. and Agricultural Bank of China potentially among the most affected.
尽管如此,考虑到共同基金二季度对银行股配置不足,仍有进一步增配空间,据瑞银集团数据。科技股进一步走弱和房地产支持政策均为潜在催化剂。
Still, there’s scope for further mutual fund allocations given that they were were underweight banks in the second quarter, according to UBS Group AG. Further tech-stock weakness and property supportive policies are potential catalysts.
“考虑到股息确定性和稳定的盈利前景,我们未来六到十二个月仍看好该板块,”瑞士宝盛香港研究主管邓志伟表示。大多数中国银行受益于存款重新定价后的资金成本下降,有助于在“市场关注AI数据中心建设步伐、科技前景不确定性上升”之际提升净息差。
“We still like the sector in the next six to twelve months considering their dividend visibility and stable earnings outlook,” said Richard Tang, head of research Hong Kong at Julius Baer. Most Chinese banks are benefiting from lower funding costs after repricing deposits, helping lift net interest margins amid “rising uncertainties in the tech outlook as market focuses on the pace of AI data center buildout,” he said.