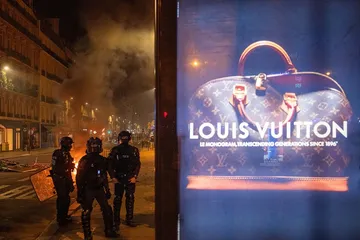
如果债券市场会说话,它对法国近期骚乱后加强警力的反应,或许会用那部剧中十字军骑士的台词:“你选择了……明智地。” 投资者将10月17日抢劫和暴力事件后的社会动荡,视为对不得人心、处于跛脚鸭地位的马克龙政府的一大考验:它能否防止本已脆弱的财政和政治危机进一步恶化。法国成功避免了大规模混乱重演,并将大多数持续进行的(且基本和平的)示威活动限制在巴黎边缘,这有助于抑制法国债务相对于德国债务的风险溢价。
If the bond market could talk, it might respond to France’s increased policing after recent riots with the words of the crusader knight from the series: “You have chosen… wisely.”Investors see the social unrest after the looting and violence of Oct. 17 as a big test of whether the unpopular lame-duck Macron administration can keep an already fragile fiscal and political crisis from getting worse. The fact that the country was able to avoid a repeat of large-scale mayhem and confine most ongoing (and largely peaceful) demonstrations to the edges of Paris last weekend has helped contain the risk premium applied to French debt over Germany’s.
在骚乱导致从爱马仕奢侈品店到金融科技公司Qonto总部等企业遭受约10亿欧元(约11亿美元)损失、利差飙升至15年高点178个基点后,该利差已回落至150个基点左右。
The spread has fallen to around 150 basis points after rocketing to a 15-year high of 178 in the wake of the rioting, which inflicted around €1 billion ($1.1 billion) worth of corporate damage, from the luxe stores of Hermès to the headquarters of fintech firm Qonto.
市场压力的缓解也反映出总统埃马纽埃尔·马克龙避免了通过紧急支出来“用金子堵住抗议者的嘴”——这种克制符合时刻警惕的债券卫士和高达国内生产总值近120%的债务堆这一新现实。这理应为欧洲央行在周四进一步安抚市场神经提供契机,届时预计将维持利率不变。加上评级机构穆迪决定暂不下调法国信用评级,清楚地解释了为何一些基金认为市场的低迷已过头了。
A pullback in market stress also reflects President Emmanuel Macron’s avoidance of emergency spending to stuff protesters’ mouths with gold — a restraint in keeping with the new reality of ever-watchful bond vigilantes and a debt pile equivalent to almost 120% of gross domestic product. It should ideally provide an opening for the European Central Bank to move to calm nerves further on Thursday, when it’s expected to keep interest rates unchanged. Throw in rating agency Moody’s decision to spare France from a credit-rating downgrade and it’s clear why some funds have decided the market malaise has gone too far.
但从长远来看,债务上较温和的“骚乱溢价”及其他喘息机会,不应掩盖这样一个事实:无论谁继任马克龙,都将继承一个更危险、更不确定的时代。
But longer term, a milder “riot premium” on its debt and other reprieves shouldn’t mask the fact that whoever succeeds Macron will inherit a more dangerous and uncertain era.
动荡背后是法律与秩序无法解决的深层社会问题。对不断上涨的通胀的反弹正在助长抗议活动和工会发起的11月5日罢工号召,即使马克龙对唐纳德·特朗普在中东挑起的通胀战争几乎没有控制力。对未来悲观的愤怒学生呼应着日益广泛的对公共服务的不满;三分之二的民众认为公共服务已经恶化。这很可能包括该国收入最高的前10%人群,国家依靠他们缴纳约75%的个人所得税总额。
Behind the unrest are simmering social issues that law and order can’t fix. A backlash against rising inflation is feeding protests and unions’ call for a strike on Nov. 5, even if Macron has little control over Donald Trump’s inflationary war of choice in the Middle East. Fed-up students pessimistic about their future echo increasingly widespread dissatisfaction with public services; two-thirds of the population thinks they’ve gotten worse. And that likely includes many of the country’s top 10% of earners, on whom the state relies for around 75% of its total income tax take.
民众对国家的耐心正在耗尽,但国家的应对能力也在衰退——明年法国光支付利息就将达约730亿欧元,超过其国防预算。
Patience with the state is running thin, but so is its ability to respond — next year France will pay around €73 billion in interest alone, more than its defense budget.
关键在于一种经济模式:它在发达国家中公共支出领先,却似乎已失去动力。这实际上是一种慢性而非急性病症,历届政府在社会转移支付上花费更多,却未能带来维持这些支出所需的生产率增长,从而加剧了病情。法国央行前行长弗朗索瓦·维勒鲁瓦·德·加洛在新书中将其比作债务成瘾者,即使药效递减仍不断加大剂量。他的建议包括激励工作和财富创造,同时遏制公共支出向养老金倾斜的趋势。
What is at stake is an economic model that leads the rich world in public spending, yet appears to be running out of steam. It’s effectively a chronic, rather than acute, condition, worsened by successive governments spending more on social transfers without delivering the productivity growth required to sustain them. Former Bank of France Governor Francois Villeroy de Galhau, in a new book, likens it to an debt addict who takes larger and larger doses even as the drug becomes less effective. His recommendations include incentivizing work and wealth creation, while halting the skew of public spending toward pensions.
部分人寄希望于六个月后的总统大选能团结国家支持这种新气象。马克龙亲历过新任法国国家元首上台时的狂喜,以及随后渴望推出断头台的冲动,他呼吁公民把愤怒留到投票箱里发泄。如果现政府能达成预算协议,避免再次发生“五月风暴”,下一任爱丽舍宫主人就有机会在议会组建多数派,更好地管理公共财政、治愈社会创伤。
The hope in some corners is that presidential elections in six months’ time can rally the country behind such a new dawn. Macron, who has first-hand experience of the euphoria that greets a new French head of state before the itch to bring out the guillotine sets in, is asking citizens to save their anger for the ballot box. If a budget deal can be clinched by the current government and another May 1968 can be avoided, the next occupant of the Elysee has a shot at building a majority in parliament capable of doing better at managing public finances and healing society.
这种情形的问题在于,民意调查和议会目前的组成显示,选民分裂且意见不一,这种局面可能会比马克龙的任期更持久。政治极端势力在总统大选中声势高涨,提出的预算方案看似不切实际——甚至彻头彻尾的危险——且不愿在养老金等问题上面对现实。无论谁获胜,悬浮议会的风险依然存在。这或许不如一个决心与欧盟伙伴决裂的议会多数派有害。但这并不利于推动雄心勃勃的积极变革。勒庞近期的言论大谈法国的“复兴”,但即便是她,或许也会因法国街头动荡的程度而感到不安。
The problem with this scenario is that opinion polls and the current composition of parliament show a fragmented and divided electorate that could outlast Macron. The political extremes are riding high in the presidential race, offering budget plans that look unrealistic — even downright dangerous — and unwilling to face reality on issues like pensions. And regardless of who wins, a hung parliament is still a risk. That might be less harmful than a parliamentary majority intent on breaking with European Union partners. But it doesn’t bode well for pushing through ambitious, positive change. Le Pen’s recent rhetoric has talked up a “renaissance” in France but even she might be rattled by the level of unrest on French streets.
值得重申的是:法国不是2010年前后的希腊。但即使不至于导致法国上一次经历的那种主权违约——那要追溯到1790年代——不断攀升的债务负担依然会让人痛苦不堪。市场反应可能比政府精心制定的计划更快。当前投资者的情绪表明,政府在几个糟糕选项中做出了明智选择。但未来还有更多抉择,这种平静可能不会持久。
It bears repeating: France is not Greece circa 2010. But being strangled by a mounting debt burden can still be painful even if it doesn’t lead to the kind of sovereign default France last experienced in the 1790s. Markets can move quicker than governments’ best-laid plans. The current investor mood is a recognition that the government has chosen wisely from several bad options. Yet there are more choices to come, and the calm may not last.