在苹果公司周一收盘后发布财报之际,其股价近几个月的飙升让这家iPhone制造商几乎没有容纳失望的余地。
The runup in Apple Inc. shares in recent months has left the iPhone maker little room for disappointment when it reports earnings after the bell on Monday.
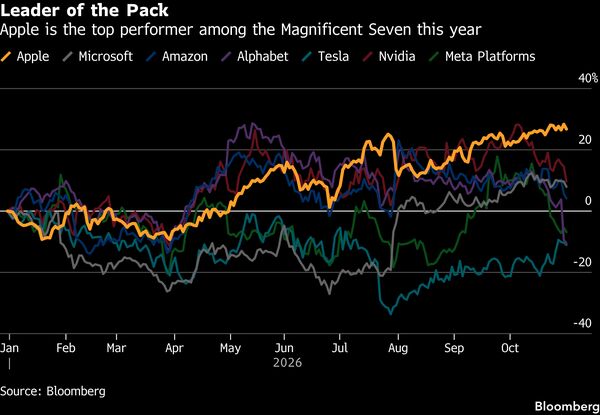
自6月下旬触底以来,该股已攀升25%,市值增加约1万亿美元。由于该公司的稳定营收增长和不断上升的自由现金流,为那些对Alphabet公司和亚马逊公司等大型同行在人工智能基础设施上大举支出感到担忧的投资者提供了一个避风港。
The stock has climbed 25% from a low in late June, adding roughly $1 trillion in market value, as the company’s steady revenue growth and rising free cash flow have offered a haven for investors balked by concerns about heavy spending on AI infrastructure by megacap peers like Alphabet Inc. and Amazon.com Inc.
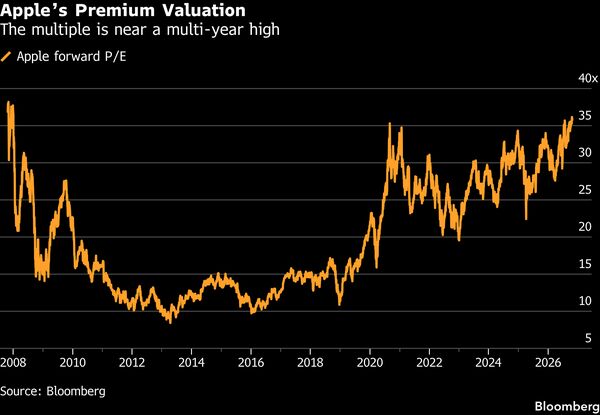
涨幅使得该股的交易估值达到2008年以来的最高水平,一旦公司的业绩不及预期,将变得格外脆弱。根据彭博社汇编的数据,按照未来12个月的预期收益计算,其市盈率达到36倍,几乎是标普500指数的两倍。
The gains have left the stock trading at the priciest levels since 2008, making it particularly vulnerable if the company’s results fall short of expectations. At 36 times earnings expected over the next 12 months, the shares are almost twice as expensive as the S&P 500 Index, according to data compiled by Bloomberg.
Tandem Investment Advisors联合首席投资官本·卡鲁(Ben Carew)表示:“苹果的历史估值处于99%的分位数,当一个股票定价如此充分时,任何意料之外的情况出现都会带来风险。目前它起到了避险的作用,但如果其增长弱于市场预期,就会让人觉得它并非那么安全,我们可能会看到估值倍数被重新评级。”持有该股票的卡鲁补充说,这个风险苹果的观察者应该不会陌生。三个月前,由于零部件短缺拖累了季度营收预期,该股遭遇了16个月来最糟糕的单日跌幅。
“Apple is in the 99% percentile of its historical valuation, and when something is priced so fully, there’s risk if something unexpected comes along,” said Ben Carew, co-chief investment officer at Tandem Investment Advisors, which holds the stock. “Right now it acts as a flight to safety, but if its growth is weaker than the market anticipates, that would make people feel it isn’t as safe, and we could see the multiple get re-rated.”It’s a risk that should be familiar to Apple watchers. Three months ago, the stock suffered its worst one-day decline in 16 months after component shortages weighed on its quarterly revenue forecast.
华尔街预计第四财季营收将增长11%至1135亿美元,净利润将增长6%至292亿美元。根据彭博社汇编的分析师平均预期,尽管这将使苹果创下自2021年以来最佳的销售增长年(增长15%),但未来两年的扩张速度预计将放缓。
Wall Street is expecting fiscal fourth-quarter revenue to rise 11% to $113.5 billion and net income to increase 6% to $29.2 billion. While that would cap Apple’s best year for sales growth since 2021 at 15%, the expansion is expected to slow in the next two years, according to the average of analyst estimates compiled by Bloomberg.
苹果的财报将首次让人真正深入了解其新款折叠屏iPhone的受欢迎程度。该设备于上个月上市,公司称需求“绝对非同寻常”,发货时间已推迟到明年。然而,分析师认为这可能反映出供应有限,而关于Duo屏幕在有限使用后出现裂纹的报道可能会削弱该产品对非早期尝鲜者的吸引力。
Apple’s report will offer the first real insight into the popularity of its new foldable iPhone. The device went on sale last month and the company said demand has been “nothing short of extraordinary,” with delivery times being pushed out to next year. However, analysts believe that could reflect limited supply availability, while reports of Duo screens cracking after limited use could diminish the product’s appeal among those who aren’t early adopters.
Duo对苹果至关重要。它不仅代表了该公司旗舰产品多年来最大的设计变动,而且起售价为1999美元,投资者希望这一高端定价能推动增长。据彭博情报(Bloomberg Intelligence)估计,随着消费者从价格较低的Pro和Pro Max型号转购,这款手机在2027财年可能会产生280亿美元至320亿美元的销售额,并拉高平均售价。
The Duo is critical for Apple. Not only does it represent the biggest design change to the company’s flagship product in years, but it starts at $1,999, and investors are hoping that premium price tag will boost growth. The phone could generate $28 billion to $32 billion in fiscal 2027 sales and lift average selling prices as consumers migrate from less expensive Pro and Pro Max models, according to Bloomberg Intelligence estimates.
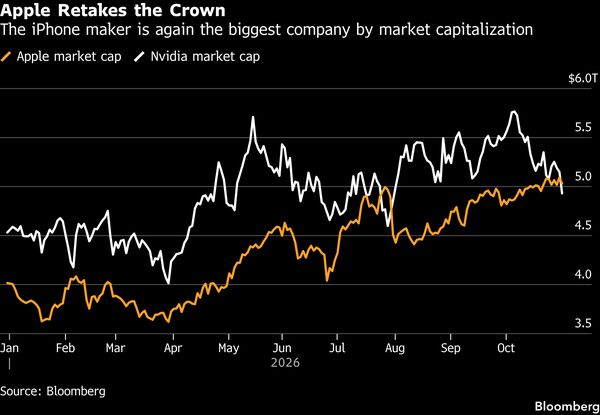
上周,Alphabet和Amazon令人失望的财报导致投资者纷纷抛售涉足人工智能的股票,让惠及苹果的科技股避险交易显露无遗。费城半导体指数周五下挫7.2%,创下6月以来最差表现,而苹果股价则跑赢标普500指数,跌幅为1.2%。由于英伟达公司(Nvidia Corp.)的股价被卷入抛售潮,苹果在周五超越这家芯片制造商,自7月以来首次成为全球市值最高公司,市值达5.03万亿美元。
The tech haven trade benefiting Apple was on display last week when disappointing earnings reports from Alphabet and Amazon sent investors fleeing AI-exposed stocks. The Philadelphia Stock Exchange Semiconductor Index tumbled 7.2% on Friday, its worst session since June, while Apple shares outperformed the S&P 500 with a decline of 1.2%. With Nvidia Corp. shares swept up in the selloff, Apple overtook the chipmaker on Friday to become the world’s most valuable company for the first time since July with a market capitalization of $5.03 trillion.
尽管苹果的营收增长落后于大多数大型科技同行,但该公司在自由现金流方面表现突出。随着投资者对人工智能支出狂潮产生怀疑,自由现金流已成为一个至关重要的指标。预计其2026财年的自由现金流将增长40%以上,达到1415亿美元,并且在未来三个财年中预计还会有进一步增长。相比之下,Alphabet、Meta和亚马逊的自由现金流赤字预计将持续下去。
While Apple’s revenue growth lags behind most Big Tech peers, the company stands out in free cash flow, which has become a critical metric as investors turn skeptical of the AI spending spree. For its 2026 fiscal year, free cash flow is expected to expand more than 40% to $141.5 billion, with further growth expected in the next three fiscal years. In contrast, Alphabet, Meta and Amazon have free cash flow deficits that are expected to continue.
纽伯格伯曼(Neuberger Berman)高级研究分析师丹尼尔·弗拉克斯(Daniel Flax)表示:“市场很欣赏苹果在自由现金流方面的实力,如果它能保持这一点,我认为该股票可以在当前水平上创造额外的价值。它执行产品周期并将其转化为强劲自由现金流增长的能力,才是对该股票最重要的事情,而初步迹象至少表明市场对Duo有很高的兴趣。”
“The market appreciates Apple’s strength on free cash flow, and if it can continue with that, I think the stock can generate additional value from current levels,” said Daniel Flax, a senior research analyst at Neuberger Berman. “Its ability to execute on the product cycle and translate that to strong free cash flow growth is what’s going to matter most for the stock, and the initial signs, at least, are that there’s a lot of interest for the Duo.”
尽管如此,高市盈率与低增长的结合还是减弱了华尔街对该股票的热情。自苹果7月下旬发布上一份财报以来,至少有六位分析师下调了评级。Loop Capital在10月将该股票评级从买入下调至持有,理由是iPhone出货量趋势;美国银行(Bank of America)周五将其从美国最佳投资理念1号名单中移除,并写道:“鉴于相对于市场共识存在潜在的逆风,我们对近期走势持谨慎态度。”
Still, the combination of a high multiple and low growth has tempered Wall Street’s enthusiasm for the stock. Since Apple’s last report in late July, at least six analysts have downgraded their ratings. Loop Capital cut the stock to hold from buy in October, citing iPhone shipment trends, and Bank of America removed it from its US 1 list of best investment ideas on Friday, writing that it is “cautious on near-term setup given potential headwinds relative to consensus.”
在彭博社追踪的分析师中,建议买入的比例不到60%,而微软、亚马逊和Meta的这一比例则超过90%。此外,该股票的交易价格高于分析师的平均目标价,使其成为“七巨头”中唯一在未来12个月内预期回报率为负的股票。
Fewer than 60% of the analysts tracked by Bloomberg recommend buying, compared with a rate of more than 90% for Microsoft, Amazon and Meta. Furthermore, the stock is trading above the average analyst price target, making it the only Magnificent Seven stock with a negative implied return over the coming 12 months.
Tandem的卡鲁表示:“估值是苹果面临的关键风险,但它确实应该享有某种溢价,因为其商业模式的确定性要高得多。我们在科技行业其他地方看到的波动,反映出它们的情况看起来有多么不确定。除非有一份真正让苹果的情况受到质疑的财报——这是我无法预见的,否则它至少应该能免受其中一些波动的影响。”
“Valuation is the key risk facing Apple, but it does deserve some kind of premium since there is a lot more certainty around its business model,” Tandem’s Carew said. “The volatility we’re seeing elsewhere in tech reflects how uncertain things seem for them. Absent a report that really calls things into question at Apple, which I can’t foresee happening, it should at least remain immune from some of that volatility.”