瑞银集团欧洲股票首席策略师兼衍生品主管格里·福勒表示,在近期人工智能相关股票回调之后,超大规模数据中心运营商的估值看起来很有吸引力,因为市场对人工智能周期的定价较实际可能持续的时间更短。
Hyperscaler valuations look attractive after the recent AI unwind as the market prices in a shorter AI cycle than is likely to play out, according to Gerry Fowler, chief European equity strategist and head of derivatives at UBS AG.
他在接受彭博电视台采访时表示:“当超大规模运营商的交易市盈率降至20倍以下,而其营收正以每年10%到20%的速度增长时,你实际上是在采取相当消极的看法。因此,我认为市场有相当大的意愿重新买入。”
“When you’ve got hyperscalers trading under 20 times now, when their revenues are growing 10 to 20% per annum, you’re taking a fairly negative view. So I do think there’s quite a lot of appetite for buying back into this,” he said in a Bloomberg Television interview.
福勒表示,超大规模运营商可能正在接近其巨额人工智能支出开始产生回报的节点。他预计2027年可能会出现一个拐点,届时数据中心的交付将释放积压订单,且营收开始追赶资本支出。他还补充说,市场上的资金并没有消失,而是转向了诸如内存制造商等供应商,这些供应商现在开始向投资者返还资金。
The hyperscalers may be nearing the point where their heavy AI spending starts producing returns, Fowler said. He sees a potential inflection in 2027, as data-center deliveries unlock backlogs and revenue begins to catch up with capex. Cash has not disappeared from the market, he added, but shifted toward suppliers such as memory makers that are now starting to return it to investors.
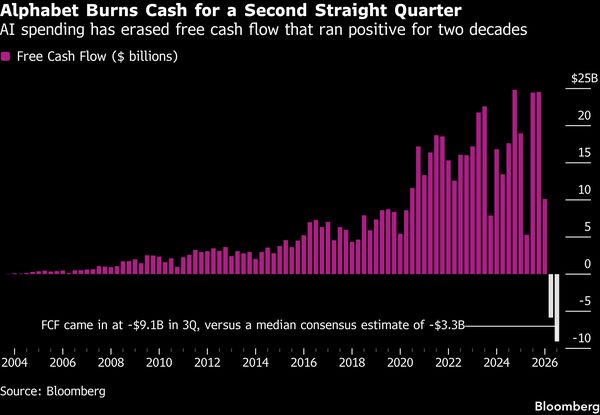
上周,Alphabet公布了连续第二个季度的自由现金流为负,这导致全球人工智能板块交易动荡,科技股权重极高的纳斯达克100指数基准在周五大跌3.5%,创下自6月以来表现最差的一天。
Alphabet posted a second straight quarter of negative free cash flow last week, helping to unsettle the global AI trade which saw the tech-heavy Nasdaq 100 benchmark dropping 3.5% on Friday, its worst day since June.
但在福勒看来,人工智能交易正开始超越第一波数据中心受益者。许多电缆、电力设备和其他基础设施供应商的产能已经售罄,订单排到了2027年甚至2028年,这使得盈利上调的空间缩小。由于市场受增长意外变化驱动,他认为下一阶段的交易必须来自其他领域。
But for Fowler, the AI trade is starting to move beyond the first wave of data-center beneficiaries. Many suppliers of cables, power equipment and other infrastructure are already sold out through 2027 or even 2028, leaving less room for earnings upgrades. With markets driven by unexpected changes in growth, he sees the next leg of the trade having to come from elsewhere.
他转而指出,那些协助建造新工厂的全球和欧洲工业企业是潜在增长点。阿斯麦控股公司就是一个例子,该公司在三星电子有限公司和SK海力士公司等内存制造商扩大产能时为其提供设备,而不是直接向数据中心销售产品。
He pointed instead to global and European industrials that help build new factories. ASML Holding NV is one example, supplying memory makers such as Samsung Electronics Co., Ltd. and SK Hynix Inc. as they expand capacity rather than selling directly into data centers.
他说:“因此,阿斯麦突然获得了盈利上调,你现在可以在欧洲工业领域的很大一部分中看到这种现象。”
“So all of a sudden ASML is getting upgrades, and you can see that across a decent chunk of the industrial landscape in Europe now,” he said.