根据最新研究,英国利率对通胀的抑制作用不如英格兰银行预期的那样大,这加强了本周加息的理由。
UK interest rates are not bearing down on inflation as much as the Bank of England thought, according to new research that strengthens the case for a hike in borrowing costs this week.
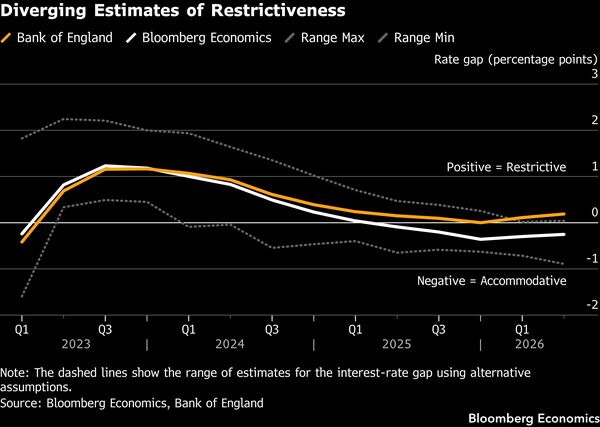
英格兰银行官员曾辩称,当伊朗战争导致能源价格飙升时,政策已处于限制性区间。然而,彭博经济学的一项研究发现,利率可能接近中性水平,这意味着货币立场既不抑制也不推高通胀。
BOE officials have argued that policy was already in restrictive territory when the Iran war sent energy prices soaring. However, a study by Bloomberg Economics found rates are likely to be close to their neutral level, meaning the monetary stance is neither weighing down nor pushing up inflation.
该研究表明,英格兰银行将需要采取行动,经济学家警告称,物价涨幅明年早些时候可能会升至4%以上——是央行目标的两倍。货币政策委员会普遍预计将在周四将基准利率上调25个基点至4%,这将是三年多来的首次加息,但对于还将加息多少仍存在不确定性。
The research suggests the BOE will need to take action, with economists warning that price growth is likely to climb above 4% early next year — double the central bank’s target. The Monetary Policy Committee is widely expected to lift its benchmark rate a quarter point to 4% on Thursday, its first hike in over three years, but uncertainty remains over how much further it will go.
彭博经济学经济学家西蒙·劳埃德和丹·汉森表示:“经济的演变,特别是最近几个季度,向我们表明,英格兰银行的政策立场对总支出的抑制作用甚微。考虑到当前的通胀背景,这主张以加息的形式重新校准政策。我们预计首次行动将在周四出台,随后在2月再次行动。” 在一连串数据显示英国经济在能源冲击下表现强劲后,利率可能不够高的担忧日益加剧。GDP在8月意外实现连续第三个月增长,使英格兰银行9月预测的第三季度0.4%增长显得过于悲观。劳动市场似乎也在趋于稳定。
“The evolution of the economy, particularly in recent quarters, suggests to us that the BOE’s policy stance is doing little to weigh on aggregate spending,” said Simon Lloyd and Dan Hanson, economists at Bloomberg Economics. “Given the current inflation backdrop, that argues for a re-calibration of policy, in the form of rate hikes. We expect the first move to come on Thursday with a follow-up move in February.”Concerns that rates may not be high enough have mounted after a string of data that has shown the British economy holding up against the energy shock. GDP unexpectedly grew for a third month in August, leaving the BOE’s September forecast of 0.4% growth in the third quarter looking pessimistic. The labor market too appears to be stabilizing.
货币政策委员会中有几位成员在9月投票维持利率在3.75%不变,他们辩称限制性政策有助于遏制通胀风险。然而,经济的韧性让他们关于闲置产能已扩大、政策正在打击需求的假设受到质疑。
Several members of the MPC who voted to keep rates at 3.75% in September argued that restrictive policy was helping to curb the risks from inflation. However, the economy’s resilience has cast doubt on their assumption that spare capacity has grown and that policy is hitting demand.
劳埃德和汉森表示:“我们的观点是,经济可能更接近其无通胀的速度限制,这与央行对支出的政策立场总体保持中性是一致的。”
“Our view is that the economy is probably a little closer to its non-inflationary speed limit, which is consistent with the central bank’s policy stance being broadly neutral for spending,” Lloyd and Hanson said.
这一判断的关键在于产出缺口,即实际GDP与经济潜在产能之间的差额。更高的需求将表明闲置产能正在耗尽;更强的供给则意味着缺口保持稳定或在扩大,这对通货膨胀来说是一个更有利的结果。
Key to the judgment is the output gap, the difference between actual GDP and the economy’s potential capacity. Higher demand would suggest spare capacity is being used up; stronger supply would mean the gap is steady or growing, a more benign outcome for inflation.
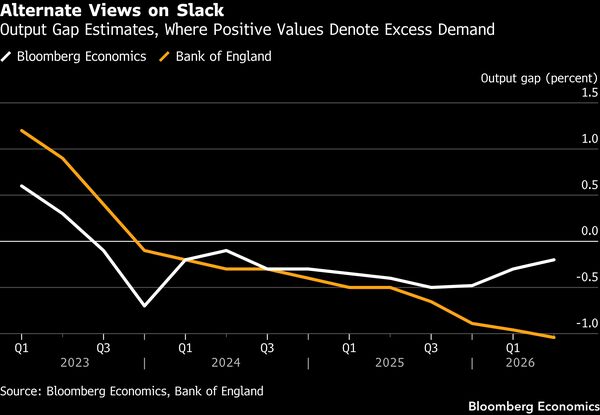
劳埃德和汉森表示:“英国央行似乎采取了后一种观点。尽管GDP持续超出预期,但英国央行一直辩称,经济中的闲置产能一直在扩大。”
“The BOE appears to have taken the latter view,” Lloyd and Hanson said. “Even though GDP has persistently beaten expectations, it has continued to argue that slack in the economy has been widening.”
彭博经济研究的建模显示,基于英国央行对产出缺口的看法,利率可能是具有限制性的。“相比之下,我们自己对超额需求的估计一直保持相对稳定。自2023年第四季度以来,该指标在零点几个百分点的区间内波动,至2026年第二季度结束时为潜在产值的-0.2%。”
Modelling by Bloomberg Economics shows that rates are likely to be restrictive based on the BOE view of the output gap. “In contrast, our own estimate for excess demand has stayed relatively stable. Since 4Q23, it has varied within a band of a few tenths, finishing 2Q26 at -0.2% of potential.”