两家投资公司正寻求推出交易所交易基金,让零售投资者押注对人工智能公司潜在信用违约的恐惧,而就在AI交易经历近年来最剧烈的一轮抛售之际。
Two investment firms are seeking to launch exchange-traded funds that would let retail investors bet on fear about potential credit defaults at artificial intelligence companies, just as the AI trade reels from one of its sharpest selloffs in years.
Tuttle Capital Management和Defiance ETFs已向美国证券交易委员会提交申请,拟推出与CoreWeave Inc.和Oracle Corp.的信用违约互换(CDS)挂钩的基金,Defiance还针对Meta Platforms Inc.提交了相关产品。这些衍生品通常被机构用来对冲违约风险,也会被打包成与高度杠杆ETF挂钩的产品,后者跟踪的是对AI建设高度敞口的上市公司篮筐,包括芯片制造商。
Tuttle Capital Management and Defiance ETFs have each filed with the US Securities and Exchange Commission to offer funds tied to credit-default swaps separately on CoreWeave Inc. and Oracle Corp., and Defiance has one tied to Meta Platforms Inc. The derivatives, typically used by institutions to hedge against default, would also be packaged into highly leveraged ETFs linked to baskets of companies heavily exposed to the AI buildout, including chipmakers.
这些产品旨在利用市场对AI借贷热潮中企业承担债务过重的日益增长的担忧。自10月峰值以来,纳斯达克指数下跌了15%,CoreWeave和Oracle等公司发行的债券的保险成本飙升至历史新高,奖励了押注信用恶化走势的投资者。
The offerings seek to capitalize on growing fears that companies at the center of the AI borrowing boom are taking on more debt than they can handle. As the Nasdaq slumped 15% from its October peak through Thursday, the cost of insuring debt issued by companies including CoreWeave and Oracle surged to new highs, rewarding investors who had bet on deteriorating creditworthiness.
“总有ETF能对应某个时刻,”Baird Strategas首席ETF策略师Todd Sohn表示,“不过这个产品确实有些棘手,因为CDS并非常见的工具,此前也尝试过。”事实上,这不是华尔街第一次将信用违约互换带给更广泛的投资者。在2008年金融危机期间,投资者曾利用这些衍生品押注与抵押贷款相关的债务。但ProShares于2014年推出首批CDS ETF后,这些产品表现不佳并最终关闭。
“There is always an ETF to meet a certain moment,” said Todd Sohn, chief ETF strategist at Baird Strategas. “This one is tricky, though, because CDS is not exactly a common instrument and has been tried before.”Indeed, this isn’t Wall Street’s first attempt to bring credit-default swaps to a wider audience. The derivatives gained wider attention during the 2008 financial crisis, when investors used them to bet against mortgage-related debt. But when ProShares launched the first CDS ETFs in 2014, the products struggled and eventually closed.
与那些追踪更广泛CDS宇宙的前期基金不同,新推出的产品针对个别公司以及AI热潮,而后者持续力正受到越来越多的审视。这些ETF将与做空和期权工具竞争——后者是零售投资者已经可以使用的押注个股下跌的工具。
Unlike those earlier funds, which tracked the broader CDS universe, the new offerings target individual companies and an AI boom whose staying power has come under growing scrutiny. The ETFs would compete with short selling and options, tools that retail investors can already use to bet against stocks.
Tuttle Capital 提议推出五只主动管理的 ETF,实际上让散户投资者能够购买针对 AI 相关公司的杠杆信用保护。每只基金的设计目标是:当发行人的债务状况恶化、信用利差扩大时上涨;若前景好转、信用利差收窄,则下跌。Defiance 计划推出四只结构类似的 ETF。
Tuttle Capital is proposing five actively managed ETFs that effectively let retail investors buy leveraged credit protection on AI-related companies. Each fund is designed to rise when the issuer’s debt profile sags and credit spreads widen, or fall if the outlook brightens and the credit spreads narrow. Defiance plans to offer four ETFs that are similarly structured.
在某些情形下,投资者反而可能亏损——即使该公司股价暴跌——因为维持 CDS 保护的持续成本会在发生足以损害公司信用的不利事件之前,就侵蚀收益。
In some scenarios, investors instead could wind up losing money — even if the company’s shares are plunging — because the ongoing cost of maintaining protection with a CDS eats away at returns before anything bad enough happens to damage the company’s credit.
无论涨跌,波动都可能被放大数倍,因为基金经理计划使用借款来增厚收益。
The movements either way could be amplified many times over because the fund managers plan to use borrowed money to augment their returns.
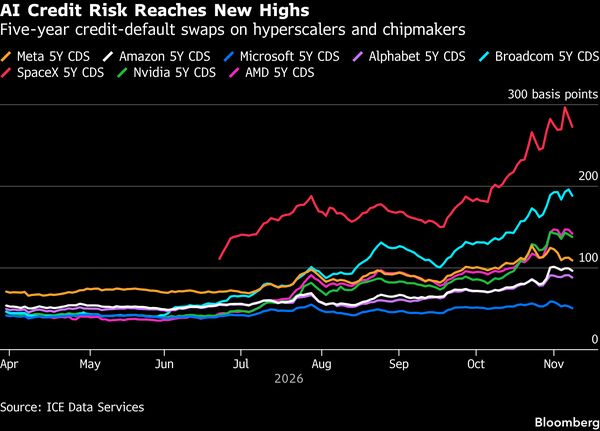
近几周,AI 交易出现逆转,原因是投资者日益担忧,这项技术的巨额支出可能需要数年才能回报,而民主党在国会选举中取得全面胜利,引发了更严格监管的预期。对保护的需求推动与超大规模云服务商和芯片制造商挂钩的 CDS 价格升至新高,而一年前这些价格几乎不存在。
The AI trade unraveled in recent weeks as investors grew increasingly concerned that enormous spending on the technology could take years to pay off while Democrats’ sweeping congressional victory raised the prospect of tighter regulation. Demand for protection has pushed the prices for CDS tied to hyperscalers and chipmakers to fresh highs, from almost nonexistent a year ago.
Oracle 在最大的超大规模云服务商中信用评级最低,普遍被视为 AI 债务风险的代名词。其五年期 CDS 上月创下历史新高,此前因担忧财报后的借贷狂潮会压垮已经不堪重负的债市,科技板块信用风险飙升。Oracle 披露,承诺到 2030 财年止,债务总额增长仅为 100 亿美元,这有助于缓解投资者的担忧。
Oracle has the weakest credit rating among the largest hyperscalers and is widely seen as a proxy for AI debt risk. Its five-year CDS hit a record last month as credit risk across tech spiked on fears a post-earnings borrowing binge would overwhelm already swamped debt markets. Oracle disclosed that it was committing to just $10 billion of gross debt growth through fiscal 2030, helping ease investor angst.
与此同时,CoreWeave 通过数十亿美元的交易,同时进入了美国高收益债市场和贷款市场,为其扩张融资。与这家“新云”公司挂钩的合约(该合约一年前开始交易)上月创下历史新高,此前该公司表示将从保险公司动用大量资金池,令投资者感到不安。这些互换目前定价显示,未来五年内违约的概率超过 60%。
CoreWeave, meanwhile, has tapped both the US high yield and loan markets with multi-billion dollar deals to finance its buildout. Contracts tied to the neocloud, which started trading a year ago, hit a fresh all-time high last month after the company’s talk of tapping vast pools of capital from insurers spooked investors. The swaps are currently pricing in a more than 60% chance of default within the next five years.
甲骨文、Meta和CoreWeave的代表未立即回复征求置评的信息。甲骨文和Meta发行的债务具有投资级信用评级。CoreWeave被标准普尔全球评级评为B级。
Representatives for Oracle, Meta and CoreWeave didn’t immediately respond to messages seeking comment. Debt issued by Oracle and Meta carries investment-grade credit ratings. CoreWeave is rated B by S&P Global Ratings.
与10家最大超大规模云服务商和芯片制造商挂钩的信用违约互换交易量达到历史新高,使这些互换成为金融部门之外美国市场中交投最活跃的合约之一。
Trading volumes for CDS tied to the 10 largest hyperscalers and chipmakers are at record highs, making the swaps among some of the most actively traded US contracts in the market outside of the financial sector.
据巴克莱银行信贷策略师贾加尔·帕特尔对交易存储库数据的分析,甲骨文CDS是美国市场交投最活跃的单一名称合约,交易量高达创纪录的476亿美元,而今年1月至10月30日仅为87亿美元。CoreWeave交易量为46亿美元,较1.45亿美元有所上升。
Oracle CDS are by far the most active single-name contract in the US market at a record $47.6 billion, from just $8.7 billion this year through Oct. 30, according to an analysis of trade repository data by Barclays Plc credit strategist Jigar PatelCoreWeave volumes stand at $4.6 billion, up from $145 million.
彭博情报分析师詹姆斯·塞弗特表示,新的CDS挂钩交易所交易基金可能难以赢得散户交易者的青睐,因为其复杂性,不过更深的人工智能抛售可能会改变这一局面。
The new CDS-linked ETFs will likely struggle to win over retail traders because of their complexity, though a deeper AI selloff could change that, according to Bloomberg Intelligence analyst James Seyffart.
“任何读过有关全球金融危机内容的普通人都会知道这些是什么。但他们会真的购买基于此的交易所交易基金吗?也许会。但我持怀疑态度,”塞弗特说。“不过,无论多么小众,一款在正确时间出现在正确位置的产品都可能产生滚雪球效应。”
“Any random person who has read anything about the global financial crisis is going to know what these are. But will they actually buy an ETF based on it? Maybe. But I’m skeptical,” Seyffart said. “Still, no matter how niche, a product at the right place in the right time can have a snowball effect.”