一些最常用的信用对冲手段正在失效,而这正值市场对人工智能相关债务激增的担忧日益加剧之际。
Some of the most popular ways to hedge credit are breaking down just as concerns mount over the flood of artificial intelligence-linked debt.
投资者长期以来依赖信用违约互换指数,将其作为一种快速且流动性强的方式来保护自己免受损失。但根据彭博汇编的数据,这些基准未能反映企业债券风险溢价的飙升。这种差距扩大意味着,利用这些工具对冲投资组合损失的投资者获得的保护比预期的要少。
Investors have long relied on credit-default swap indexes as a quick and liquid way to protect themselves against losses. But those benchmarks have failed to reflect a surge in risk premiums on corporate bonds, according to data compiled by Bloomberg. The widening gap means investors using the instruments to offset losses on their portfolios are getting less protection than expected.
高盛分析师阿曼达·莱纳姆(Amanda Lynam)率领的团队在周四致客户的报告中写道:“与更广泛的表现良好市场相比,人工智能相关信用的疲软,导致许多投资者开始质疑哪种对冲工具最适合其投资组合。”他们补充道:“鉴于市场如此关注与人工智能相关发行挂钩的特有风险,以及建设扩张的资金核算问题,一个关键问题是宏观指数是否仍然是有效的对冲工具。”
“Weakness in AI-related credit relative to the broader performing market has led many investors to question which hedges are best suited for their portfolios,” Goldman Sachs analysts led by Amanda Lynam wrote in a note to clients on Thursday. “With so much focus on idiosyncratic risks tied to AI-related issuance and the funding arithmetic of the buildout, a key question is whether macro indices remain effective hedges,” they added.
这种脱节出现之际,全球最大信用市场的交易日益集中在与个别公司挂钩的单一实体信用违约互换上,例如亚马逊、Meta Platforms 和 Alphabet。这些公司为资助人工智能投资而进行的历史性借贷狂潮,给交易员带来了新的风险来源。当标的资产与对冲工具在价值上保持一致时,对冲交易效果最好。
The disconnect comes as trading in the world’s biggest credit market is increasingly focused on single-name credit default swaps tied to individual companies such as Amazon.com Inc., Meta Platforms Inc. and Alphabet Inc., whose historic borrowing binge to fund AI investment has created a new source of risk for traders. Hedging transactions work best when the underlying asset and hedging instrument are aligned in value.
TabCap Investment Management 首席执行官兼联合创始人大卫·皮科克(David Peacock)表示:“当你用指数对冲现金信用时,两者之间的初始估值差距很重要。”
“When you hedge cash credit with indexes, the starting valuation gap between the two matters,” said David Peacock, chief executive officer and co-founder at TabCap Investment Management, a hedge fund investing in credit indexes and related instruments.
CDS 与债券指数之间的相关性有波动的历史,这使得任何对冲都不完美。然而,随着信用市场走向 2022 年以来的首个年度亏损,这种经过考验的策略如今失效,可能迫使投资者更多地使用替代方案。
The correlation between CDS and bond indexes has a history of fluctuating, making any hedges imperfect. However the breakdown of the tried-and-tested strategy now, as credit markets head for their first annual loss since 2022, may force investors to make greater use of alternatives.
美国的 CDX 和欧洲的 iTraxx Crossover 等 CDS 指数,每天仍吸引着数百亿美元名义本金的交易量。基金经理通常将其作为战术工具,用于买入保护以对冲债券持仓恶化的风险,但它们越来越多地成为交易员押注大盘走势的工具。
CDS indexes like the CDX in the US and Europe’s iTraxx Crossover still attract trades worth tens of billions of dollars in notional volumes every day. Fund managers typically use them tactically to buy protection against the chance of their bond holdings going sour, though they have increasingly become tools for traders to bet on broader moves.
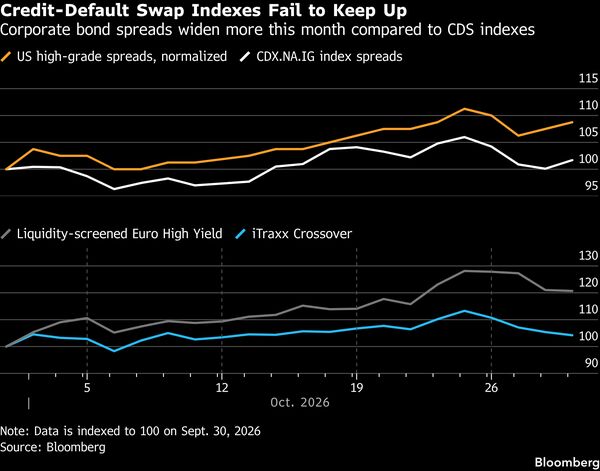
随着对 AI 的担忧加剧,投资者更倾向于直接敞口于主导市场因素,而非可能独立于其成分股变动的指数。因此,追踪 125 家北美公司债务的 CDX 利差扩大速度,不及美国投资级企业债券指数的五分之一。两者的相关性已降至五年均值的一半左右。
As AI fears mount, investors have preferred direct exposure to the dominant market factor rather than indexes that can move independently of their constituents. As a result, spreads on the CDX, which tracks the debt of 125 North American companies, have widened at less than a fifth of the pace of the US high-grade corporate bond index. The correlation between the two has fallen to about half its five-year average.
“在其他条件相同的情况下,如果单名 CDS 而非指数成为首选工具,那么通过指数进行看空宏观对冲的需求可能不会像以往那样大幅跃升,”德国商业银行信贷策略主管 Marco Stoeckle 表示。
“All else equal, if single name CDS, not indexes, are the tool of choice then demand for bearish macro overlays via indexes might not jump as much,” said Marco Stoeckle, head of credit strategy at Commerzbank AG.
欧洲情况类似,主要包含垃圾级公司 CDS 的 iTraxx Crossover 指数,表现落后于一项流动性次投资级债券指标。根据彭博编制的数据,10 月每当垃圾债利差扩大 3 个基点,CDS 指数利差扩大不到 1 个基点。
Listen: AI Bond Blitz Upends Investor Benchmarks It’s a similar picture in Europe, where the iTraxx Crossover index of CDS on mostly junk-rated companies has trailed a gauge of liquid sub-investment grade bonds. For every three basis points of widening in the junk bond spread in October, the CDS index spread gained less than one, based on data compiled by Bloomberg.
所谓的“新云”公司 CoreWeave Inc 缺席指数成分股——该公司是最近 AI 信贷抛售的核心——是一个因素,而指数在 9 月的常规成分股调整也具有重要意义。
The absence of CoreWeave Inc — the so-called neocloud firm at the center of the most recent selloff in AI credit — has been a factor, while a regular update of the index’s composition in September was also significant.
TabCap 的 Peacock 将这种欧洲市场的背离描述为“不可持续”,称其“既源于市场技术面因素,也源于其他因素”。他补充说,该缺口最近已开始回归至更典型的水平。
TabCap’s Peacock described the European disconnect as “unsustainable,” saying it was “due to market technicals as much as anything else.”The gap has begun to revert to more typical levels recently, he added.
然而,随着市场情绪随对 AI 交易的信心起伏,这种扭曲可能还会持续一段时间。
However, with market sentiment rising or falling with confidence in the AI trade, the distortion may persist for a while longer.
“单一名义对冲仍有一定空间,”斯托克尔说。“问题始终在于对冲什么以及对冲到何种程度。”
“I still think the single-name hedge still has some mileage left,” Stoeckle said. “The question is always against what and to which extent you need to hedge.”