美国企业债券近几周出现反弹,吸引了寻求在股市动荡中避险的资金管理者的关注。
US corporate bonds have been rallying in recent weeks, drawing the attention of money managers seeking shelter from turbulence in stocks.
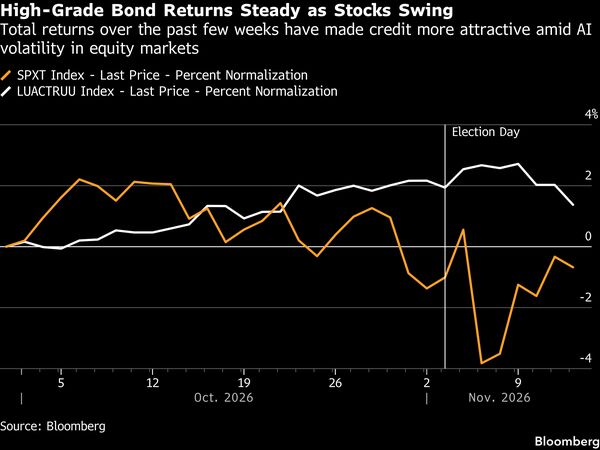
据彭博指数总回报数据,从9月底到周五收盘,美国高等级公司债务上涨了1.2%。同期标普500指数(含股息)下跌约1.1%,英伟达公司本周的困境提醒投资者市场可能多么脆弱。周五投资级公司债券的平均收益率为6%,接近金融危机以来的最高水平,让投资者有机会在未来几年潜在地锁定可观的固定收益。
High-grade US company debt gained 1.2% from the end of September through Friday’s close, according to Bloomberg Index total return data. The S&P 500 fell about 1.1% during that period, including dividends, with Nvidia Corp.’s woes this week reminding investors how fragile the market can be. Yields on investment-grade corporate bonds averaged 6% on Friday, near the highest levels since the financial crisis, giving investors a chance to potentially lock in solid income for years.
与此同时,尽管标普500指数自2023年以来基本翻倍,但其涨势显示出疲软迹象。今年以来该指数(含股息)上涨约11.5%。这大约是其2025年全年涨幅的三分之二,近几周来,对人工智能交易可持续性的担忧以及较高利率削弱了风险偏好。
Meanwhile, although the S&P 500 has essentially doubled since 2023, its momentum is showing signs of flagging. The index is up about 11.5% this year including dividends. That’s around two-thirds of its gain for all of 2025, as worries over the sustainability of the artificial intelligence trade and higher interest rates have dented risk appetite in recent weeks.
联邦赫密斯固定收益投资策略师凯伦·曼纳表示:“如果你认为股市还有进一步回调的空间,并将其与固定收益已知的收益率和收入水平进行比较,债券开始显得更具吸引力。”
“If you’re thinking that we have additional pullback to go in equity land, and you’re comparing that to the known yield and income level of fixed income, bonds begin to look more attractive,” said Karen Manna, fixed income investment strategist at Federated Hermes.
民主党人本月初在关键的中期选举中大获全胜,夺取了国会两院的控制权以及几个共和党传统优势选区的州长职位。选举结果引发了股市大幅抛售,投资者抛售科技股,预期国会将加强对数据中心建设和科技行业的总体监管。如果数据中心增长放缓,利润增长可能滞后,从而拖累股市。
Democrats swept key midterm races earlier this month, taking both chambers of Congress and several governorships in Republican strongholds. The election results triggered a sharp stock selloff as investors dumped technology shares on expectations of tighter congressional scrutiny of data center development and the tech industry more broadly. If data centers grow more slowly, profit growth could lag, weighing on stocks.
与此同时,这些项目开发放缓可能会减少科技公司为融资投资而发行的债券数量,从而有可能提振企业债券回报。而且,随着投资者所能承受的单一企业债务接近极限,科技公司似乎也在放缓债券发行步伐。最终结果是,美国高等级企业债券发行明年可能会放缓,而今年以来截至周四已增长28%并创下全年纪录。
At the same time, slower development for these projects could cut into the amount of bonds that tech companies sell to fund their investments, potentially helping corporate bond returns. And tech companies seem to be slowing down their bond sales anyway as investors reach their limits for how much debt they can take from individual corporations. The end result is the potential for US high-grade corporate bond sales to moderate next year after growing 28% this year through Thursday and reaching a full-year record.
摩根大通公司包括纳撒尼尔·罗森鲍姆在内的策略师本月在一份展望报告中写道:“退一步说,中期选举后及年底前,资产配置者面临的一个新问题是企业债券与股票的相对价值。我们怀疑这将成为年底前日益激烈的辩论话题。”美国银行公司包括尤里·塞利格在内的策略师表示,美国高等级企业债券发行明年可能从今年预期的2.1万亿美元降至1.9万亿美元,部分原因是人工智能热潮的融资渠道日益多元化,不再仅依赖企业债券。
“Taking a step back, one developing question for asset allocators post-midterms and into year-end will be the relative value of corporate bonds versus equities,” wrote JPMorgan Chase & Co. strategists including Nathaniel Rosenbaum in an outlook note this month. “We suspect this will be a growing debate into year-end.”
在发行量下降的背景下,宏利投资管理预计,未来五年美国大盘股年化回报率为6%,而美国投资级信用债年化回报率为5.1%。宏利投资管理多元资产解决方案团队首席投资官内森·图夫特表示,调整股票回报的风险后,高等级信用债显得相对更具吸引力。
US high-grade corporate bond issuance could decline next year to $1.9 trillion from an expected $2.1 trillion this year, partly because the AI boom is increasingly getting financed via a wide range of markets in addition to corporate bonds, according to Bank of America Corp. strategists including Yuri Seliger. Amid lower issuance, Manulife Investment Management expects US large-cap stocks to return 6% annually over the next five years, against 5.1% annual returns for US investment grade credit.
高等级企业债务部分吸引力在于其收益率仍维持在近几年高位附近,而年初收益率约为4.8%。本周公布的美国消费者价格指数报告显示通胀仍是个问题,这一担忧推动债券收益率在固定收益市场全年走高。
Adjusting the risk of the returns in equities, high-grade credit appears relatively attractive, said Nathan Thooft, chief investment officer of Manulife Investment Management’s multi-asset solutions team. Part of the appeal for high-grade corporate debt lies in yields that remain near multi-year highs after starting the year at around 4.8%.
虽然较高收益率曾周期性地拖累股市,但也促使部分投资者增加债券配置。总部位于伦敦的投资公司 Ruffer 自 7 月以来已将投资组合久期翻倍,升至两年多来的最高水平,该公司美国投资专家 Oli Shale 表示,这是通过增加固定收益敞口实现的。“此举旨在防范 AI 建设放缓可能损害经济增长并施压美股,同时也为了锁定有吸引力的收益率,”Shale 说。
The US consumer price index report this week signaled that inflation still remains a problem, a concern that has helped push up bond yields all year across fixed-income markets. While higher yields have periodically weighed on stocks, they have also pushed some investors to increase bond allocations. Ruffer, an investment firm based in London, has doubled its portfolio duration since July to the highest level in more than two years, by increasing its fixed income exposure, said Oli Shale, US investment specialist at the firm, via“The move is to protect against a slowdown in the AI buildout that may hurt economic growth and pressure US stocks, and to also capture an attractive yield,” according to Shale.
大型科技公司越来越多地利用的一个市场是芯片融资,这类融资最终往往会进入投资级债券市场。一些由算力支持的债券发行已在筹备中,虽然这些债务通常最初在私募市场由银行安排,但明年可能会通过发行债券进行再融资。
One market that big tech companies are increasingly tapping is chip financings, which can often end up in the investment grade market. Some bond sales backed by computing power are already in the works, and while the debt is often initially arranged in private markets and by banks, it could be refinanced with bonds next year.
例如,银行计划明年发行最多约 210 亿美元的高评级债券,作为博通公司 (Broadcom Inc.) 筹集的 630 亿美元融资包的一部分,用于帮助 AI 开发商 Anthropic PBC 融资采购芯片。
For instance, banks are planning to sell up to about $21 billion of high-grade bonds next year as part of a $63 billion funding package that Broadcom Inc. has pulled together to help finance chips for AI developer Anthropic PBC.
“到 2027 年,芯片融资肯定会增加,并可能对信用债造成一定压力,”L&G — Asset Management, America 多行业固定收益及投资策略主管 Anthony Woodside 说。鉴于当前收益率水平以及供给可能下降的潜力,他总体认为投资级信用债目前具有吸引力。
“Chip financing into 2027 is certainly expected to pick up and can weigh on credit a bit,” said said Anthony Woodside, head of multi-sector fixed income and investment strategy at L&G — Asset Management, America. He generally thinks high-grade credit looks attractive now given yields and the potential for declining supply.
明年股市是否会下跌,或企业债券是否会受损,目前尚不清楚。但随着科技公司潜在借贷减少,债券可能会看到美国企业风险溢价在最新一周收窄 5 个基点(即 0.05 个百分点)后继续收紧。周五利差平均为 86 个基点,略高于全年均值,但按过去二十年的标准来看仍相对较低。
It’s unclear whether equities will fall next year, or if corporate bonds will suffer. But with tech companies potentially borrowing less, the bonds could see US corporate risk premiums continue to tighten after narrowing five basis points, or 0.05 percentage point, in the latest week. Spreads averaged 86 basis points on Friday, a bit wider than the year’s mean but still relatively tight by the standards of the last two decades.
“股市波动加剧、部分信贷供给退出市场,加上绝对收益率走高,这为信贷资产带来了不错的潜在回报,”宏利的Thooft表示。信贷前沿:银行正在抛售大量AI债务(播客)
“A combination of more volatility in equity markets, plus some supply in credit coming off the table, and the fact that absolute yields are higher, is a recipe for decent return potential in credit,” Manulife’s Thooft said. Credit Edge: Banks Are Offloading a Glut of AI Debt (Podcast)