对大型科技公司来说,过去几周可谓动荡不安:中期选举以及对英伟达公司黄仁勋出人意料的罢免持续冲击华尔街。但有一只股票在乱局中岿然不动:苹果公司。
It’s been a wild few weeks for Big Tech, as the midterm elections and stunning ouster of Jensen Huang at Nvidia Corp. continue to rock Wall Street. But one stock has held firm through the chaos: Apple Inc.
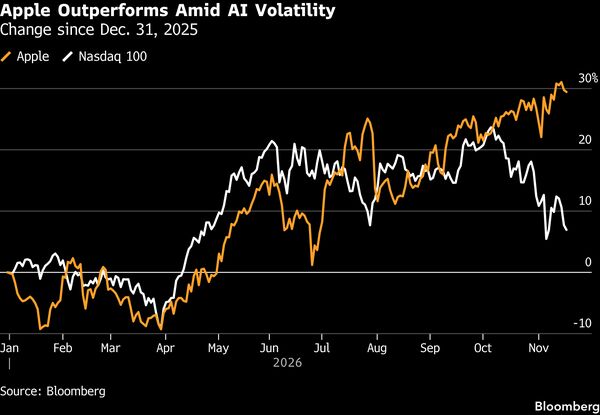
当投资者抛售一切与人工智能相关的股票时——从芯片制造商到超大规模云服务商,再到新型云服务提供商——苹果却继续稳步走高。该股今年上涨29%,使其成为“科技七巨头”中表现遥遥领先的最好公司,也是对标普500指数点数贡献最大的个股,在该指数7.2%的涨幅中占到28%。在此过程中,苹果还以5.1万亿美元的市值成为全球市值最高的公司。
While investors dump shares of everything tied to artificial intelligence, from chipmakers to hyperscalers to neocloud providers, Apple continues to grind higher. The stock is up 29% this year, making the company by far the best performer among the Magnificent Seven technology giants and the biggest points contributor to the S&P 500 Index, accounting for 28% of the benchmark’s 7.2% rise. Along the way, it’s also become the world’s largest company with a market capitalization of $5.1 trillion.
原因相当简单。当许多超大型竞争对手都在大举投入追逐人工智能时,苹果基本上置身事外,专注于销售iPhone和Mac,并为人们在这项新兴技术完全成熟后在其设备上使用它做准备。
The reason is fairly simple. While so many of its megacap rivals are spending heavily chasing AI, Apple is largely sitting on the sidelines, selling its iPhones and Macs and preparing for people to use the emerging technology on its devices when it’s fully developed.
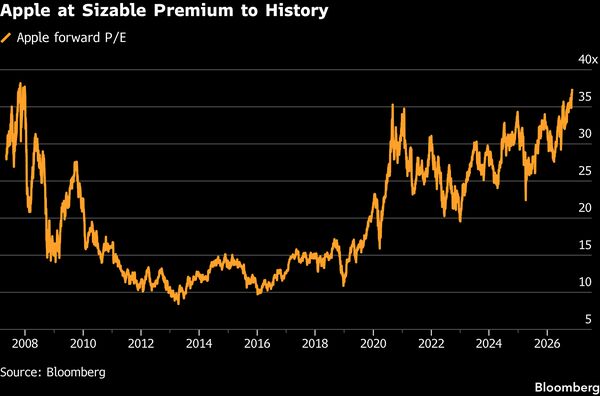
然而,买入一个AI避风港的成本正变得越来越高。苹果股价目前为未来12个月预期盈利的37倍,这一倍数自2007年以来未曾出现,使该股跻身标普500指数中估值最贵的25只股票之列。换句话说,其估值正接近可能让投资者在买入前三思的水平。
However, the cost of buying an AI haven is becoming increasingly steep. Apple shares are trading at 37 times earnings expected over the next 12 months, a multiple not seen since 2007, putting the stock among the 25 most expensive in the S&P 500. In other words, they’re approaching levels that are likely to make investors think twice about buying.
“关注苹果的人应该意识到,现在是鼎盛时期,”YieldMax ETFs策略师迈克·库说。“该股的波动率很低,但只会从这里往上走,而且考虑到其估值从历史角度看已被拉得如此之高,市盈率不可能再合理地上涨多少。把这些因素放在一起,你必须认识到部分溢价有可能被挤出。”投资者正押注苹果的稳定表现将持续。追踪市场对该股未来波动率预期的芝加哥期权交易所苹果波动率指数本月已下跌近10%,而纳斯达克100指数的波动率指标则跃升25%。
“People looking at Apple should realize that these are halcyon days,” said Mike Khouw, strategist at YieldMax ETFs. “The stock’s volatility is low, but can only go up from here, and the multiple can’t reasonably get much higher, considering how stretched it is from a historical perspective. When you put all that together, you have to recognize the potential for some of the premium to come out.”Investors are betting that Apple’s stability will continue. The CBOE Apple VIX, which tracks a market estimate of future volatility in the stock, has dropped almost 10% this month, while a volatility measure for the Nasdaq 100 Index has jumped 25%.
苹果今年推出了多款新产品,其中包括一款引发消费者抢购热潮的折叠屏iPhone,尽管其起售价接近2000美元。但苹果股价的强势,与其说是因为公司在做什么,不如说是因为它没有做什么,即没有在人工智能上大肆烧钱。而正是这种烧钱行为推高了其他许多超大型科技公司的资本支出,并耗尽了它们的现金流。
Apple has launched a number of new products this year, including a foldable iPhone that sparked a mania among shoppers despite a price tag that starts at almost $2,000. But the stock’s strength really is less about what the company is doing than what it isn’t, namely spending wildly on AI, which has driven up capital expenditures and depleted cash flows at so many other megacap tech companies.
Bernstein分析师马克·纽曼在11月12日给客户的报告中写道,避开这场竞赛使苹果“免受困扰上游股票(如半导体、存储及其他零部件)的AI数据中心资本支出下滑风险的影响,也免受超大规模云服务商当前所面临的自由现金流崩塌的影响”。
Avoiding that race has made Apple “immune to the risk of AI data center capex falling that plagues upstream stocks (such as semiconductors, memory and other components) and is also immune to the collapsing free cash flow that hyperscalers are currently seeing,” Bernstein analyst Mark Newman wrote in a note to clients on Nov. 12.
他补充说,考虑到公司的“客户忠诚度、盈利持久性、增长、自由现金流生成能力以及股东回报”,该股的估值倍数并不算离谱。当然,这并不意味着一切都是一帆风顺。
Considering the company’s “customer loyalty, earnings durability, growth, FCF generation and shareholder returns,” the stock’s multiple isn’t outrageous, he added. Of course, that’s not to say it’s all smooth sailing.
苹果本月早些时候给出了令人失望的利润率展望,因公司正应对供应限制,尤其是存储芯片的供应限制。而且其增长正在放缓。预计截至9月的2027财年营收将增长10%,而2026财年的增幅为15%。预计接下来两个财年的增速还将进一步放缓。
Apple gave a disappointing outlook for profit margins earlier this month as it grapples with supply constraints, especially for memory chips. And its growth is slowing. Revenue in fiscal 2027, which ends in September, is expected to rise 10%, versus growth of 15% in fiscal 2026. And that pace is expected to decelerate further in each of the next two fiscal years.
根据可追溯至2005年的数据,苹果的PEG比率为5.3,创历史新高。PEG比率是衡量股票价值的指标,通过将市盈率除以利润增长率计算得出。PEG比率高于1通常意味着股票被认为估值过高。相比之下,英伟达的PEG比率不到0.15,处于历史最低水平,因为预计其当前财年利润将翻倍,而其估值已大幅下跌。
Apple’s PEG ratio, a measure of a stock’s value that’s calculated by dividing its price-to-earnings ratio by its profit growth rate, stands at an all-time high of 5.3, based on data going back to 2005. A PEG ratio above 1 typically means a stock is considered overvalued. By comparison, Nvidia’s is less than 0.15, an all-time low, because its profits are expected to double in the current fiscal year and its valuation has tumbled.
苹果的估值似乎让华尔街犹豫不决。在彭博追踪的59位覆盖该股的分析师中,仅有36位给出买入评级,这在超大型股中属于较低的比例。
Apple’s valuation appears to be giving Wall Street pause. Of the 59 analysts tracked by Bloomberg who cover the stock, just 36 have buy recommendations, a low rate among megacaps.
这些股票的交易价格高于分析师的平均目标价,这意味着预计未来12个月股价将下跌。苹果是“美股七雄”中唯一一只隐含回报为负的股票。
The shares are trading above the average analyst price target, meaning they’re expected to decline over the next 12 months. Apple is the only Magnificent Seven stock with a negative implied return.
尽管如此,尼尔斯投资管理公司创始人兼投资组合经理丹·尼尔斯仍认为,苹果作为科技行业主导消费品牌的独特地位,依然是持有其股票的理由。他将苹果列为今年自己的五大首选股之一。他表示,如果人工智能继续发展,用户通过智能手机和笔记本电脑使用这项技术,苹果最终将从中受益;而如果人工智能周期逆转,该股也应能起到对冲作用。
Still, the company’s unique position as the tech industry’s dominant consumer brand remains a reason to own Apple shares, according to Dan Niles, founder and portfolio manager at Niles Investment Management, who named the stock one of his top five picks for the year. If AI development continues, Apple will ultimately benefit as users access the technology through their smartphones and laptops, and if the AI cycle turns, the stock should remain a hedge, he said.
“它今年碾压了其他科技股,这一事实恰恰说明了它为何如此有价值,”他说。“在市场偏好风险时期,它表现稳健;在市场避险时期,它的表现比同行好得多。它已经通过了严峻考验,没有理由认为这种态势不会在明年延续。除了估值——这一点我就是不喜欢——对于我们所处的环境而言,它是一只很棒的股票。”腾讯控股有限公司的股价在2026年已下跌38%,势将创下有记录以来最差年度表现。
“The fact that it has crushed other tech stocks this year shows you why it’s so valuable,” he said. “It holds up well in risk-on periods, and it holds up a lot better than peers when it’s risk off. It has passed the acid test, and there’s no reason to think those dynamics won’t continue next year. Outside of the valuation, which I just don’t like, it’s a great stock for the environment we’re in.”Tencent Holdings Ltd.’s shares have declined 38% in 2026, putting them on track for their worst year on record.
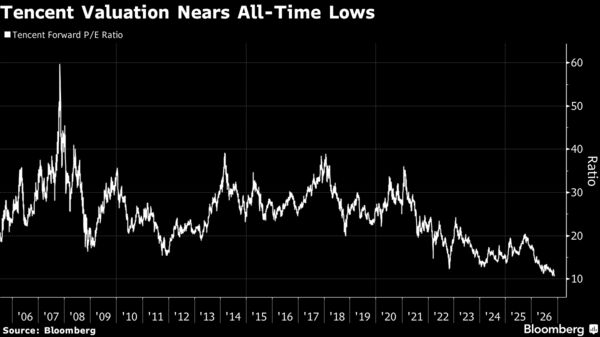
该股的估值倍数接近历史最低水平,远期市盈率为11倍。周四香港市场重开时,腾讯股价可能进一步下跌,此前与腾讯走势密切相关的普罗苏斯公司在欧洲交易时段下跌近8%。腾讯最新财报显示,由于加倍投入人工智能投资,公司出现大额现金流出,同时营收未达预期。周三将公布财报的顶级科技新闻
The stock’s valuation multiple is close to a record low, with a forward price-to-earnings ratio of 11 times. It could drop further when Hong Kong reopens on Thursday after Prosus NV — which tracks Tencent closely — fell almost 8% in European trading. Tencent’s latest results showed a big cash outflow as it doubled down on AI investments, while missing expectations on revenues. Top Tech Stories Earnings Due Wednesday