苹果是全球最有价值的公司之一。在市值排名靠前的几家公司中,它也是唯一一家未来并不完全取决于人工智能热潮的公司。
Apple is one of the most valuable companies in the world. It is also the only one among the top several whose future doesn’t hinge entirely on the AI boom.
这种避风港地位在科技同行股价遭受重创之际,帮助了这家智能手机巨头的股价。截至周一收盘,苹果股价在过去一个月上涨了1.4%。谷歌母公司Alphabet、Meta Platforms和英伟达在同一时期均下跌了两位数百分比。
That safe-haven status has helped the smartphone giant’s stock at a time when tech peers are getting battered. Apple’s shares are up 1.4% in the past month as of Monday’s close. Google parent Alphabet, Meta Platforms and Nvidia are all down by double digits over that period.
不过,投资者面临的问题是,苹果的安全溢价是否值得。截至周一收盘,苹果股票的市盈率(按预期盈利计算)约为35倍,接近18年来的高点。这使得苹果股票称不上便宜。在原本动荡的市场中,至少有几个令人信服的理由支持看好苹果。
The question for investors, though, is whether Apple’s safety premium is worth it. Apple’s shares were trading at about 35 times forward earnings as of Monday’s close, near an 18-year high. That makes Apple anything but a bargain. There are at least a few compelling reasons to favor Apple in an otherwise choppy market.
首要原因是,在智能手机市场低迷之际,该公司的智能手机业务表现出了令人惊讶的韧性。根据国际数据公司(IDC)的数据,第三季度全球智能手机出货量同比下降22%,但iPhone出货量仅下降4%。
Chief among them is that the company’s smartphone business has been surprisingly resilient during an anemic period for the market. The number of smartphones sold globally fell 22% from a year earlier in the third quarter, according to International Data Corp., but iPhone unit sales fell only 4%.
而且,至少到目前为止,苹果擅长在设备销量减少时仍能挤出利润。该公司今夏将智能手机和Mac电脑的价格最高上调了33%。公司周一表示,最新季度产品营收增长12.5%,达到829亿美元,高于分析师预期。
And Apple has been adept, at least so far, at squeezing out profits even when it is selling fewer devices. The company raised prices for its smartphones and Mac computers this summer by as much as 33%. Product revenue in its latest quarter rose 12.5% to reach $82.9 billion, the company said Monday, higher than analysts were expecting.
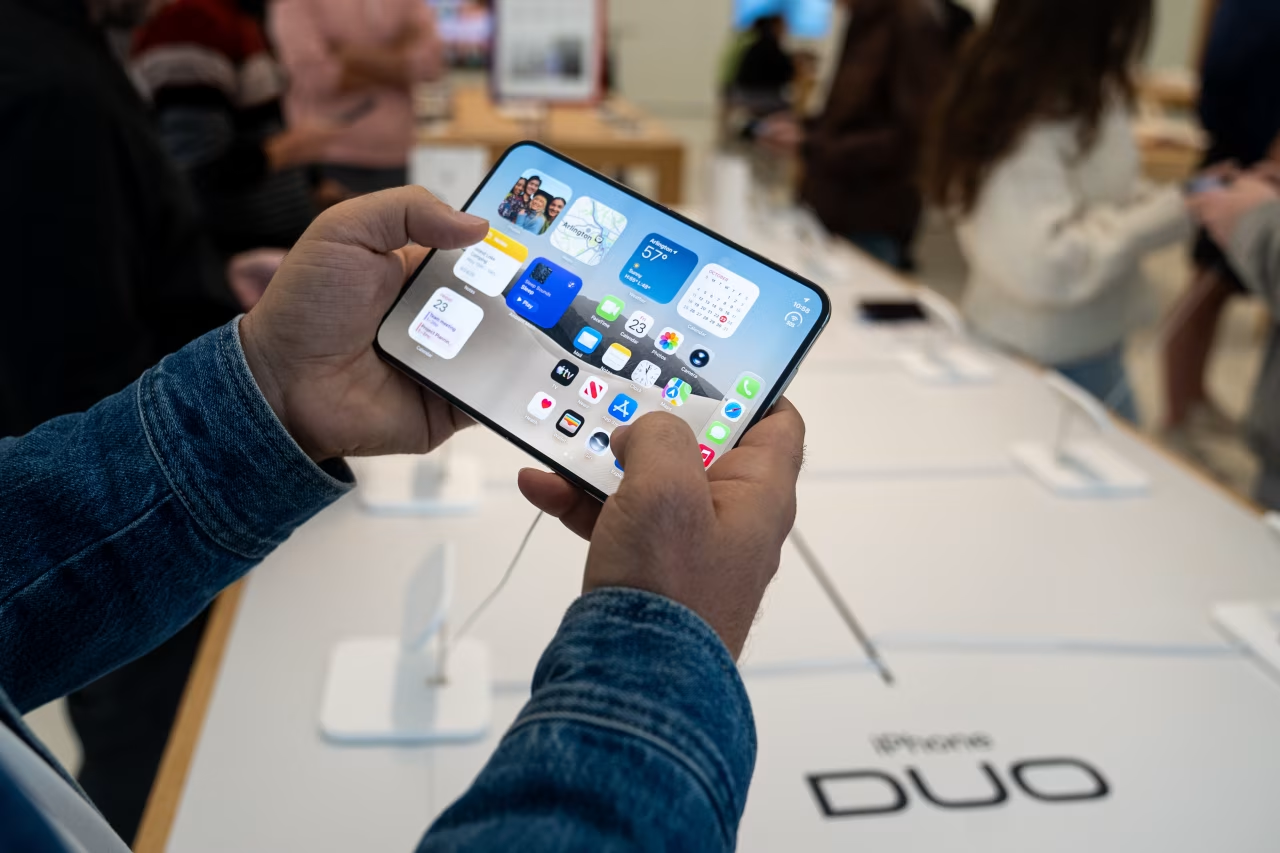
这些产品的未来前景也看起来稳固。苹果上个月开始销售其可折叠的Duo手机,同时推出了iPhone 18的新款Pro和Pro Max版本。根据高盛近期的一份研报,近期供应链指标显示对这些产品的需求“令人鼓舞”,这支持了向高价手机转型的趋势。
The future for those products looks solid, too. Apple started selling its foldable Duo phone last month, alongside new Pro and Pro Max versions of its iPhone 18. Recent supply-chain indicators suggest “encouraging” demand for them, according to a recent Goldman Sachs note, which supports the shift toward higher-priced phones.
与此同时,同行企业在人工智能领域大举投入,却收效有限,投资者对此已不再一致看好。苹果拥有雄厚的财务垫,资产负债表上有567亿美元的现金和有价证券,且没有即将到期的大额人工智能账单。
Meanwhile, the company’s peers have been maxing out spending on AI with limited returns to show for it, a state of affairs investors are no longer uniformly happy about. Apple has a substantial financial cushion, with $56.7 billion of cash and marketable securities on its balance sheet, and no big AI bills coming due.
事实上,该公司在刚刚结束的财年资本支出仅为90亿美元——与五大超大规模云服务商今年预计合计投入的近8000亿美元相比,简直是九牛一毛。在9月季度,苹果获得了超过300亿美元的自由现金流,而大多数大型科技公司当时的现金流出多于流入。
The company, in fact, had just $9 billion of capital expenditures in its recently ended fiscal year—small potatoes compared with the nearly $800 billion the five large hyperscalers are projected to shell out collectively this year. It raked in more than $30 billion of free cash flow in its September quarter, when most of Big Tech was sending more cash out the door than it was bringing in.
苹果显然表现优异。但也有理由怀疑,投资者是否因其种种优势而过度奖励了它。
Apple is clearly doing well. But there are also reasons to wonder whether investors are rewarding it too much for all its advantages.
令人担忧的一个原因是,苹果的涨价策略在长期内是否可持续尚不清楚。该公司今年可能大幅提价,但仍有待观察它能否在不疏远客户的情况下继续这样做。
One reason for pause is that it isn’t clear Apple’s price-increase strategy is sustainable in the longer term. The company may have raised prices a bunch this year, but it remains to be seen whether it can keep doing so without alienating customers.
如果客户认为价格高不可攀,许多人可能会更长时间地保留旧手机。虽然移动运营商目前通过慷慨的以旧换新和融资方案帮助客户购买新iPhone,从而弥补了这一差距,但这种情况可能会改变。据设备保险公司Assurant称,第二季度以旧换新iPhone的平均机龄已首次超过四年,高于第一季度的3.7年。
Many customers might hang on to older phones longer if they see prices as out of reach. While mobile carriers are helping bridge that gap now, with generous trade-in and financing offers to help customers get new iPhones, that could change. The average age of traded-in iPhones already surpassed four years for the first time in the second quarter, according to device-insurance player Assurant, up from 3.7 years in the first quarter.
与此同时,因零部件成本上涨而对苹果利润率造成的压力短期内不太可能缓解,高管们周一在与分析师的电话会议上也暗示了这一点。苹果在内存方面遇到了特别麻烦,由于人工智能计算需求旺盛,内存成本正飙升。
Pressure on Apple’s margins from rising component costs, meanwhile, isn’t likely to ease any time soon, a factor executives nodded to on a call with analysts Monday. Apple has had particular trouble with memory, the cost of which is skyrocketing because it is in high demand for AI computing.
这尚未对苹果的利润率造成太大影响——至少目前如此。该公司周一表示,其整体毛利率为健康的47.9%,部分原因是近期的关税退税抵消了更高的成本。但首席财务官Kevan Parekh预计,本季度毛利率将收窄至45%至46%之间。这导致该公司股价在盘后交易中下跌。
That hasn’t put much of a dent in Apple’s profit margins—yet. The company on Monday said its overall gross margin was a healthy 47.9%, in part because recent tariff refunds have offset higher costs. But Chief Financial Officer Kevan Parekh projected a narrowing to between 45% and 46% in the current quarter. That prompted a decline in the company’s shares in after-hours trading.
苹果面前还有其他几个问题。首先,它长期以来一直享受着应用内交易的高额费用,但美国、欧盟及其他地区的监管和法律变化意味着应用开发者可以通过其他渠道进行更多交易。这限制了App Store收入及其整体高利润服务业务的增长。
Apple has a few other problems on its horizon, too. It has long enjoyed hefty fees on transactions inside apps, for one, but regulatory and legal changes in the U.S., European Union and elsewhere mean app developers can do more transactions through other channels. That is limiting the growth of App Store revenue and its high-margin services business overall.
苹果新任首席执行官John Ternus是另一个不确定因素。他在周一首次主持财报电话会议时,并未提供太多独特的愿景。但他如何在公司留下自己的印记,可能会严重影响苹果在多大程度上能免受人工智能支出热潮的冲击。
Apple’s new chief executive, John Ternus, presents another wild card. He didn’t offer much of a distinct vision on Monday in his first earnings call at the helm. But how he puts his stamp on the company could heavily influence how insulated Apple remains from the AI spending boom.
对于想要长线投资科技股但又不想过度暴露于人工智能领域的投资者来说,苹果并非一个糟糕的选择。不过,按公司目前的估值来看,它是一个相当昂贵的选择。
Apple isn’t a bad option for investors who want to go long on tech without being overexposed to AI. At the company’s current valuation, though, it is quite an expensive one.