MSCI公司高管于周二下午雅加达时间参加了一次电话会议,与会的100多名投资者大多仍因该指数提供商突然警告可能对印度尼西亚实施“双重降级”而感到震惊。他们质疑采取如此激烈措施的必要性,并想了解该国是否还有机会保住新兴市场地位。
MSCI Inc. officials joined a call on Tuesday afternoon Jakarta time, many of the more than 100 participants were investors still reeling from the index provider’s sudden warning of a potential double downgrade for Indonesia. They questioned the need for such a drastic step and wanted to know whether the country stood a chance of retaining its emerging-market status.
据知情人士透露,MSCI董事总经理Raman Aylur Subramanian在由瑞银集团主办的电话会议上表示,印度尼西亚的问题不是指数问题,而是市场问题。他补充说,需要进行改革以清除“害群之马”。知情人士因讨论私密信息而要求不具名。
Indonesia’s case is not an index issue but a market issue, MSCI Managing Director Raman Aylur Subramanian said on the call hosted by UBS Group AG, according to people familiar with the matter, who asked not to be identified discussing private information. There’s a need for reforms to weed out the “bad actors,” he added, the people said.
Subramanian的言论清楚地表明:随着印度尼西亚争分夺秒以避免地位遭受双重打击,成败将取决于能否说服MSCI和全球投资者,相信其能够有效监管股市。
Subramanian’s comments made one thing clear: as Indonesia races against time to avert the double blow to its status, success will rest on convincing MSCI and global investors that it can effectively regulate its stock market.
MSCI上周的警告明确指出,仅靠新规不足以扭转局势。距离其2027年6月的决定还有八个多月,当局面临的挑战是建立一份令人信服的执法记录——揭露不透明的股权结构,调查可疑交易,并实施严厉处罚,包括惩处与该国一些最有实力的企业集团有关联的公司。
MSCI’s warning last week was explicit in that new rules alone won’t be enough to turn the tide. With a little over eight months until its June 2027 decision, the challenge for authorities is to build a convincing record of enforcement — uncovering opaque ownership, investigating suspicious trading and imposing strict penalties, including on companies linked to some of the country’s most powerful business groups.
任务艰巨,印度尼西亚在全球市场中的排名岌岌可危。若被降为独立市场地位,将使其甚至跻身不上该指数提供商的前沿市场范畴,可能引发数十亿美元的资金外流。而全球投资者今年已净抛售了53亿美元当地股票,有望创下有纪录以来最大规模外流。
The task is formidable, with Indonesia’s rank in global markets on the line. A move to standalone-market status would push it outside even the index provider’s frontier-market universe, potentially triggering billions of dollars in outflows. That’s when global investors have already sold a net $5.3 billion of local shares this year, set for the biggest outflow on record.
“问题不在于规则,印尼已经收紧了规则,而在于持续存在的涉嫌操纵和执法不力,”期权交易对冲基金Carthage Capital的管理合伙人Stephen Wu表示。“及时解决问题是可能的,但很难,因为他们无法仅靠立法解决,必须展现真正的行为改变。”
“The problem isn’t the rules, which Indonesia has already tightened, but continued suspected manipulation and weak enforcement,” said Stephen Wu, managing partner of Carthage Capital, an options-trading hedge fund. “Fixing it in time is possible but tough, because they can’t legislate their way out and have to show real behavioral change.”
Wu补充道,这将意味着“追究政治关联财团的责任,并持续几个季度”。他表示,降级的可能性较大,要么降为前沿市场地位,要么推迟决定,如果执法迅速严肃起来,这两者是现实的中间地带。MSCI的警告反映了全球基金更深层的疑虑,即雅加达市场的股价和成交量是否反映了真实的投资者活动。不透明的所有权结构、高度集中的持股和涉嫌协同交易,给正常的价格形成机制和报告的自由流通股——即被视为可供公众交易的公司股份比例——蒙上了阴影。
That, Wu added, will mean “going after politically connected conglomerates and sustaining it for a few quarters.”He said the odds favor a downgrade, with either a frontier status or a delay the realistic middle ground “if enforcement gets serious fast.”MSCI’s warnings reflect deeper doubts among global funds about whether share prices and trading volumes in Jakarta’s market reflect genuine investor activity. Obscure ownership structures, concentrated holdings and suspected coordinated trading have cast a shadow over both proper price formation and reported free float — the portion of a company’s shares considered available for public trading.
考虑到许多印尼上市公司隶属于庞大的家族控制财团,业务跨越采矿、烟草到石化等行业,这些担忧显得尤为相关。控制权可通过亲属和关联实体延伸,导致公众手中的股份相对较少。
Those concerns are particularly relevant given that many listed Indonesian firms sit within sprawling family-controlled conglomerates spanning industries from mining and tobacco to petrochemicals. Control can extend through relatives and affiliated entities, leaving relatively fewer shares in public hands.
“修复股票市场需要迫使公司所有者上市更多股份,”Tellimer新兴市场股票与地缘政治策略主管Hasnain Malik表示。“问题在于,其中一些所有者可能不需要资金,或者因为股票缺乏流动性交易,而坐拥虚高的股价。”知情人士透露,Subramanian在UBS电话会上为MSCI的做法进行了辩护,称该公司的评估基于从市场参与者收集的反馈,且MSCI在得出结论时采用客观框架。
“Fixing the equity market requires forcing company owners to list more of their shares,” said Hasnain Malik, head of emerging market equity and geopolitics strategy at Tellimer. “The problem is some of those owners may not need the capital or are sitting on inflated share prices because they are not liquidly traded.”Subramanian defended MSCI’s approach during the UBS call, saying that the firm’s assessment was based on feedback gathered from market participants and that MSCI applies an objective framework in reaching its conclusions, the people familiar said.
据知情人士透露,该指数编制公司近期在纽约和雅加达与印尼官员举行的私下会议中一直在暗示,市场的问题尚未得到解决。这些知情人士因讨论私密信息而要求不具名。
The index provider had been privately signaling to Indonesian officials in recent meetings in New York and Jakarta that the market’s problems have not been fixed, according to other people familiar with the matter, who asked not to be identified discussing private information.
据知情人士称,在8月31日的一次此类会议上,一位MSCI高管传达了印尼需要建立一种超越财务处罚的、针对市场操纵的“核威慑”机制,并援引香港和美国作为执法制度严格的例子。该高管还强调,印尼缺乏识别异常交易模式和防范市场滥用所需的技术和监控系统。
In one such meeting on Aug. 31, a top MSCI executive conveyed how Indonesia needed to set up a “nuclear deterrent” against market manipulation that goes beyond financial penalties, referring to Hong Kong and the US as examples of where there are stringent enforcement regimes, according to people familiar with the discussion. The executive also highlighted how Indonesia lacked the technology and surveillance systems needed to identify irregular trading patterns and prevent market abuse.
另一位知情人士称,在9月23日的另一次会议上,MSCI首席执行官亨利·费尔南德斯对股市状况表达出的警觉感让印尼官员感到意外。他们请求对方提供可转达给总统普拉博沃·苏比安托的建议,费尔南德斯同意通过电子邮件发送,该人士说。
In another meeting on Sept. 23, Indonesian officials were taken aback by MSCI Chief Executive Henry Fernandez’s sense of alarm over the state of the stock market, another person familiar with the matter said. They asked for recommendations that they could relay to President Prabowo Subianto, which Fernandez agreed to email over, the person said.
“MSCI将继续监测印尼市场的发展,并与市场参与者和当局保持接触,”该指数编制公司在通过电子邮件发回的答复中写道。它补充称,MSCI不披露其会议日程的细节。
“MSCI will continue to monitor developments in the Indonesian market and engage with market participants and authorities,” the index provider wrote in an emailed response to questions. It added that MSCI doesn’t disclose details of its meeting schedule.
“我们定期与市场参与者会面,讨论他们的市场体验,并与监管机构、政府机关和官员会面,以了解他们的观点和视角。目前的咨询反映了这一接触政策,”MSCI在其声明中表示。瑞银集团的一位代表拒绝置评。
“We regularly meet market participants to discuss their market experience, and with regulators and government agencies and officials to understand their views and perspective. The current consultation reflects this policy of engagement,” MSCI said in its statement. A representative for UBS declined to comment.
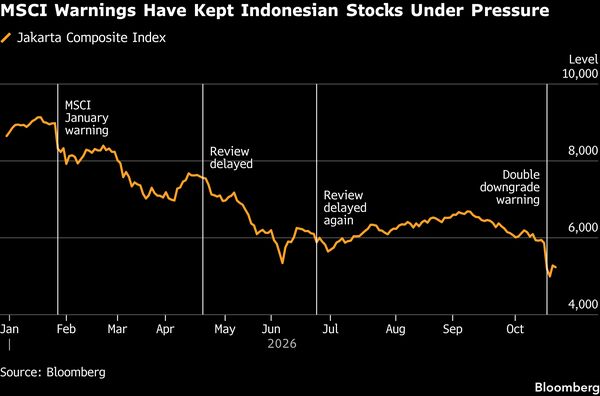
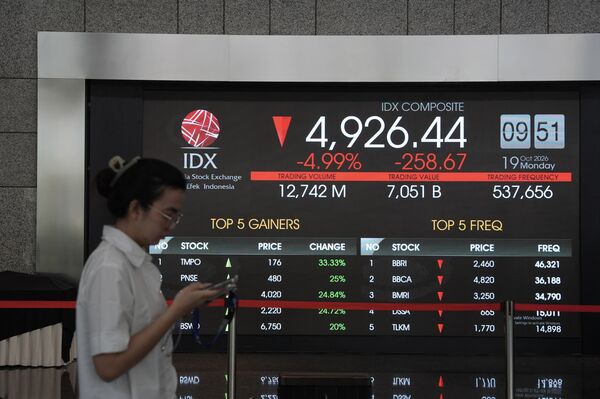
印尼当局已采取行动改善所有权披露并识别高度集中持股的股票,此举源于 MSCI(明晟)1 月发出首次警告后,当地股市陷入暴跌。该机构扬言将实施“双重降级”,引发基准雅加达综合指数(JCI)在周五遭遇近三十年来最严重抛售,加大了监管层采取行动的压力,并促使其出台更多纠正措施。
Indonesian authorities have moved to improve ownership disclosure and identify highly concentrated stocks since MSCI’s first warning in January sent local equities into a tailspin. The firm’s threat of a double downgrade sparked the benchmark Jakarta Composite Index’s worst selloff in nearly three decades on Friday, intensifying pressure on regulators to act and prompting more corrective measures.
“尽管已宣布改革,但围绕市场机能失调的重大担忧依然存在,包括持续存在的疑似协同交易行为,以及缺乏有意义执法行动的证据,” MSCI 在 10 月 15 日的声明中表示。该机构未说明需要多少案例、处罚或多少个月的更清洁交易记录,才足以通过其审查。
“Despite the announced reforms, significant concerns remain around market dysfunction, including continued suspected coordinated trading behavior and lack of evidence of meaningful enforcement,” MSCI said in an Oct. 15 statement. It didn’t say how many cases, penalties or months of cleaner trading would be enough before its review.
在周一与 MSCI 代表会晤后,印尼证券交易所表示,将把高度集中持股的公司从基准指数成分股计算中剔除。名单包含约 80 家公司。
Following a meeting with MSCI representatives on Monday, the Indonesia Stock Exchange said it will remove companies with highly concentrated ownership from the calculation of the benchmark index. The list includes about 80 companies.
即便如此,将这些股票从基准指数中移除,可能很难解决令 MSCI 担忧的深层行为问题。这些股票仍将继续交易,而围绕其所有权、真实自由流通股及交易模式的疑问依然存在 —— 这凸显了清理指数与证明更广泛的市场本身运行良好之间的差距。
Even so, getting rid of those stocks from the benchmark may do little to address the underlying conduct that has troubled MSCI. Their shares will continue to trade, while questions over their ownership, true free float and trading patterns remain — underscoring the gap between cleaning up an index and demonstrating that the broader market itself is functioning properly.
据知情人士透露,苏布拉马尼安在周二的电话会议上表示,该名单不充分,且筛选标准不明确,与会者多为代表被动及主动基金的外资投资者。
The list was insufficient and the selection criteria was unclear, Subramanian said on Tuesday’s call, which included mostly foreign investors representing passive and active funds, according to the people familiar.
印尼现在有至 4 月底的时间 —— MSCI 关于“双重降级”的咨询期结束之时 —— 来证明其采取的任何变革确实带来了持续改善。与此同时,今年以来 JCI 已下跌逾 38%,在彭博追踪的 90 多个全球指数中,仍是今年表现最差的指数。
Indonesia now has until the end of April, when MSCI’s consultation on the double downgrade closes, to demonstrate any changes it makes are indeed producing sustained improvements. Meantime, down more than 38% so far in 2026, the JCI remains this year’s worst performer among more than 90 global indexes tracked by Bloomberg.
“印尼应抓住这一机遇,将信息披露和执法推向更接近全球规范的水平,”总部位于伦敦的Edgbaston Investment Partners首席投资官Charu Fernando表示,该公司管理的亚太股票投资策略资产规模达8.58亿美元,印尼是其第三大国家配置市场。“目前存在推动这一进程的势头和政治意愿,这次机会不应被浪费。”
“Indonesia should take this opportunity to move disclosure and enforcement closer to global norms,” said Charu Fernando, London-based chief investment officer at Edgbaston Investment Partners, which oversees $858 million across its Asia-Pacific equity investment strategy and counts Indonesia as its third-largest country exposure. “There is currently momentum and political will to do this, and this time should not be wasted.”