加拿大央行周三上调基准利率,以遏制通胀。但对该国房地产市场而言,这一举措是沉重打击。
The Bank of Canada raised its benchmark interest rate Wednesday in an effort to fight inflation. But for the nation’s housing market, the move is a heavy blow.
与美国不同,加拿大人倾向于每五年或更短时间续签一次抵押贷款。浮动利率借贷也很普遍。这意味着,当央行调整利率时,住房是受影响最早的经济板块之一。而随着加拿大房地产市场自2022年以来降温,央行的政策举措削弱了近期复苏的希望。
Unlike in the US, Canadians tend to renew their mortgages every five years or less. Variable-rate borrowing is also common. That means housing is one of the first parts of the economy affected when the central bank moves interest rates. And with Canada’s housing market cooling since 2022, the central bank’s policy move blunts hope for an imminent recovery.
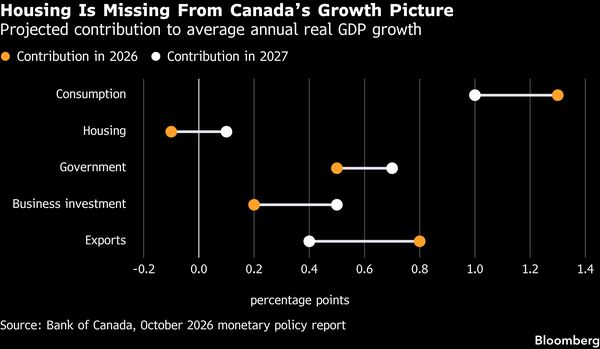
加拿大央行的经济预测现在显示,住宅房地产对经济增长几乎不做贡献,直至2028年。
The Bank of Canada’s economic projections now show residential real estate making virtually no contribution to economic growth through 2028.
“我们对房地产的前景看法相当低迷,”高级副行长卡罗琳·罗杰斯周三对记者表示。“当然,目前的借贷利率正在一定程度上拖累房地产市场。加息将加剧这种影响。” 2022年开始的低迷期之前,经历了长达四分之一世纪的价格稳步上涨,成为全球规模最大、持续时间最长的房地产繁荣之一。
“Our outlook on housing is pretty subdued,” Senior Deputy Governor Carolyn Rogers told reporters Wednesday. “Certainly borrowing rates are currently weighing a bit on the housing market. An increase will add to that.”The downturn that began in 2022 was preceded by a quarter-century in which prices rose steadily, becoming one of the biggest, longest housing booms in the world.
但那轮繁荣的最后阶段,是由借贷者涌入浮动利率抵押贷款所推动的。这些人将是最早感受到本周加息影响的人群。
But the last stage of that boom was driven by a surge of borrowers into variable-rate mortgages. Those people will be among the first to feel this week’s rate rise.
紧随其后的将是那些在低利率时代借贷、并首次面临续签抵押贷款的房主。根据德嘉登分析师罗伊斯·门德斯和蒂亚戈·菲格雷多的研究,未来几个月续签浮动利率贷款的人可能面临约50%的还款冲击。
Soon to follow will be homeowners who borrowed in an era of low rates and are renewing their mortgages for the first time. People with variable rates renewing in the coming months may receive a payment shock of roughly 50%, according to research from Desjardins analysts Royce Mendes and Tiago Figueiredo.
尽管加拿大拖欠抵押贷款的比例仍低于历史水平,但此类冲击可能会推高这一比率,分析师在10月27日的研究报告中写道:“抵押贷款续约正进入一个充满风险的时期。”如果住房活动按照加拿大央行的预测在2028年前演变,该国将陷入长达六年的低迷。这将与1990年代那段臭名昭著的时期相媲美,当时全国房价在十年初开始暴跌后,花费了九年多时间才恢复到之前的高点。
Though Canada’s portion of mortgages in arrears remains below historic levels, such shocks may nudge the rate higher, the analysts wrote in their Oct. 27 research note: “Mortgage renewals are entering a risky period.”If housing activity plays out in line with the Bank of Canada’s projections through 2028, the country would be six years into a slump. That would rival the infamous 1990s, when national home prices took more than nine years to regain their previous high after a crash that began at the beginning of the decade.
加拿大1990年代的经济形势与现在存在相似之处。在两种情况下,央行都被迫在经济疲软的情况下加息。但35年前,加拿大的高额公共债务是一个重要因素。如今,困扰经济的最大问题——由油价上涨推动的通胀以及与美国的贸易战——在很大程度上都超出了该国的控制范围。
There are similarities between Canada’s economic landscape in the 1990s and now. In both cases, the central bank was forced to raise interest rates despite a weak economy. But 35 years ago, Canada’s high public debt was a significant factor. Today, the biggest problems bedeviling the economy — inflation driven by higher oil prices and the trade war with the US — are both largely outside the country’s control.
央行的罗杰斯周三表示:“目前有许多因素正在拖累住房市场。”他说,“在整体经济不确定性的背景下,人们倾向于不做出购房等重大购买决定。”
“There’s a number of things weighing on housing right now,” the central bank’s Rogers said Wednesday. With “the overall uncertainty in the economy, people don’t tend to make big purchase decisions like housing in that kind of an environment.”