资产管理公司的鲍勃·米歇尔给财政部长斯科特·贝森特提了个建议:取消20年期债券。
Asset Management’s Bob Michele has some advice for Treasury Secretary Scott Bessent: get rid of the 20-year bond.
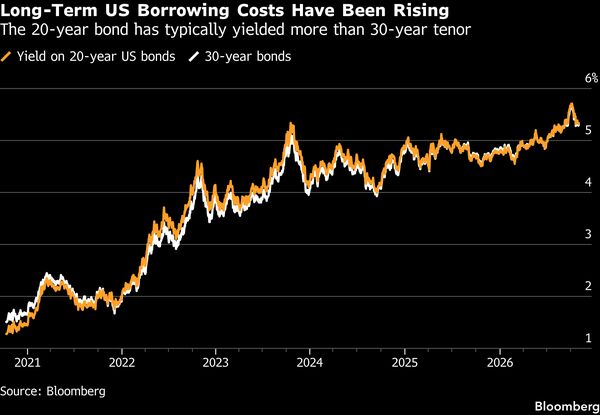
“谁都不喜欢它,”该公司全球固定收益主管米歇尔在财政部周三公布季度债务发行计划前表示,“为什么要发行它?在另一个时代这说得通。现在说不通了。” 长期收益率飙升至2002年以来最高,引发市场猜测财政部将在未来几个月将发行重心转向短期国库券和中期票据。尽管如此,彻底取消20年期债券仍属尾部风险,彭博社调查的交易商中无人将其作为基准情景预测。
“Nobody likes it,” Michele, the firm’s global head of fixed income, said ahead of the Treasury’s announcement of its quarterly debt sales on Wednesday. “Why do you issue it? It made sense in another era. It doesn’t make sense now.”The surge in long-dated yields to the highest since 2002 has fanned speculation the Treasury will pivot sales toward shorter-dated bills and notes in the coming months. Still, scrapping the 20-year bond outright remains a tail risk, with no dealer surveyed by Bloomberg forecasting such a move as their base case.
米歇尔在彭博电视节目《监视》上表示,财政部可将发行重心从20年期板块转向短期国库券——期限最长一年——从而支撑收益率曲线的长端。
Michele, who was speaking on Bloomberg Surveillance, said the Treasury could rebalance sales away from the 20-year sector toward short-term bills, which mature in up to one year, supporting the long end of the curve.
自2020年重新推出以来,20年期债券表现长期落后于其他长期品种,导致市场不时呼吁财政部取消该品种,甚至在今年收益率飙升之前就已如此。
The 20-year maturity has struggled relative to its long-dated peers since it was reintroduced in 2020, leading to intermittent calls for the Treasury to scrap it even before this year’s run-up in yields.
意外取消该期限债券将打破财政部在债务管理政策上长期坚持的“定期且可预期”沟通惯例。在8月的上一次再融资声明中,财政部称预计“至少未来几个季度”拍卖规模不变。此后,贝森特以增加长期国债回购计划令交易员意外。虽然该改革未能带来持久的收益率缓解,但重燃了关于20年期国债优劣的辩论。法国巴黎银行策略师上月指出,此举可能产生“意外后果”,包括收益率上升或流动性下降。对米歇尔而言,财政部在别处有深得多的流动性池可供利用。
An unexpected move to drop the maturity would represent a break from the Treasury’s longstanding approach to “regular and predictable” communications when it comes to its debt-management policies. At its previous refunding statement in August, the Treasury said it envisaged no changes to auction sizes for “at least the next several quarters.”Since then, Bessent surprised traders with plans to boost buybacks of long-maturity Treasuries. While the revamp failed to bring lasting yield relief, it helped revive the debate around the merits of the 20-year Treasury. Strategists at BNP Paribas SA argued last month that such a move could have “unintended consequences,” including higher yields or lower liquidity. For Michele, there are much deeper pools of liquidity elsewhere for the Treasury to tap.
“只需说:‘这事完了,这是个无人问津的问题,我们打算直接把它扔进前端,那里有8万亿美元的货币市场基金资产,’”他说。“我们可以在那里轻松为自己融资。”
“Just say: ‘it’s done for, it was an orphan issue, we’re going to just dump it into the front end where there’s $8 trillion in money-market fund assets,’” he said. “We can finance ourselves there with ease.”