欧洲股市正在走强,投资者开始重新审视华尔街对人工智能的高度依赖。
European equities are gaining ground as investors reconsider Wall Street’s heavy reliance on AI.
较低的估值和更广泛的行业分布,使欧洲具备了极具吸引力的分散投资价值。
Lower valuations and broader sector exposure give Europe a compelling diversification case.
但要将这一优势转化为持久增长,取决于那些在很大程度上仍未完成的改革。
But turning that advantage into lasting growth will depend on reforms that remain largely unfinished.
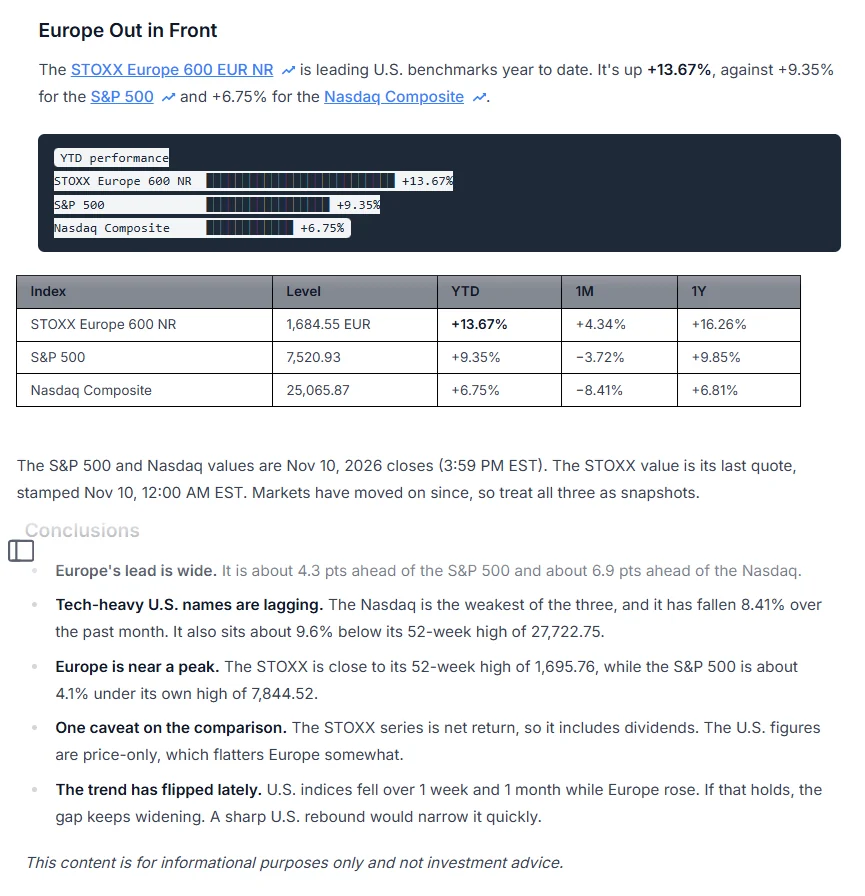
欧洲已悄然成为2026年表现最强劲的主要股票市场之一。截至11月11日收盘,标普500指数年内上涨11.3%,纳斯达克指数上涨约9.6%,而欧洲斯托克600指数涨幅接近12%,刚刚创下收盘历史新高。这种反差在11月5日美国股市大幅抛售后变得尤为明显,当时纳斯达克指数、标普500指数以及英伟达、超威半导体和美光科技等主要芯片股承受重压,而欧洲市场几乎未动。
Europe has quietly become one of the stronger major equity markets of 2026. As of the November 11 close, the S&P 500 was up 11.3% year to date and the Nasdaq had gained about 9.6%, while the STOXX Europe 600 was ahead by almost 12%, having just notched a record close. The contrast became especially visible after a sharp sell-off in U.S. equities on November 5 left the Nasdaq, S&P 500 and major semiconductor names such as Nvidia, AMD and Micron under heavy pressure, while European markets barely moved.
单一交易日的表现无法确立长期趋势,但这种分化提出了一个更重要的问题:当美国市场日益集中于少数押注巨资发展人工智能的科技公司时,欧洲能否为投资者提供一个更稳定的替代选择?答案不仅仅是欧洲股票更便宜。更有力的论据在于,欧洲兼具较低估值、对AI的依赖程度较低,以及大量因市场碎片化和资本形成薄弱而被锁住的经济潜力。
One difficult session does not establish a long-term trend, but the divergence raises a more important question: whether Europe can offer investors a more stable alternative at a time when the U.S. market is increasingly concentrated in a small group of technology companies making enormous bets on artificial intelligence. The answer is not simply that European stocks are cheaper. The stronger argument is that Europe combines lower valuations, less dependence on AI, and a large amount of economic potential that remains locked behind fragmented markets and weak capital formation.
因此,这一机遇包含两个层面。第一是防御性的:欧洲面临的集中度风险远低于主导美国市场的那种风险。第二是结构性的:如果欧洲能够减少内部壁垒、调动居民储蓄并建设更深层的资本市场,该地区就能创造一个强得多的国内投资周期。问题在于执行。这些潜力已存在多年,德拉吉议程中确定的改革迄今仅有很小一部分得以落实。
The opportunity therefore has two layers. The first is defensive: Europe is less exposed to the same concentration risk that dominates the U.S. market. The second is structural: if Europe can reduce internal barriers, mobilize household savings and build deeper capital markets, the region could create a much stronger domestic investment cycle. The problem is execution. Much of that potential has existed for years, and only a small share of the reforms identified in the Draghi agenda has been implemented so far.
来源:WarrenAI 对于希望深入研究同类公司数据、估值指标和 AI 分析的投资者,InvestingPro 目前提供高达 55% 的折扣。
Source: WarrenAI For investors who want to dig into the same kind of company data, valuation metrics and AI analysis, InvestingPro is currently available at up to a 55% discount.
如果您想利用该优惠,请使用下方链接在早鸟黑五优惠结束前领取:华尔街的强势伴随着高度的 AI 集中度 美国市场依然极其强劲,但这种强势在很大程度上集中在少数几家公司身上。苹果、英伟达、微软、Alphabet、亚马逊、Meta 和特斯拉合计占标普 500 指数的比重约为 34%。这意味着,极少数公司现在对整个指数的走向拥有异常巨大的影响力。
If you want to take advantage of the offer, use the link below to claim the Early-Bird Black Friday offer before it’s gone: Wall Street’s Strength Comes With Heavy AI Concentration The U.S. market remains enormously powerful, but much of that strength is concentrated in a handful of companies. Apple, Nvidia, Microsoft, Alphabet, Amazon, Meta and Tesla together account for roughly 34% of the S&P 500. That means a relatively small number of companies now have an unusually large influence on the direction of the entire index.
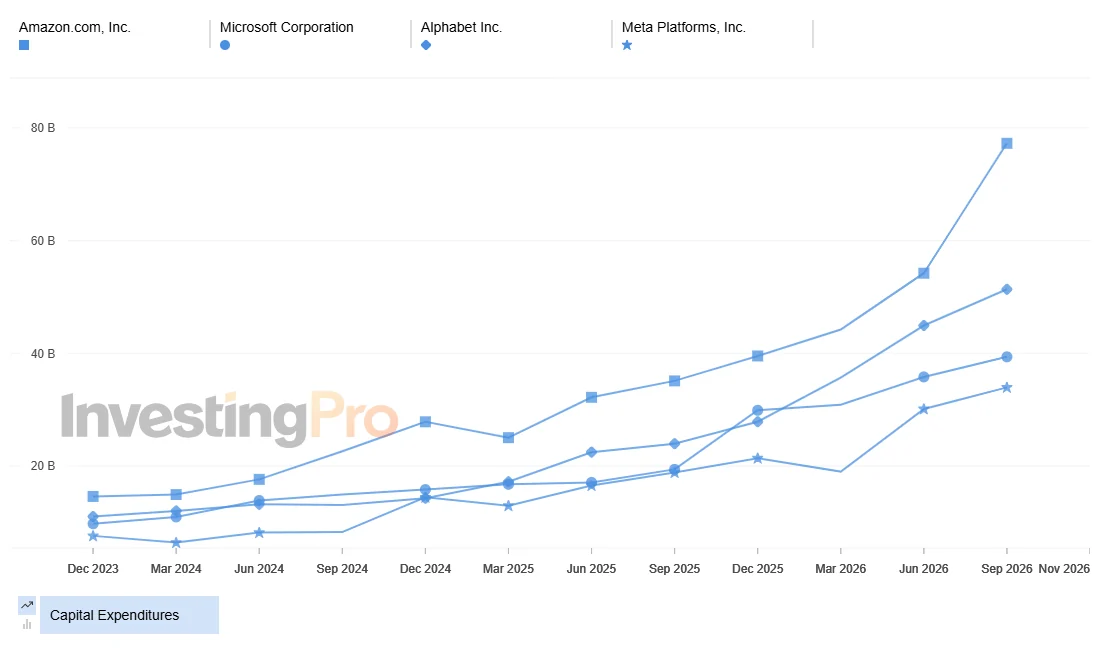
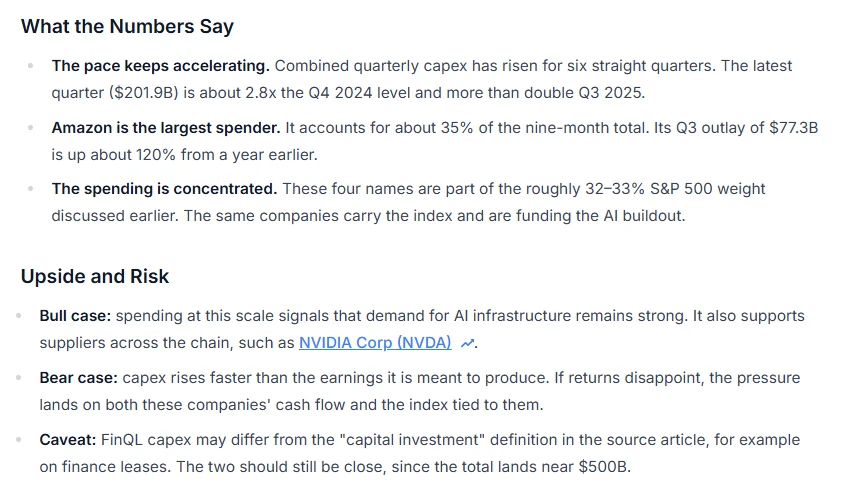
这种集中度变得更加重要,因为几乎所有这些公司都在积极投资人工智能。仅在 2026 年前九个月,亚马逊、微软、Alphabet 和 Meta 的资本支出就接近 5000 亿美元。其中大部分资金被投向 AI 芯片、数据中心以及支持这些基础设施所需的设施。
The concentration becomes more important because almost all of those companies are making aggressive investments in artificial intelligence. Amazon, Microsoft, Alphabet and Meta alone spent nearly $500 billion on capital investment during the first nine months of 2026. Much of that money is being directed toward AI chips, data centers and the infrastructure needed to support them.
这形成了一种不同寻常的局面。华尔街不再仅仅是押注科技公司的增长;它越来越多地押注于极少数超大规模企业将巨额基础设施支出转化为未来利润的能力。如果这些投资奏效,上行空间可能非常可观。如果失败,损害将不局限于少数个股,因为这些公司在主要美国指数中占据如此大的比重。
That creates an unusual setup. Wall Street is not simply betting on the growth of technology companies; it is increasingly betting on the ability of a small number of hyperscalers to turn enormous infrastructure spending into future profits. If those investments work, the upside could be substantial. If they do not, the damage would not be confined to a few individual stocks because the companies involved represent such a large share of the major U.S. indices.
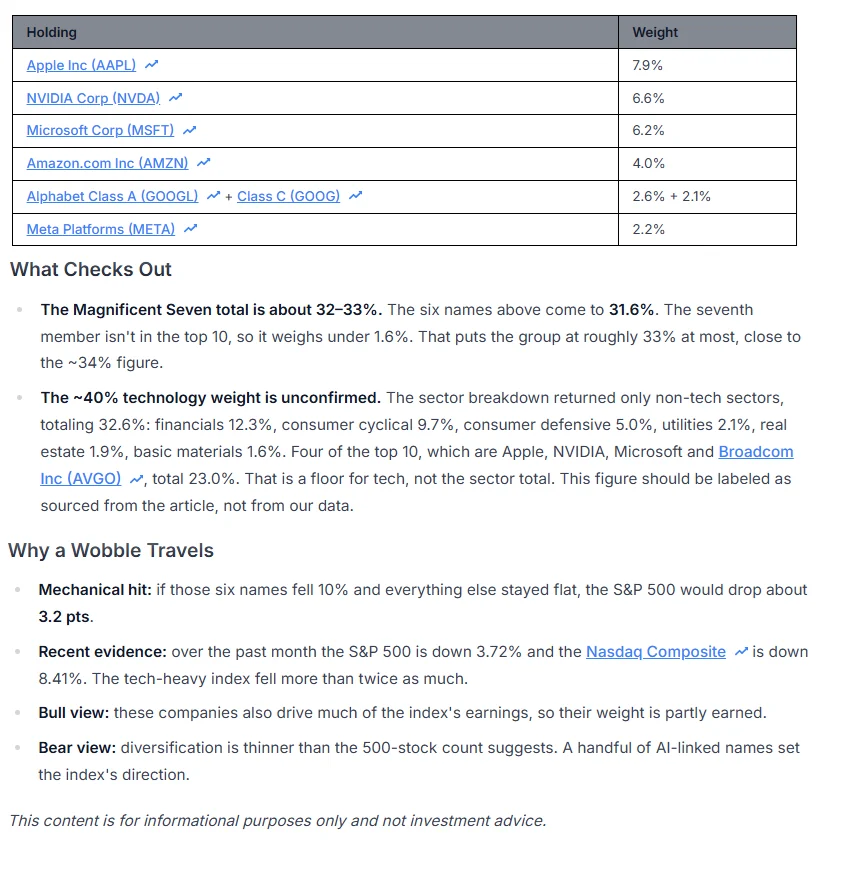
在板块层面,这种集中度更加明显。科技板块占标普 500 指数的比重近 40%,而 STOXX 欧洲 600 指数中同类板块的比重不足 10%。这种差异使得欧洲对当前 AI 投资热潮的成败依赖程度低得多。AI建设热潮也正成为政治议题AI投资周期并非在政治真空中进行。美国的增长战略日益将AI基础设施视为经济扩张、税收收入和未来国家收入的来源。
The concentration is even clearer at the sector level. Technology represents almost 40% of the S&P 500, while the comparable share in the STOXX Europe 600 is below 10%. That difference makes Europe much less dependent on the success of the current AI investment boom. The AI Buildout Is Also Becoming a Political Issue The AI investment cycle is not taking place in a political vacuum. The U.S. growth strategy increasingly treats AI infrastructure as a source of economic expansion, tax revenue and future national income.
这很重要,因为该国背负的国家债务超过40万亿美元,约占GDP的124%。华盛顿的论点是,在AI发挥重要作用的更强劲增长,可以帮助该国应对这一债务负担。
That matters because the country is carrying more than $40 trillion of national debt, equal to roughly 124% of GDP. The argument from Washington is that stronger growth, with AI playing an important role, can help the country manage that debt burden.
与此同时,对数据中心建设的抵制变得更加明显。盖洛普民调显示,71%的美国人反对在其所在社区建设AI数据中心。在11月的选举中,选民在41项地方投票提案中有38项支持限制或否决了数据中心建设。这给一个最大公司正大举投资此类基础设施的市场带来了额外风险。
At the same time, resistance to data-center development has become more visible. A Gallup poll shows that 71% of Americans oppose the construction of AI data centers in their own communities. In the November elections, voters favored restrictions or rejected data-center development in 38 of 41 local ballot measures. That creates an additional risk for a market whose largest companies are spending heavily on exactly this kind of infrastructure.
投资启示并非AI繁荣必然失败,而是前路变得更加复杂。超大规模企业建设数据中心需要海量电力、土地和基础设施,而地方抵制可能使这种扩张变得更慢或成本更高。如果AI回报同时令人失望,压力可能会被放大,因为美国市场已高度集中在进行这些投资的公司身上。
The investment implication is not that the AI boom must fail. It is that the path has become more complicated. Hyperscalers need enormous amounts of power, land and infrastructure to build out their data centers, while local resistance can make that expansion slower or more expensive. If AI returns disappoint at the same time, the pressure could be amplified because the U.S. market is already so concentrated in the companies making those investments.
债务问题增加了另一层考量。如果AI投资成为美国增长的主要引擎,那么低于预期的回报将影响的不仅仅是股票估值。它还将削弱用来支撑“美国可通过扩张化解巨额债务负担”这一信心的增长叙事之一。欧洲对AI交易的依赖程度低得多欧洲在技术领域的薄弱常被视为劣势,但在当前市场环境下,这也提供了分散化优势。由于科技板块在STOXX Europe 600指数中的权重不足10%,该指数对AI相关股票突然重新定价的敞口远低于标普500指数。
The debt issue adds another layer. If AI investment becomes a major engine of American growth, then a weaker-than-expected payoff would affect more than equity valuations. It would also weaken one of the growth narratives being used to justify confidence that the U.S. can expand its way through a very large debt burden. Europe Is Much Less Dependent on the AI Trade Europe’s weakness in technology has often been treated as a disadvantage, but in the current market it also provides diversification. With technology making up less than 10% of the STOXX Europe 600, the index is far less exposed to a sudden repricing of AI-related stocks than the S&P 500.
欧洲市场的构成更为宽泛。银行、工业企业、医疗保健和能源扮演着重要得多的角色,这降低了任何单一主题的影响力。即便是STOXX Europe 600指数中市值最大的10家公司,其权重合计也不到20%,而标普500指数中仅7家公司的权重合计就约为34%。
The composition of the European market is broader. Banks, industrial companies, healthcare and energy play a much larger role, which reduces the influence of any single theme. Even the 10 largest companies in the STOXX Europe 600 account for less than 20% of the index, compared with roughly 34% for just seven companies in the S&P 500.
这并不意味着欧洲股票能免疫全球性抛售。但这确实意味着,该地区对目前推动美股市场表现很大一部分的那一小撮AI相关公司的依赖程度较低。因此,如果AI股票遭遇大幅回调,欧洲承受的来自这一特定集中度风险的直接压力应当会更小。
That does not make European equities immune to a global sell-off. It does mean the region is less dependent on the same narrow group of AI-linked companies that currently drives a large part of U.S. market performance. If AI stocks suffer a major correction, Europe should therefore feel less direct pressure from that particular source of concentration.
这种差异也有助于解释,为何在美股科技股剧烈波动期间,欧洲市场显得更为稳定。市场的构建仅仅是围绕着不同的行业组合。投资者并没有像在美国那样,对超大规模数据中心运营商、半导体和AI基础设施进行同样高度集中的押注。欧洲股票也以巨大的估值折价交易分散化论点之所以更具吸引力,是因为欧洲股票也更便宜。投资者为美股支付的市盈率约为预期年利润的22倍,而欧洲股票则不足15倍。这代表了约30%的估值折价。
The difference also helps explain why Europe can appear more stable during periods of sharp volatility in American technology shares. The market is simply built around a different mix of industries. Investors are not making the same concentrated bet on hyperscalers, semiconductors and AI infrastructure. European Stocks Also Trade at a Large Valuation Discount The diversification argument becomes more interesting because European equities are also cheaper. Investors are paying roughly 22 times expected annual profits for American stocks, compared with less than 15 times for European stocks. That represents a valuation discount of around 30%.
更便宜并不自动意味着更好。较低的倍数可能反映增长较慢、业务较弱或理应享受折价的结构性问题。关键在于,欧洲起步于一个更低的估值基数,而与此同时,美股市场承担着大得多的AI交易敞口。
Cheaper does not automatically mean better. A lower multiple can reflect slower growth, weaker businesses or structural problems that deserve a discount. The point is that Europe begins from a lower valuation base at the same time that the U.S. market carries much greater exposure to the AI trade.
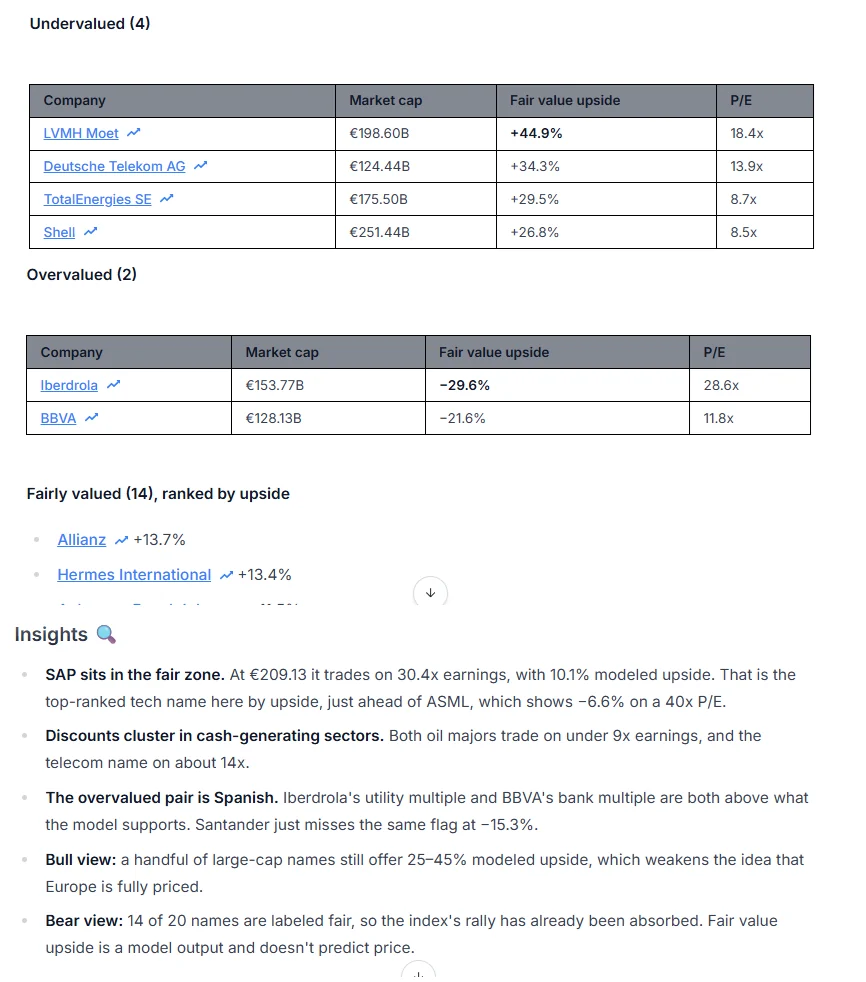
这种组合为股票选择创造了空间。STOXX Europe 600 指数中市值最大的 20 家公司组成的观察名单,可划分为高估、合理估值、低估和超值四类。SAP 即为一例:该股此前经 InvestingPro 审视后买入,并设定了较低的目标价,作为另一次可能具有吸引力的买入区间。
That combination creates room for stock selection. A watchlist of the 20 largest companies in the STOXX Europe 600 can be separated into overvalued, fairly valued, undervalued and bargain categories. SAP is one example: the stock had previously been purchased after reviewing it through InvestingPro, with a lower price target set as an area where another purchase could become attractive.
WarrenAI 通过生成包含看多理由和看空理由的结构化公司分析,增加了另一层决策支持。其目的并非取代投资者的判断,而是让投资者在决定某只欧洲股票是否真正具有吸引力前,更容易对比估值、财务数据以及双方的论据。
WarrenAI adds another layer by producing a structured company analysis with both a bull case and a bear case. The purpose is not to replace the investor’s judgment, but to make it easier to compare valuation, financial data and the arguments on both sides before deciding whether a European stock is genuinely attractive.
欧洲最大的机遇依然锁在其自身国境之内 欧洲最有力的看多理由,不仅仅在于其股市估值更便宜或集中度更低。而在于该大陆已拥有巨大的经济资源,只是未被高效利用。
Europe’s Biggest Opportunity Is Still Locked Inside Its Own Borders The strongest bullish case for Europe is not simply that its stock market is cheaper or less concentrated. It is that the continent already has enormous economic resources that are not being used efficiently.
首要问题是碎片化。欧洲本应作为单一市场运作,但企业跨境经营时仍面临不同的许可证、文书工作和规则。国际货币基金组织(IMF)估计,这些内部壁垒相当于欧盟国家之间货物贸易征收 44% 的关税,以及高达 110% 的服务贸易关税。
The first problem is fragmentation. Europe is supposed to operate as a single market, yet companies still face different licenses, paperwork and rules when doing business across borders. IMF estimates suggest that these internal barriers are equivalent to a 44% tariff on goods and an enormous 110% tariff on services between EU countries.
这意味着欧洲建立了一个巨大的共同市场,却未完全拆除其内部的无形围墙。降低这些壁垒可扩大欧洲企业可触及的规模,使成功企业更容易在整个大陆扩张,而非将每个国家视为独立市场。
That means Europe has built a huge common market without fully removing the invisible walls inside it. Reducing those barriers could increase the scale available to European companies and make it easier for successful businesses to expand across the continent rather than treating each country as a separate market.
这一潜力对服务业尤为重要,因为碎片化隐含的负担在服务业大得多。一个真正一体化的市场,不需要欧洲创造新的需求来源;它将让企业获取更多集团内部已存在的需求。欧洲拥有充足资本 —— 只是没有把足够多的资本留在国内资本市场的问题可能更为严重。欧盟家庭持有约 10 万亿欧元的银行存款。这是一笔巨大的储蓄资金池,但其中大部分仍处于欧洲企业的生产性投资之外。
The potential is particularly important for services, where the implied burden of fragmentation is much larger. A genuinely integrated market would not require Europe to invent a new source of demand; it would allow companies to access more of the demand that already exists inside the bloc. Europe Has Plenty of Capital — It Just Does Not Keep Enough of It at Home The capital-markets problem may be even larger. EU households hold around €10 trillion in bank deposits. That is an enormous pool of savings, but much of it remains outside productive investment in European companies.
与此同时,欧洲正在输出资本。2024 年,欧盟录得 4370 亿欧元的资本净流出,而美国吸引了约 1.23 万亿美元的资本净流入。这种对比表明,欧洲的问题并非资金短缺。该大陆富裕;问题在于其过多的资本投向了别处。
At the same time, Europe is exporting capital. In 2024, the European Union recorded a net capital outflow of €437 billion, while the United States attracted a net inflow of roughly $1.23 trillion. The contrast suggests that Europe’s problem is not a shortage of money. The continent is wealthy; the problem is that too much of its capital is invested somewhere else.
更深度的资本市场联盟可以改变这一局面,通过在欧洲家庭储蓄与欧洲企业之间建立更有效的渠道。与其让数万亿欧元躺在银行存款中,或任由资本流向国外,该地区可以将更多资金引导至国内企业、创新和扩张。
A deeper Capital Markets Union could change that by creating a more effective channel between European household savings and European businesses. Instead of leaving trillions in bank deposits or allowing capital to flow abroad, the region could direct more of that money toward domestic companies, innovation and expansion.
这是改革议程蕴含巨大潜力的原因之一。欧洲不一定非要创造全新的资本才能增加投资。它需要更好地利用已有的资本。
This is one of the reasons the reform agenda has so much potential. Europe does not necessarily need to generate entirely new capital before it can invest more. It needs to make better use of the capital it already has.
联合借贷可提供另一投资资金来源 机遇的第三部分在于财政层面。欧洲目前主要仍通过各成员国单独借贷:法国以法国名义、意大利以意大利名义、德国以德国名义。通过欧洲债券发挥更大的联合借贷作用,可为新技术、国防等领域的投资创造额外的财政能力。
Joint Borrowing Could Add Another Source of Investment The third part of the opportunity is fiscal. Europe still borrows largely through individual member states: France as France, Italy as Italy and Germany as Germany. A greater role for joint borrowing through Eurobonds could create additional financial capacity for investment in areas such as new technologies and defense.
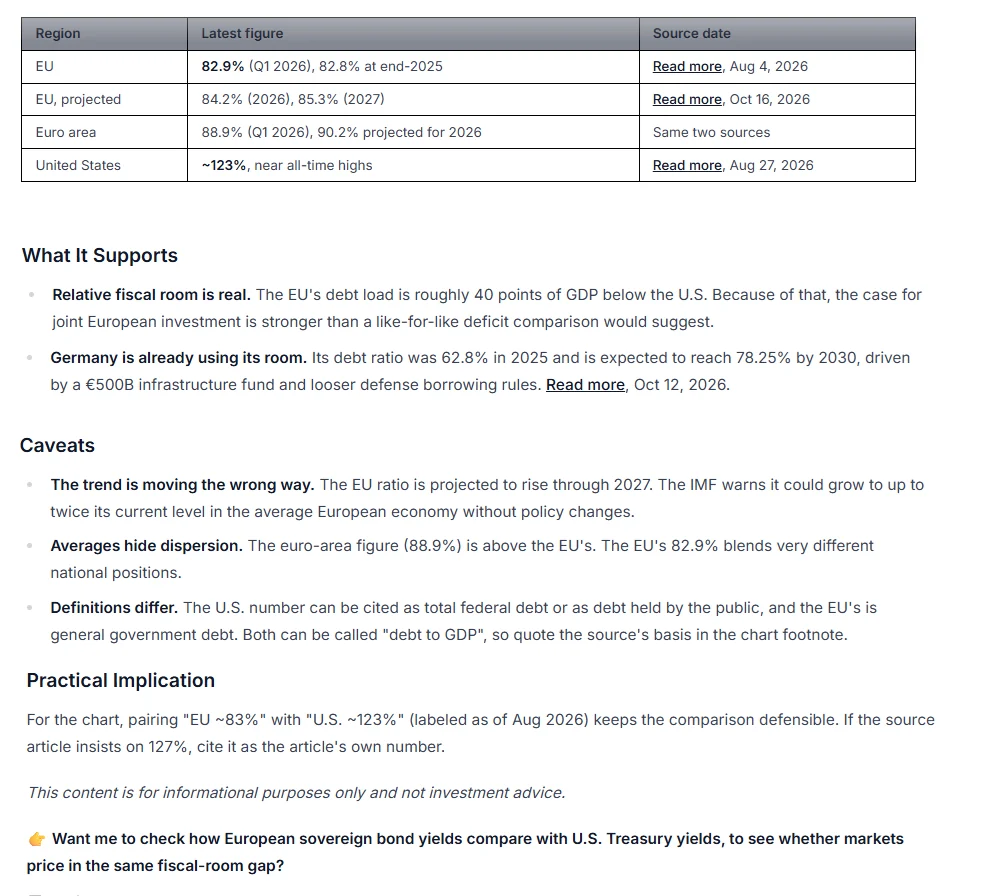
这一论据部分建立在欧洲的相对财政状况之上。欧盟各国政府债务约占 GDP 的 83%,而美国约为 124%。这并不意味着欧洲应试图追平美国的债务水平。但这确实表明,如果联合借贷与旨在提振未来增长的投资挂钩,该地区拥有更大的操作空间。
The argument rests partly on Europe’s relative fiscal position. Government debt across the EU stands at around 83% of GDP, compared with roughly 124% in the United States. That does not mean Europe should try to match American debt levels. It does suggest that the region has more room to consider joint borrowing if it is tied to investments intended to raise future growth.
结合一个更完善的单一市场和功能健全的资本市场联盟,联合借贷可以构成一个更大规模的欧洲投资周期的第三条腿。单一市场将改善企业的运营环境,更深的资本市场将动员私人储蓄,而欧元债券可以为战略项目提供公共财政火力。
Combined with a more complete single market and a functioning Capital Markets Union, joint borrowing could form the third leg of a much larger European investment cycle. The single market would improve the operating environment for companies, deeper capital markets would mobilize private savings, and Eurobonds could provide public financial firepower for strategic projects.
这些改革合在一起,可能会创造出一种可以被称为“欧洲经济海啸”的局面。这种想法并非基于欧洲突然变成一个技术密集型的美国翻版。而是基于欧洲更有效地利用其现有的市场、储蓄和财政能力。
Together, those reforms could create what might be called a European economic tsunami. The idea is not based on Europe suddenly becoming a technology-heavy version of the United States. It is based on Europe using its existing market, savings and fiscal capacity more efficiently.
风险在于欧洲未能实施改革。整个结构性论证都取决于执行情况,而这正是乐观情绪变得更为谨慎的地方。德拉吉的建议已经为提高欧洲竞争力提供了路线图,但大约两年后,这些建议中只有15.7%已完成。
The Risk Is That Europe Fails to Implement the Reforms The entire structural case depends on execution, and this is where the optimism becomes more cautious. The Draghi recommendations already provide a roadmap for making Europe more competitive, yet only 15.7% of those recommendations have been completed after roughly two years.
这种速度不足以释放上述潜力。如果基础性改革仍未完成,资本市场联盟就无法引导家庭储蓄。如果国家规则继续制造障碍,一个更有效的单一市场就无法出现。如果政治协议从未达到实施阶段,联合借贷就无法转变投资。
That pace is not enough to unlock the potential described above. A Capital Markets Union cannot redirect household savings if the underlying reforms remain incomplete. A more effective single market cannot emerge if national rules continue to create barriers. Joint borrowing cannot transform investment if political agreement never reaches the implementation stage.
这种沮丧在“欧盟公司”(EU Inc.)等倡议周围尤为明显,“欧盟公司”旨在解决企业在欧洲运营时面临的一些障碍。削弱这类倡议会增加政策制定者仍然低估竞争力问题规模的风险。
The frustration becomes especially clear around initiatives such as EU Inc., which was intended to address some of the obstacles faced by companies operating across Europe. Weakening initiatives of that kind raises the risk that policymakers still underestimate the scale of the competitiveness problem.
乐观的前景依然成立,因为解决方案在很大程度上仍掌握在欧洲自己手中。该大陆已拥有庞大的市场、巨额的家庭储蓄、低于美国的政府债务总额,以及估值倍数大幅更低的企业。欧洲无需发掘这些优势,只需更有效地整合它们。
The optimistic case remains intact because the solution is still largely within Europe’s control. The continent already has a huge market, large household savings, lower aggregate government debt than the United States and companies trading at substantially lower valuation multiples. It does not need to discover those advantages; it needs to organize them more effectively.
这就是为什么欧洲即便在所有改革到位之前也具有吸引力。其股市在2026年已跑赢美国基准指数,估值更低,且市场对人工智能的集中度较低。若欧洲最终加快落实德拉吉议程,这些现有优势将叠加更强劲的国内投资周期。
That is why Europe can be attractive even before all the reforms arrive. Its equities are already outperforming the U.S. benchmarks in 2026, valuations are lower and the market is less concentrated in AI. If Europe eventually accelerates implementation of the Draghi agenda, those existing advantages could be joined by a stronger domestic investment cycle.
因此,问题不在于欧洲是否具有潜力。潜力已清晰可见。问题在于政策制定者究竟会释放多少潜力。
The question is therefore not whether Europe has potential. The potential is already visible. The question is how much of it policymakers will actually unlock.
以下是 InvestingPro 订阅提升您股市投资表现的主要方式:ProPicks AI:每月由 AI 管理的股票精选,已有多只精选股在本月及长期表现中脱颖而出。
Below are the key ways an InvestingPro subscription can enhance your stock market investing performance: ProPicks AI: AI-managed stock picks every month, with several picks that have already taken off this month and in the long term.
Warren AI:Investing.com 的 AI 工具提供实时市场洞察、高级图表分析和个性化交易数据,助力交易者快速做出数据驱动的决策。
Warren AI: Investing.com’s AI tool provides real-time market insights, advanced chart analysis, and personalized trading data to help traders make quick, data-driven decisions.
Fair Value(合理价值):该功能汇总 17 种机构级估值模型,拨开迷雾,显示哪些股票被过度炒作、被低估或定价合理。
Fair Value: This feature aggregates 17 institutional-grade valuation models to cut through the noise and show you which stocks are overhyped, undervalued, or fairly priced.
1,200 多项财务指标触手可及:从负债比率和盈利能力到分析师盈利预期修正,您将拥有专业投资者分析股票所用的一切工具,尽在一个清爽的仪表盘中。
1,200+ Financial Metrics at Your Fingertips: From debt ratios and profitability to analyst earnings revisions, you’ll have everything professional investors use to analyze stocks in one clean dashboard.
机构级新闻与市场洞察:凭借独家头条和数据驱动分析,抢先掌握市场动向。
Institutional-Grade News & Market Insights: Stay ahead of market moves with exclusive headlines and data-driven analysis.
无干扰的研究体验:无弹窗、无杂乱、无广告。仅提供为明智决策打造的流畅工具。
A Distraction-Free Research Experience: No pop-ups. No clutter. No ads. Just streamlined tools built for smart decision-making.
Vision AI:InvestingPro 的最新功能。它利用专业级市场情报分析任何资产的图表,识别关键时间框架、技术形态和指标 —— 不到一分钟即可提供一份清晰的交易策略手册,包含最重要的关键位、情景和风险。
Vision AI: InvestingPro’s newest addition. It analyzes any asset’s chart with professional-grade market intelligence, identifying key timeframes, technical patterns, and indicators — then delivers a clear trading playbook with the levels, scenarios, and risks that matter most in under a minute. Not a Pro member yet? below at 55% off during the limited-time EARLY-BIRD SALE. Disclaimer: This article is written for informational purposes only; it does not constitute a solicitation, offer, advice, counsel or recommendation to invest as such it is not intended to incentivize the purchase of assets in any way.
还不是 Pro 会员?在限时早鸟优惠期间,点击下方以 55% 折扣订阅。
I would like to remind you that any type of asset, is evaluated from multiple perspectives and is highly risky and therefore, any investment decision and the associated risk remains with the investor.